


Even when a business is losing money, it's possible for shareholders to make money if they buy a good business at the right price. For example, biotech and mining exploration companies often lose money for years before finding success with a new treatment or mineral discovery. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
Given this risk, we thought we'd take a look at whether Europa Oil & Gas (Holdings) (LON:EOG) shareholders should be worried about its cash burn. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. Let's start with an examination of the business' cash, relative to its cash burn.
When Might Europa Oil & Gas (Holdings) Run Out Of Money?
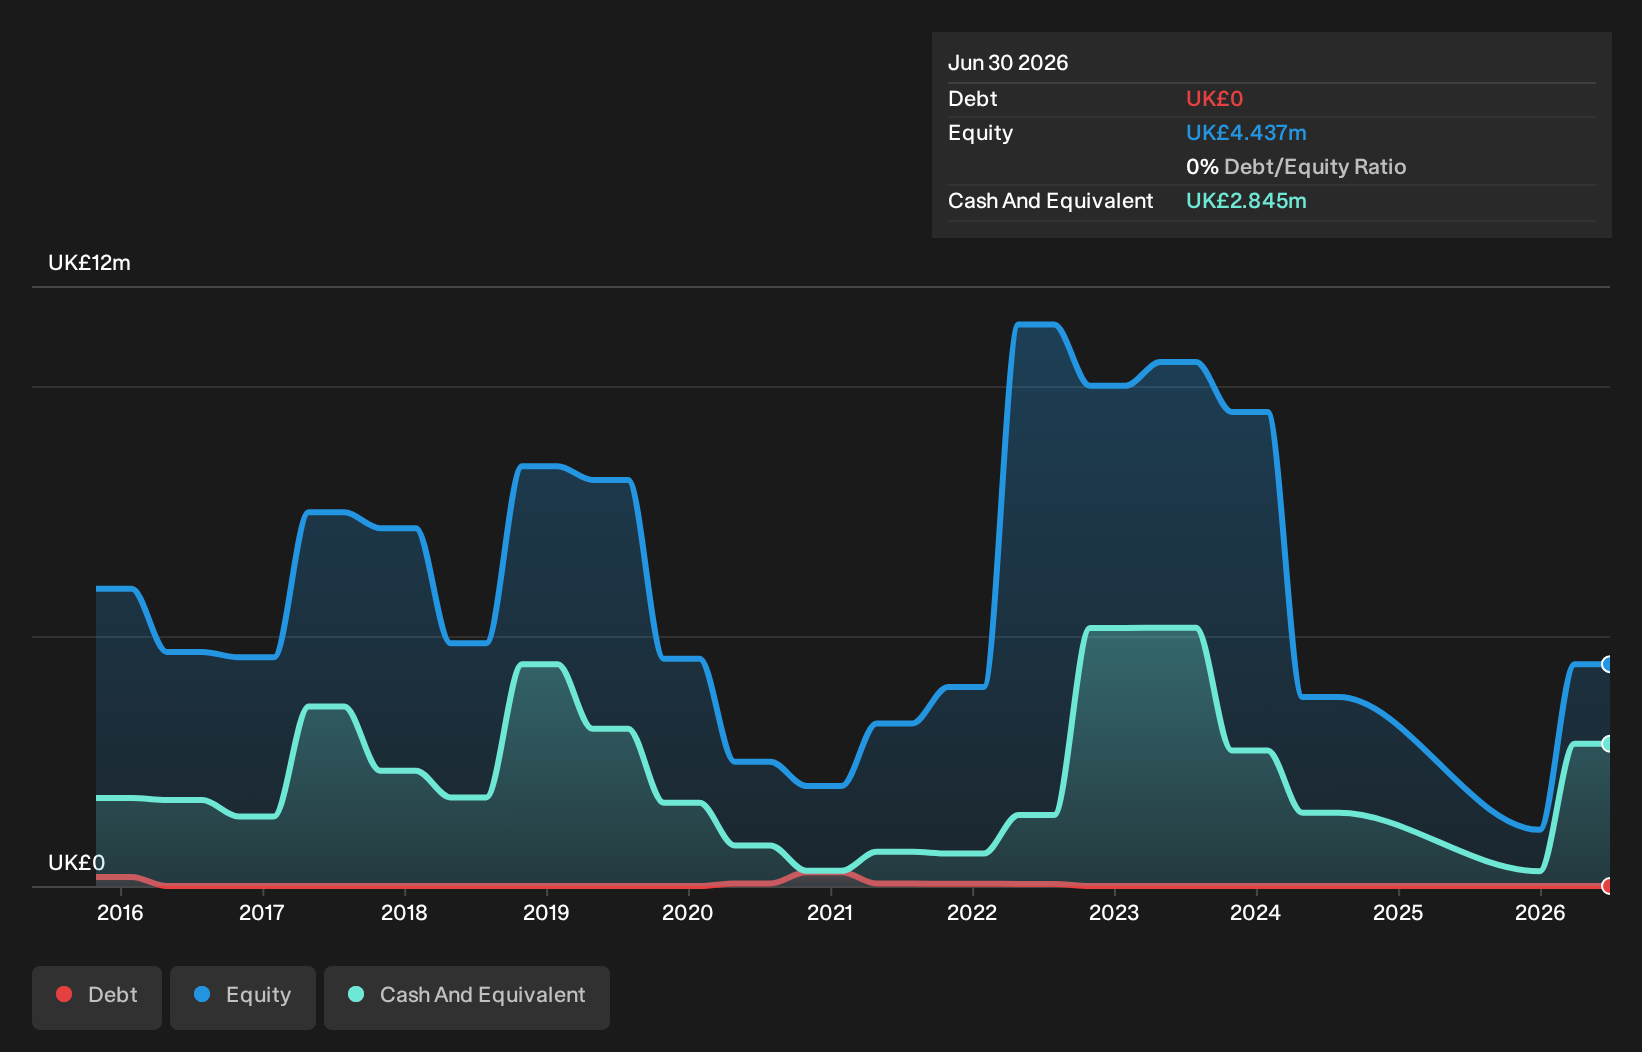
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. In June 2026, Europa Oil & Gas (Holdings) had UK£2.8m in cash, and was debt-free. Importantly, its cash burn was UK£1.5m over the trailing twelve months. Therefore, from June 2026 it had roughly 23 months of cash runway. While that cash runway isn't too concerning, sensible holders would be peering into the distance, and considering what happens if the company runs out of cash. The image below shows how its cash balance has been changing over the last few years.
See our latest analysis for Europa Oil & Gas (Holdings)
How Well Is Europa Oil & Gas (Holdings) Growing?
At first glance it's a bit worrying to see that Europa Oil & Gas (Holdings) actually boosted its cash burn by 31%, year on year. In light of that, the flat year on year operating leverage is a bit off-putting. Considering both these factors, we're not particularly excited by its growth profile. In reality, this article only makes a short study of the company's growth data. This graph of historic earnings and revenue shows how Europa Oil & Gas (Holdings) is building its business over time.
Can Europa Oil & Gas (Holdings) Raise More Cash Easily?
Even though it seems like Europa Oil & Gas (Holdings) is developing its business nicely, we still like to consider how easily it could raise more money to accelerate growth. Companies can raise capital through either debt or equity. Commonly, a business will sell new shares in itself to raise cash and drive growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Since it has a market capitalisation of UK£22m, Europa Oil & Gas (Holdings)'s UK£1.5m in cash burn equates to about 6.7% of its market value. That's a low proportion, so we figure the company would be able to raise more cash to fund growth, with a little dilution, or even to simply borrow some money.
Is Europa Oil & Gas (Holdings)'s Cash Burn A Worry?
Even though its increasing cash burn makes us a little nervous, we are compelled to mention that we thought Europa Oil & Gas (Holdings)'s cash burn relative to its market cap was relatively promising. While we're the kind of investors who are always a bit concerned about the risks involved with cash burning companies, the metrics we have discussed in this article leave us relatively comfortable about Europa Oil & Gas (Holdings)'s situation. On another note, Europa Oil & Gas (Holdings) has 5 warning signs (and 2 which can't be ignored) we think you should know about.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of companies with significant insider holdings, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.