


Global regulators are pushing fresh rules to improve transparency and cut systemic risk, which puts a spotlight on businesses that already look cleaner and more aligned with their owners. That is where fast growing Canadian companies with sizable insider stakes can draw attention. This article walks through three such stocks from our high growth, high insider alignment pool so you can see which ones might deserve a spot on your watchlist.
The three stocks below are only a starter slice of this theme. The full screen surfaces 46 additional fast growing, insider-backed businesses that also have compelling stories but are not covered here. If you want to move beyond a small sample and start sorting for your own highest conviction ideas, head straight into the Fast Growing Stocks With High Insider Ownership screener to identify, filter, and analyze the profiles that best match your checklist.
Lightspeed Commerce (TSX:LSPD)
Lightspeed Commerce runs a cloud platform that helps retailers, restaurants, and golf venues manage sales, inventory, staff, and payments. This fits tightly with this screener’s focus on subscription and payments driven growth that management and analysts both see as promising.
Lightspeed Commerce generates about US$1.24b from software and programming services, primarily recurring subscriptions and payment solutions, and has a market value around CA$1.8b.
For this theme, the draw is how Lightspeed Commerce leans on its software subscriptions and integrated payments to create recurring, transaction linked revenue that can potentially scale if merchants process more through the platform.
"While Lightspeed Commerce is benefiting from the expansion of global e-commerce and the rising adoption of cashless payments, which are driving higher transaction-based revenue and payments penetration, the company faces ongoing competition from larger, consolidated ecosystem players such as Shopify, Clover, and Amazon."
Future returns could hinge on how one quiet pressure shapes the balance between improving margins and the growth ambitions behind that payments engine.
That trade off between efficiency and ambition sits at the heart of the full narrative for Lightspeed Commerce, which unpacks how competition, pricing power, and merchant mix could reshape the story next.

Colliers International Group (TSX:CIGI)
Colliers International Group is a global commercial real estate, engineering, and investment manager that leans heavily on capital markets and investment management services tied to property deals and assets under management. This is supported by large contributions from commercial real estate at about $3.5b, engineering at roughly $1.9b, and investment management at around $562 million, on top of a market value near CA$6.5b.
Colliers International Group reflects this focus through its fee based capital markets and investment management work, where every new deal or fund can contribute to higher assets under management and more stable income, making it a key watchlist candidate for investors who prioritize growth.
"The growing interest from institutional and private wealth channels in alternative asset classes such as data centers, student housing, infrastructure, and credit solutions is driving segment diversification and AUM growth in the investment management business, supporting future recurring fee revenue and higher net margins."
The main point of tension for Colliers International Group is how that expanding opportunity set interacts with one funding related pressure that could significantly influence future profitability.
If that funding squeeze is what you are watching, the full narrative for Colliers International Group shows how Colliers International Group could keep fee income accelerating while risk and reward decouple.

Cascades (TSX:CAS)
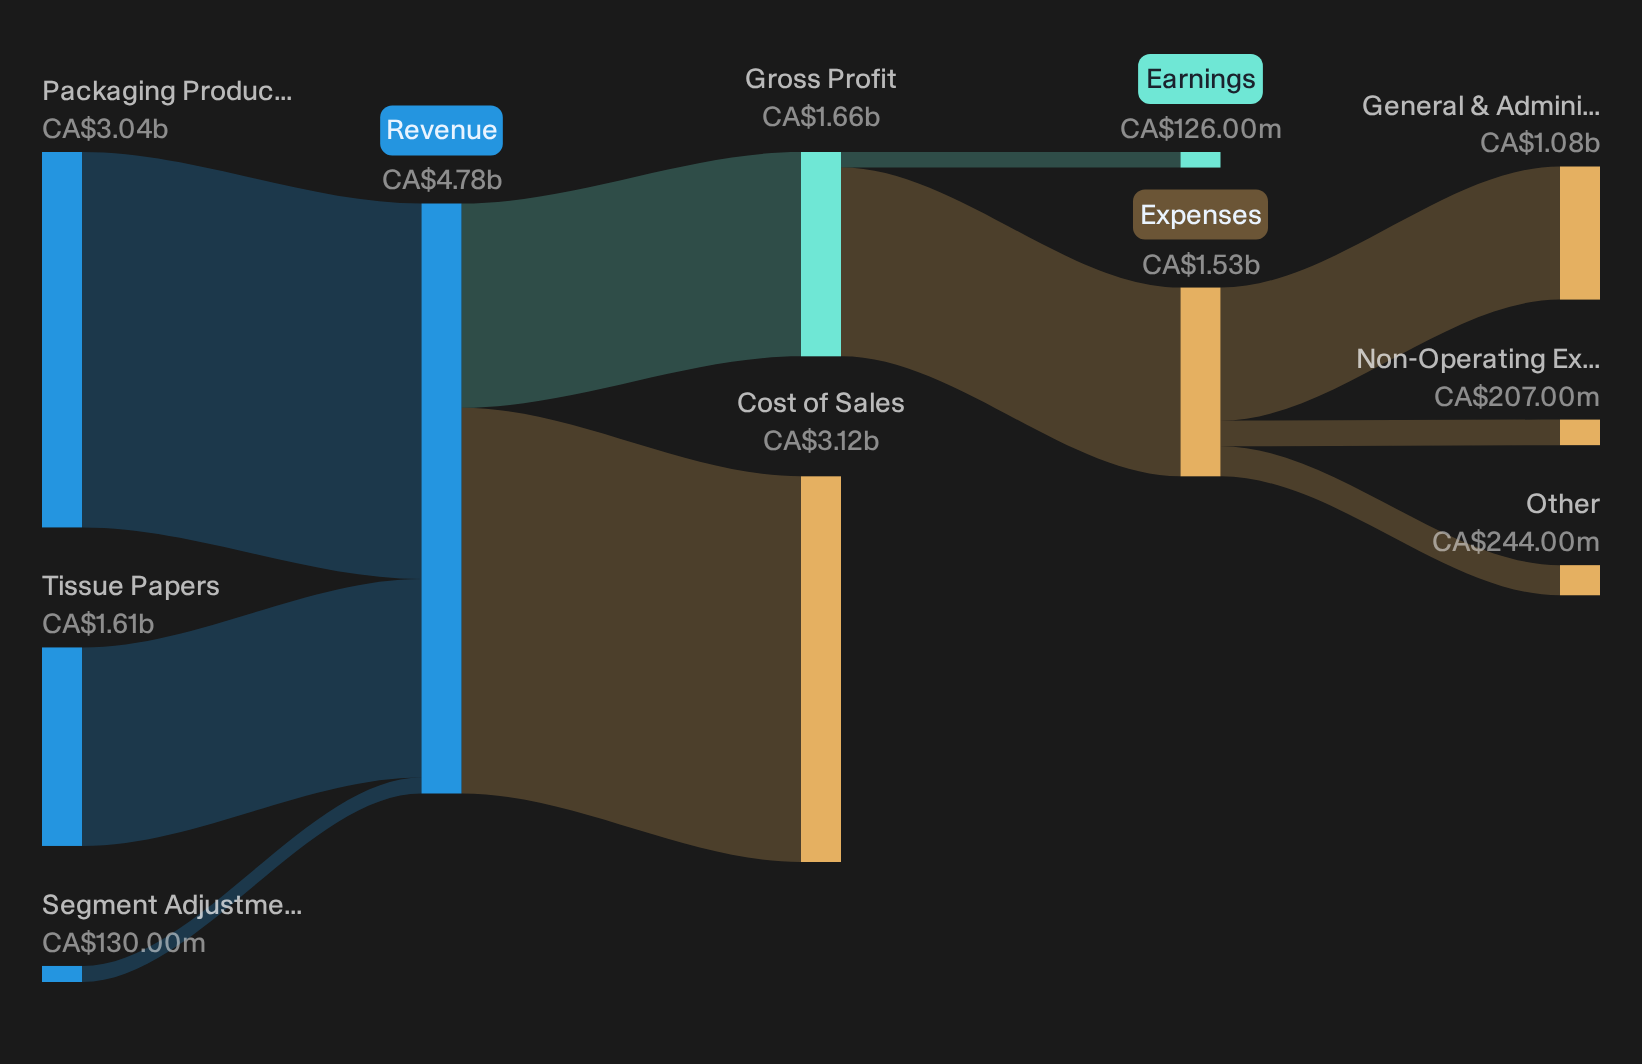
Cascades is a CA$1.9b packaging and tissue producer. Its growth angle for this screener comes from its e-commerce and food packaging line within the CA$3.0b Packaging Products segment, alongside a CA$1.6b Tissue Papers arm that keeps the overall business diversified.
Cascades taps directly into the fast growing, high insider alignment theme through its e-commerce and food packaging products, where management optimism and analyst expectations both focus on earnings power rather than flashy top line targets.
"Continued ramp up at the Bear Island mill toward Greenpac level efficiencies, combined with targeted reductions in chemical and material usage, should lift Packaging segment productivity and support structurally higher EBITDA margins."
What happens to Cascades’ valuation story if one less visible pressure on its ability to sustain those margin gains starts to bite harder?
If that risk is on your radar, the full narrative for Cascades explains how Cascades’ margin story, capital demands, and insider alignment could be quietly accelerating or stalling the thesis.
Curious About What You Might Be Missing?
Fresh ideas move first. Watch where breakout momentum is building and which stories are still under the radar for now. Do not delay, get in early.
- Spot resilient businesses before the crowd catches on by scanning the list of solid balance sheet and fundamentals (7 results) that already show disciplined financial footing and cleaner fundamentals.
- Ride structural shifts in energy demand by tracking the 19 nuclear energy infrastructure stocks that could benefit as infrastructure spending and grid reliability stay in focus.
- Stay ahead of the next materials squeeze by reviewing the curated 36 best rare earth metal stocks powering batteries, electronics, and advanced manufacturing worldwide.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com