


Smith & Nephew plc (LON:SN.) is about to trade ex-dividend in the next 4 days. The ex-dividend date is two business days before a company's record date in most cases, which is the date on which the company determines which shareholders are entitled to receive a dividend. The ex-dividend date is important because any transaction on a stock needs to have been settled before the record date in order to be eligible for a dividend. Thus, you can purchase Smith & Nephew's shares before the 1st of October in order to receive the dividend, which the company will pay on the 6th of November.
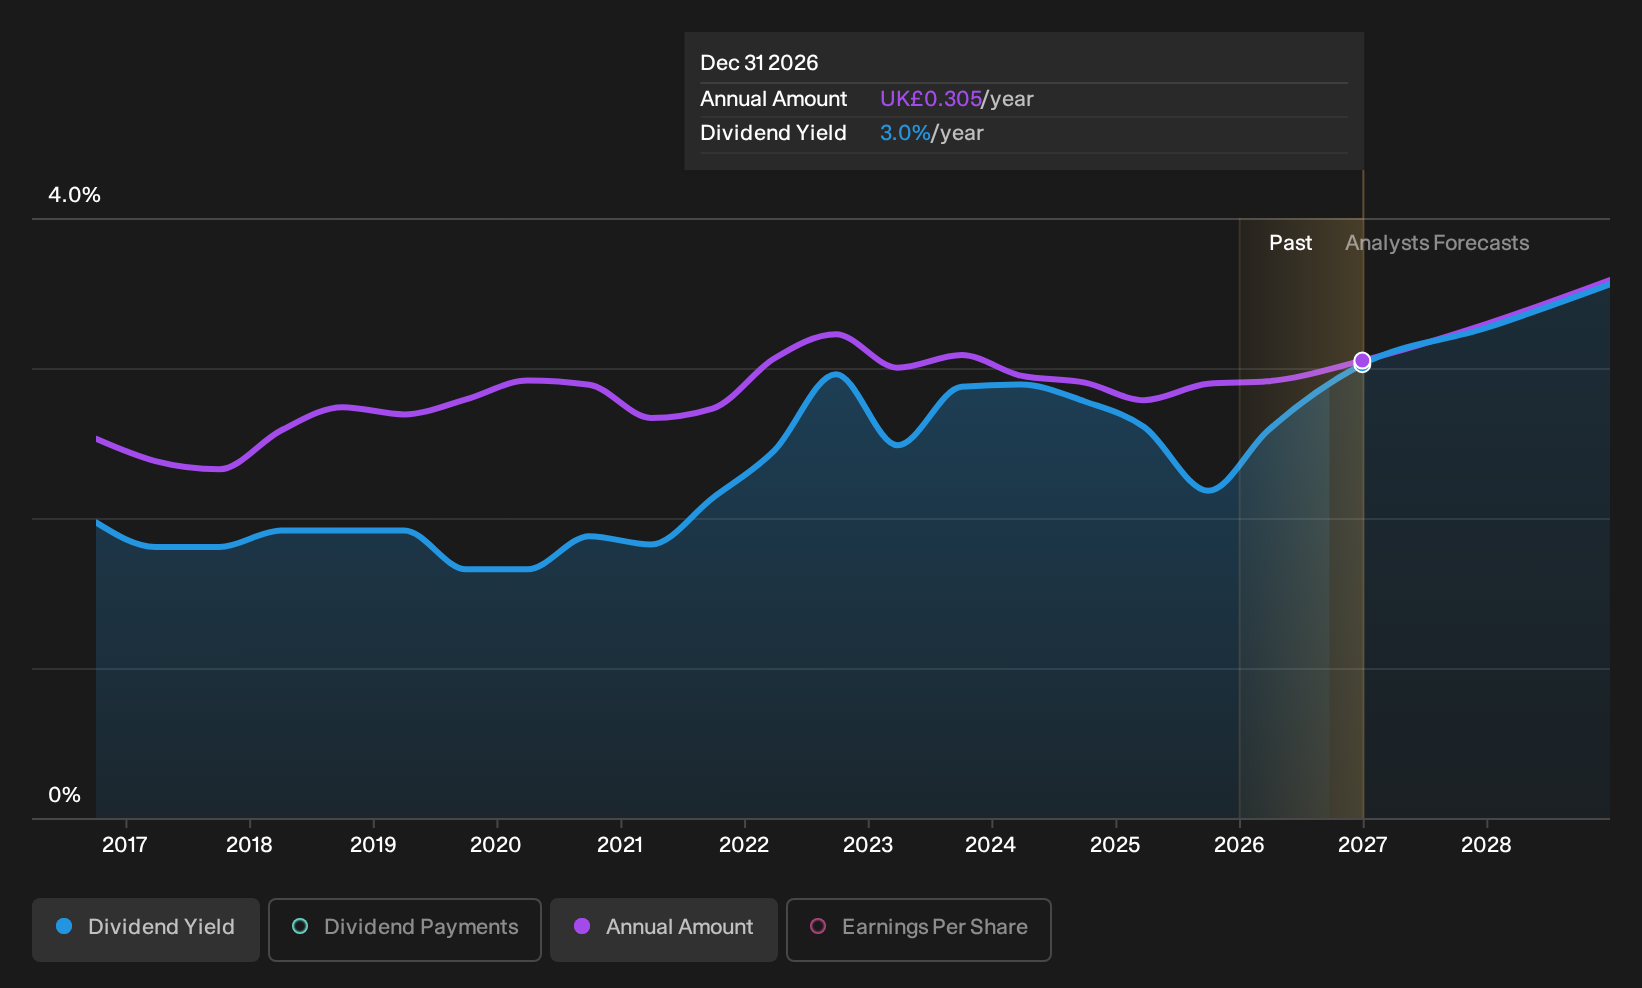
The company's next dividend payment will be US$0.156 per share, and in the last 12 months, the company paid a total of US$0.39 per share. Looking at the last 12 months of distributions, Smith & Nephew has a trailing yield of approximately 2.9% on its current stock price of UK£10.08. We love seeing companies pay a dividend, but it's also important to be sure that laying the golden eggs isn't going to kill our golden goose! So we need to check whether the dividend payments are covered, and if earnings are growing.
Dividends are usually paid out of company profits, so if a company pays out more than it earned then its dividend is usually at greater risk of being cut. Smith & Nephew paid out 53% of its earnings to investors last year, a normal payout level for most businesses. A useful secondary check can be to evaluate whether Smith & Nephew generated enough free cash flow to afford its dividend. It distributed 39% of its free cash flow as dividends, a comfortable payout level for most companies.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
View our latest analysis for Smith & Nephew
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. Investors love dividends, so if earnings fall and the dividend is reduced, expect a stock to be sold off heavily at the same time. This is why it's a relief to see Smith & Nephew earnings per share are up 8.1% per annum over the last five years. Decent historical earnings per share growth suggests Smith & Nephew has been effectively growing value for shareholders. However, it's now paying out more than half its earnings as dividends. If management lifts the payout ratio further, we'd take this as a tacit signal that the company's growth prospects are slowing.
Many investors will assess a company's dividend performance by evaluating how much the dividend payments have changed over time. Since the start of our data, 10 years ago, Smith & Nephew has lifted its dividend by approximately 2.4% a year on average. It's encouraging to see the company lifting dividends while earnings are growing, suggesting at least some corporate interest in rewarding shareholders.
The Bottom Line
From a dividend perspective, should investors buy or avoid Smith & Nephew? While earnings per share growth has been modest, Smith & Nephew's dividend payouts are around an average level; without a sharp change in earnings we feel that the dividend is likely somewhat sustainable. Pleasingly the company paid out a conservatively low percentage of its free cash flow. Overall we're not hugely bearish on the stock, but there are likely better dividend investments out there.
So while Smith & Nephew looks good from a dividend perspective, it's always worthwhile being up to date with the risks involved in this stock. Case in point: We've spotted 1 warning sign for Smith & Nephew you should be aware of.
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.