


- Takeda Pharmaceutical recently secured FDA Priority Review for its oral TYK2 inhibitor zasocitinib in moderate to severe plaque psoriasis and outlined extensive oncology data presentations at the October 2026 ESMO Congress, covering late stage assets arcotatug tavatecan and TAK-928 plus real world analyses for ALUNBRIG and FRUZAQLA.
- The combination of a potential new dermatology product and upcoming oncology readouts points to Takeda Pharmaceutical leaning heavily on late stage R&D execution across multiple therapy areas to support future portfolio depth and operational focus.
- We will now look at how Takeda Pharmaceutical's investment narrative could be influenced by FDA Priority Review for zasocitinib.
Takeda Pharmaceutical Investment Narrative Recap
To own Takeda Pharmaceutical, you need to be comfortable with a story that leans heavily on late stage R&D to offset pressure from generics, pricing reform and a balance sheet still carrying Shire era debt. The operating question is whether pipeline execution across immunology and oncology can support a return to sustainable profitability while funding a dividend that is not covered by current earnings.
In the near term, the zasocitinib FDA Priority Review looks like the clearest single catalyst because it opens up a fresh oral option in dermatology if approved. The flip side is pipeline risk. Any setback for key programs such as zasocitinib or major oncology assets would make it harder for Takeda Pharmaceutical to counter generic erosion and service debt comfortably.
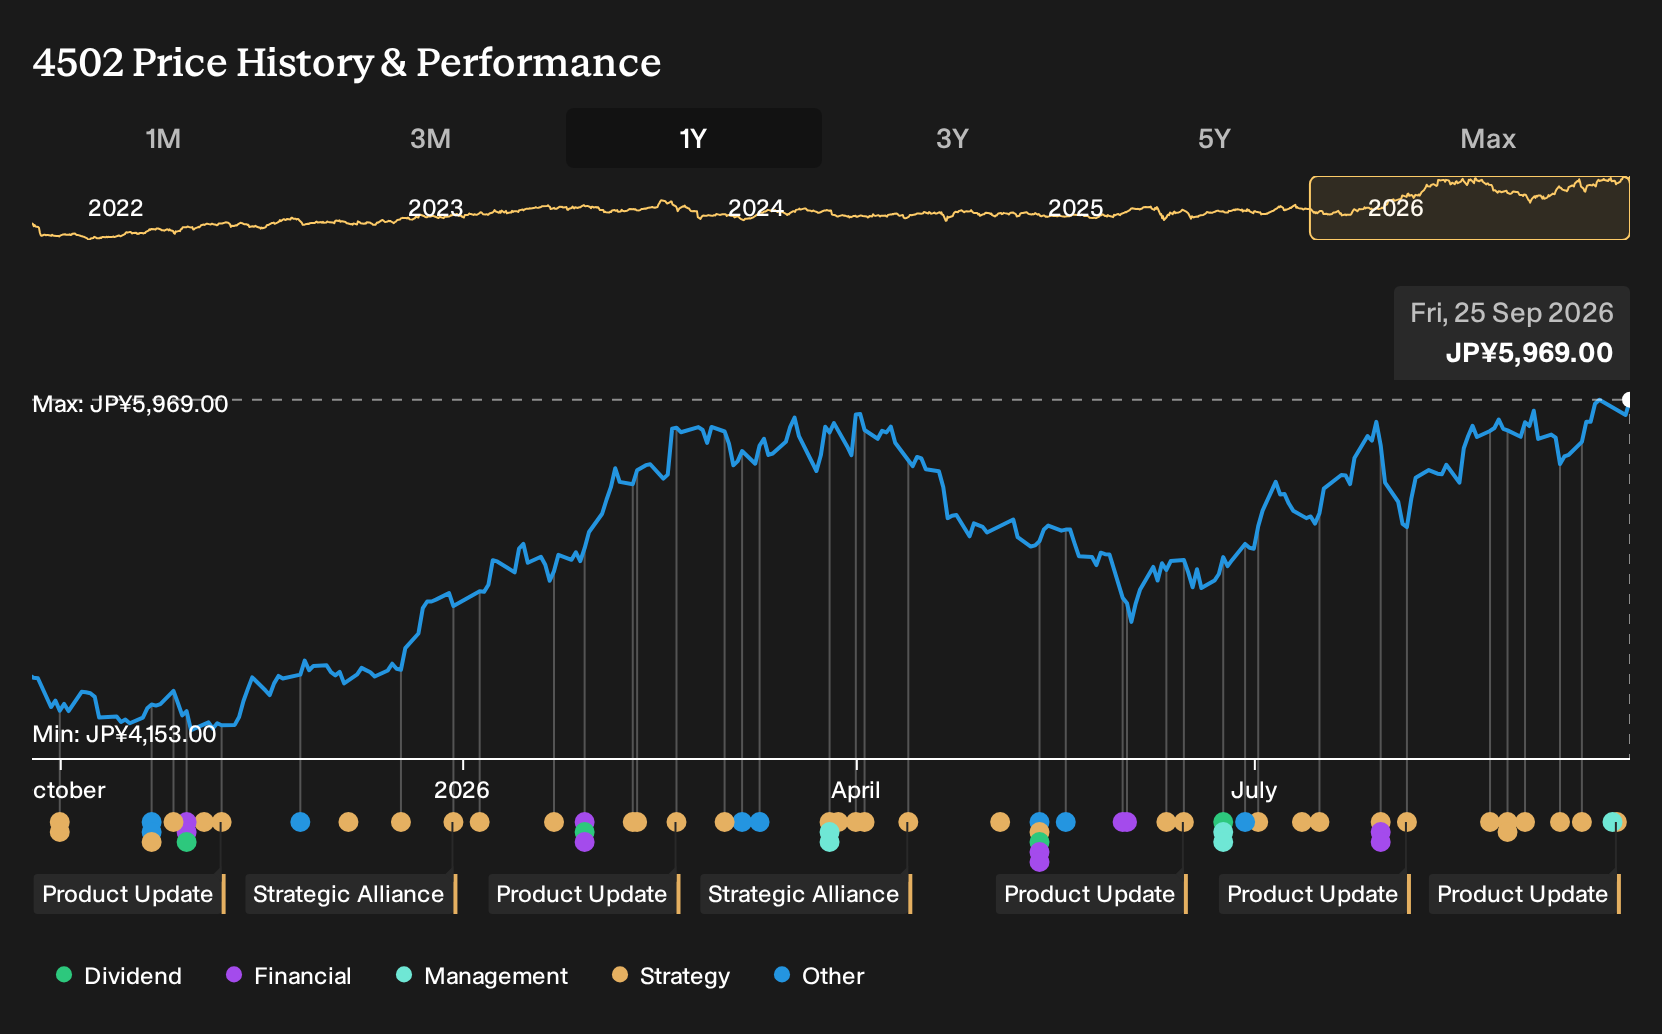
The Priority Review for zasocitinib matters most right now. It brings a potential new oral TYK2 product into focus at the same time Takeda Pharmaceutical is highlighting oncology data at ESMO for arcotatug tavatecan, TAK-928, ALUNBRIG and FRUZAQLA. Together, that keeps attention on whether future launches can help shift the business away from older, exposed revenue sources.
Execution risk is real. Late stage drugs carry the possibility of regulatory delay, safety questions or weaker than expected differentiation once real world data arrive. For investors, the practical read through is straightforward: watch FDA interactions around zasocitinib and the upcoming ESMO data flow, because those are the clearest near term signposts for how much of Takeda Pharmaceutical’s long term pipeline narrative is turning into commercial reality.
Takeda Pharmaceutical's current analyst script points to revenues of ¥4,976.1b and earnings of ¥401.3b by 2029. This projection is built on assumed annual top line growth of 2.5% and a swing in net income of roughly ¥564.7b, from an earnings loss of ¥163.4b today to that projected profit level.
Uncover why Takeda Pharmaceutical's fair value indicates an 11% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts the spotlight on oncology spending instead of zasocitinib. The most cautious analysts worry that funding programs like arcotatug tavatecan and TAK-928 could keep costs high and leave earnings closer to ¥274.4b on about ¥4,750.4b of revenue by 2029. These pre news forecasts are far more conservative than consensus, so use them as a prompt to compare several viewpoints and decide how the new dermatology and ESMO updates might reshape your own expectations for Takeda Pharmaceutical.
Explore 2 other Takeda Pharmaceutical fair value estimates, including one that suggests it could be worth just ¥6603.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Takeda Pharmaceutical research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Takeda Pharmaceutical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Takeda Pharmaceutical's overall financial health at a glance.
Looking for more Takeda Pharmaceutical sized ideas?
If the Takeda Pharmaceutical story has you thinking about portfolio upgrades, it can help to scan a wider field of opportunities using the Simply Wall St Screener.
- For investors who want mispriced quality at the top of their list, start with a focused set of opportunities by reviewing 18 high quality undervalued stocks.
- If capital preservation is your first filter, narrow the field to sturdier balance sheets by checking out a targeted list of solid balance sheet and fundamentals (22 results).
- When you are hunting for future market leaders that still fly under the radar, broaden your research with a hand picked pool of 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com