


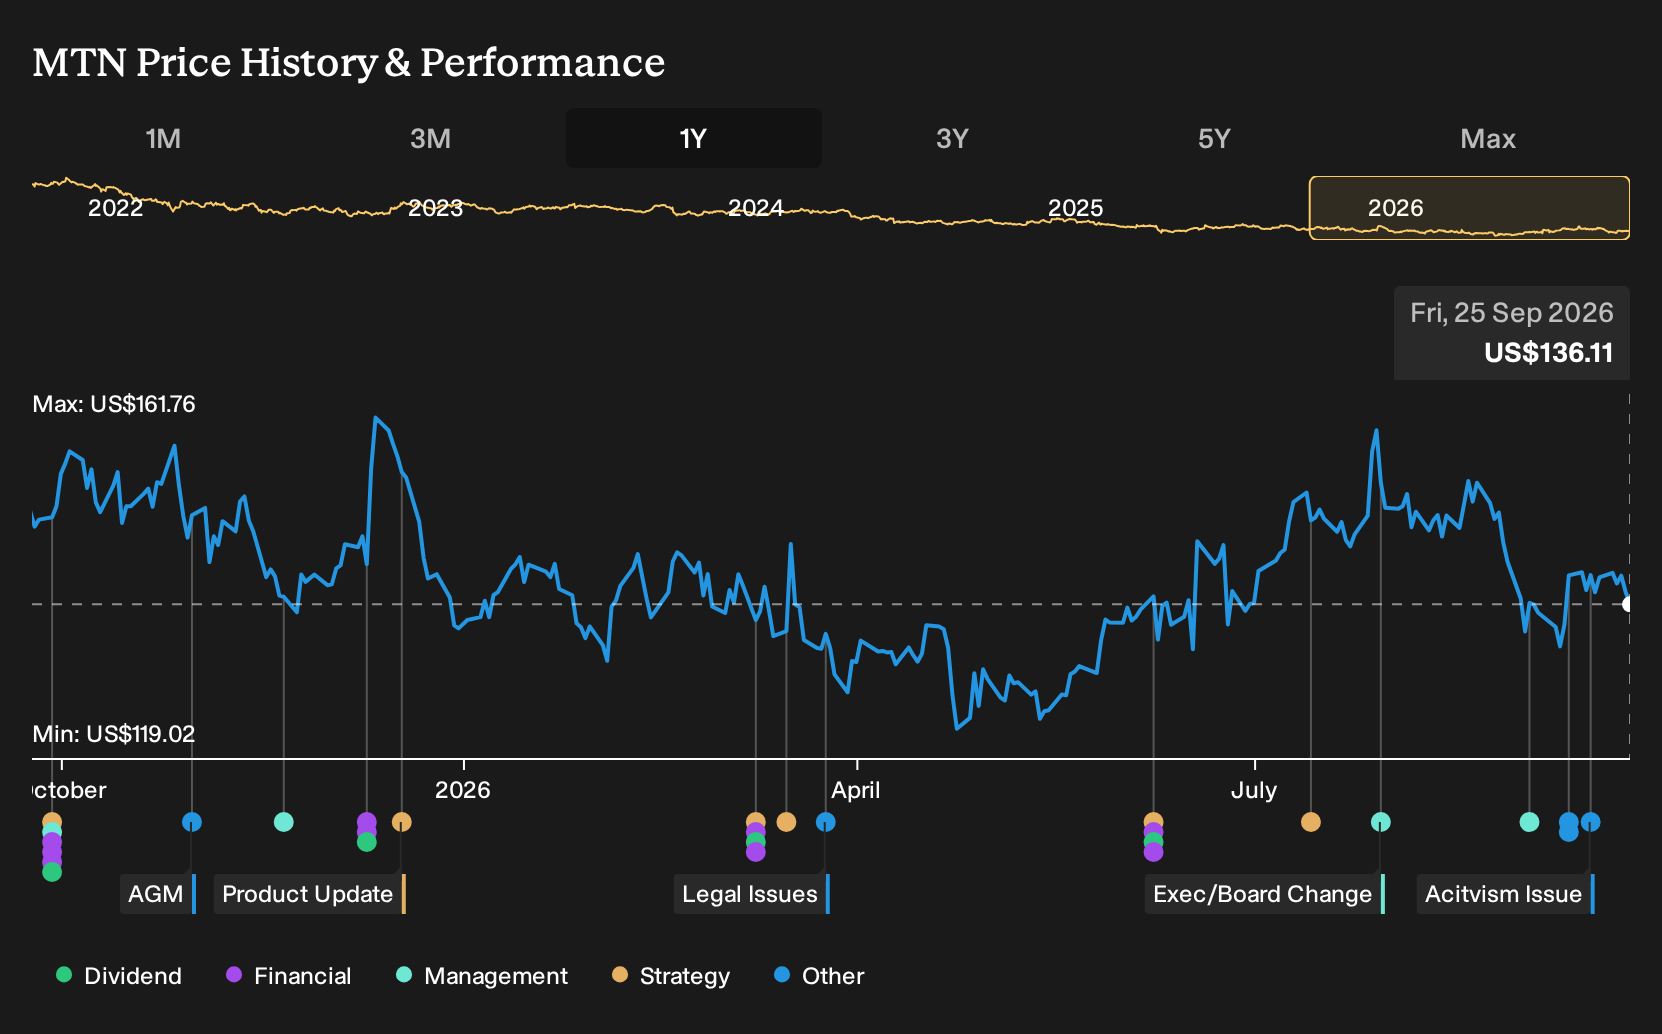
- Oasis Management has already nominated Robert A. Chapek, M. Ashton Hudson, Bryce Roberts, and Picabo Street to Vail Resorts' Board for the 2026 Annual Meeting, arguing that the ski operator’s 42 mountain resorts and hospitality assets are not fully reflected in its current valuation.
- The activist fund is pushing for a refreshed Board to sharpen Vail Resorts' execution on guest experience, pricing, food and beverage, resort utilization, and community ties. These areas directly target the operating levers that support the company’s long-term earnings profile.
- This article will now examine how Vail Resorts' investment narrative could evolve if Oasis succeeds in advancing a refreshed Board with different priorities.
Scan how activist pressure at Vail Resorts compares with other opportunities by reviewing a curated list of 30 resilient stocks with low risk scores that may be less exposed to single-company governance shakeups.
Vail Resorts Investment Narrative Recap
To own Vail Resorts, you need to believe its 42 mountain resorts and lodging assets can support consistent demand across volatile winter seasons and uneven visitation patterns. The short term swing factor sits in fiscal 2026 performance. Management already cut Resort EBITDA guidance after difficult North American weather, so Oasis’s board campaign does not immediately change that near term earnings overhang.
The bigger swing risk today remains visitation normalization and weaker destination trips to Western resorts, plus pressure on margins with net profit at 5.5% versus 9.7% last year. Oasis’s push on pricing, guest experience, and utilization could influence future decisions, but operational delivery and weather still drive the nearer term outcome.
The upcoming fourth quarter fiscal 2026 earnings release on September 28 now matters more in light of the Oasis letter. Vail Resorts has flagged stable summer demand in North American lodging and mountain operations, stronger trends in Australia, and ongoing cost efficiency work toward a planned US$100 million in annualized savings by the end of fiscal 2026.
At the same time, a weaker North American winter already weighed on full year earnings expectations and pulled down the Resort EBITDA outlook. This ties directly into concerns around visitation patterns, foreign exchange headwinds, and dividend coverage. How management talks about guest behavior, Epic Pass pricing, and cost control on the call will frame both the activist debate and the key operational catalysts for the next season.
Vail Resorts' narrative projects US$3.2b revenue and US$310.0 million earnings by 2029. This assumes 4.2% yearly revenue growth and an earnings increase of about US$153.2 million from US$156.8 million today.
Uncover why Vail Resorts' fair value indicates a 9% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The biggest swing factor in the alternate view is climate risk. Some of the lowest Vail Resorts analysts were already baking in only 3.0% annual revenue growth and earnings of about US$231.7 million by 2029, versus the consensus of US$310.0 million. That is a much more cautious story. With Oasis now pushing for board change, those forecasts might shift again, so treat this as your cue to compare several narratives, not just one.
Explore 2 other Vail Resorts fair value estimates, including one that suggests it could be worth just $148.50.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Vail Resorts research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Vail Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vail Resorts' overall financial health at a glance.
Looking For More Ideas Beyond Vail Resorts?
If the Vail Resorts story has you rethinking concentration risk or hunting for different risk reward profiles, it can help to line it up against a broader watchlist built with the Simply Wall St Screener.
- For investors who want quality on sale, use the screener to hunt for companies trading on more modest valuations with solid fundamentals by checking out 32 high quality undervalued stocks.
- If balance sheet strength matters most to you, focus on businesses with conservative debt levels and resilient cash positions through the list of solid balance sheet and fundamentals (24 results).
- Income focused readers who prefer to get paid while they wait can zero in on higher yielding opportunities with the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com