


Adient (NYSE:ADNT) is reshaping its finance leadership after announcing that director Peter Carlin will leave the board to become vice president, finance, before taking over as chief financial officer in November.
Adient’s recent CFO announcement lands against a tougher backdrop for holders, with the share price at US$17.63 after a 1-day share price gain of 3.71% but a 30-day share price decline of 7.01%. The 1-year total shareholder return is down 28.45%, pointing to fading momentum and a market that is still recalibrating its view of the business’s risk and recovery profile.
Scan how Adient compares with other auto suppliers undergoing leadership or valuation resets by reviewing our curated list of 16 high quality undiscovered gems.
Adient is effectively swapping an investor’s seat in the boardroom for control of the finance engine. Is that a signal about underlying earnings power, or just an attempt to reset how the market feels about the stock’s US$17.63 price tag?
Most Popular Narrative: 44% Undervalued
On Simply Wall St’s most followed view, Adient’s fair value of $31.42 sits well above the recent $17.63 share price. This puts a lot of weight on how convincingly new leadership can translate product wins into steadier earnings.
Adient's strategic focus on U.S. onshoring, underpinned by its unmatched production footprint (75% of North American capacity in the U.S. versus 55% for its nearest competitor), is already translating into significant net new business wins with Asia-based and domestic OEMs. Minimal incremental capital needs mean this will deliver highly accretive incremental revenue and margin improvement as volumes ramp into FY2026-27.
See why 5 investors see Adient as 44% undervalued.
Result: Fair Value of $31.42 (UNDERVALUED)
Still, Adient’s reliance on restructuring in Europe and its exposure to shifting OEM sourcing decisions could quickly challenge the undervaluation story if execution disappoints.
Find out about the key risks to this Adient narrative.
Another View On Adient’s Valuation
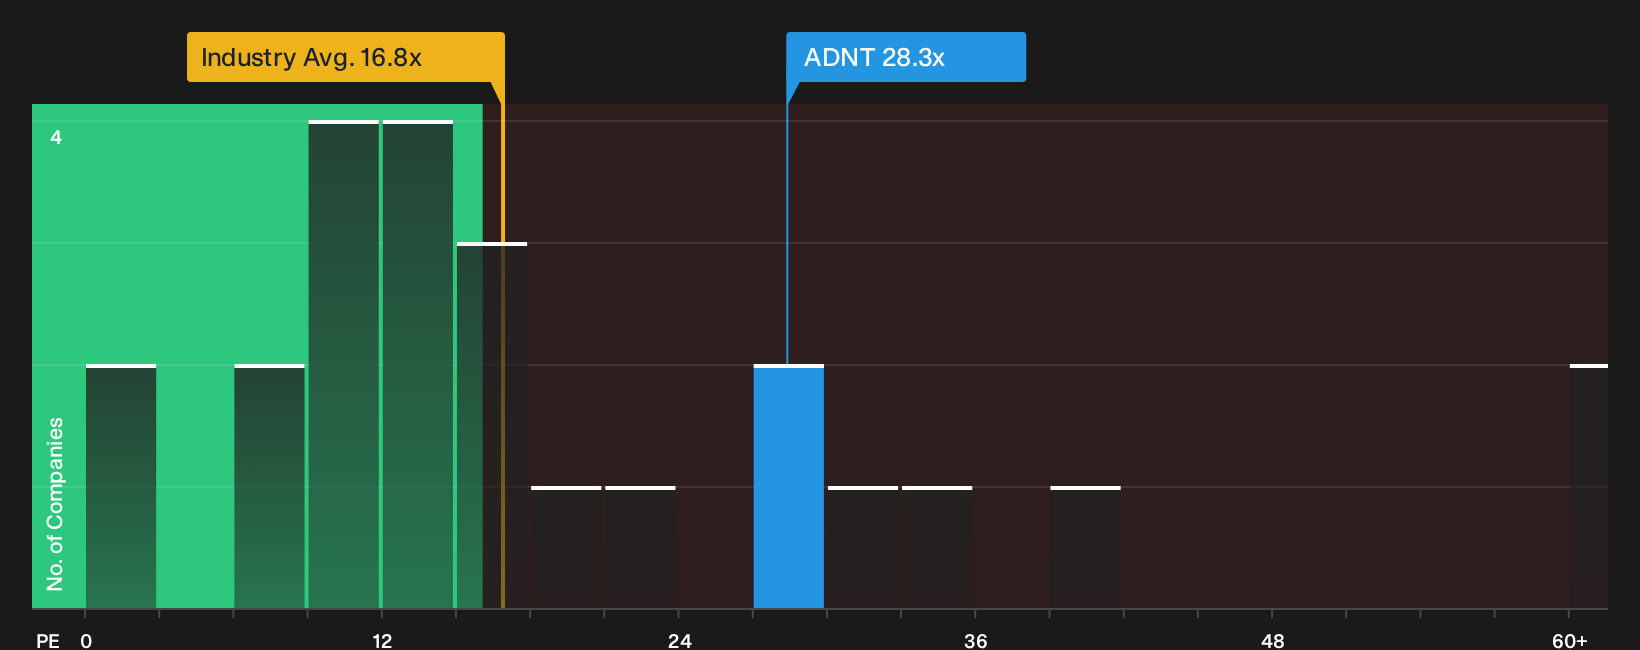
The first take paints Adient as undervalued at $17.63 relative to a $31.42 fair value. A different lens tells a more cautious story. On a P/E basis, the stock trades at about 28.3x, above the US Auto Components industry on 16.3x and above a fair ratio of 28x. That gap points to less of a clear bargain and more of a question about how much execution risk you want to carry.
For a closer look at what the numbers imply for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Adient can be confusing, so treat this as a prompt to move fast, review the underlying figures yourself, and build your own stance. To see both sides of the story in one place, check out the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Adient?
If Adient has you rethinking where you deploy capital next, do not stop at a single ticker. Broaden your watchlist with focused stock shortlists built from rigorous screening.
- Target quality at a discount by reviewing companies on our 32 high quality undervalued stocks that pair stronger fundamentals with valuations that still look compressed.
- Prioritise resilience by scanning the list of solid balance sheet and fundamentals (24 results) for businesses with cleaner debt profiles and sturdier financial footing.
- Hunt for tomorrow’s quiet outperformers through the 16 high quality undiscovered gems before wider attention crowds into the same opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com