


Recent reports pointing to expanding residential HVAC and heat pump markets, combined with a favorable mention from Wells Fargo analyst Stephen Tusa, have pushed Trane Technologies (NYSE:TT) into sharper focus for many investors.
Trane Technologies has seen a sharp pickup in attention, with the latest share price at US$454.44 and a 1-day share price return of 3.63% and 7-day share price return of 5.90%, even though the 90-day share price return is down 4.91%. That short-term bump sits against a 14.18% year-to-date share price return and a 3-year total shareholder return of 130.79%. This suggests momentum has cooled recently, while long-term holders have still seen very strong gains as interest in energy efficient HVAC and fresh analyst commentary have come through.
Scan beyond Trane Technologies and size up other potential HVAC beneficiaries with our hand-picked 40 power grid technology and infrastructure stocks.
After that quick surge in Trane Technologies shares and with analysts’ targets and intrinsic models pointing higher than the current US$454.44 price, the real tension is where fair value actually sits. How wide is the gap?
Most Popular Narrative: 13% Undervalued
On the widely followed narrative, Trane Technologies screens as undervalued, with a fair value estimate of $521.51 compared with the latest close at $454.44, which puts the current enthusiasm in a different light.
Trane Technologies is poised for significant growth in the Commercial HVAC segment, with strong bookings and pipeline visibility indicating sustainable revenue growth. The focus on energy efficiency and the ability to deliver attractive paybacks for customers could bolster future sales and market share, positively impacting revenue.
See why 36 investors see Trane Technologies as 13% undervalued.
Result: Fair Value of $521.51 (UNDERVALUED)
Still, Trane Technologies depends heavily on strength in data centers and healthcare, and prolonged weakness in its Transport segment could quickly challenge the view that it is 13% undervalued.
Find out about the key risks to this Trane Technologies narrative.
Another View On Trane Technologies’ Valuation
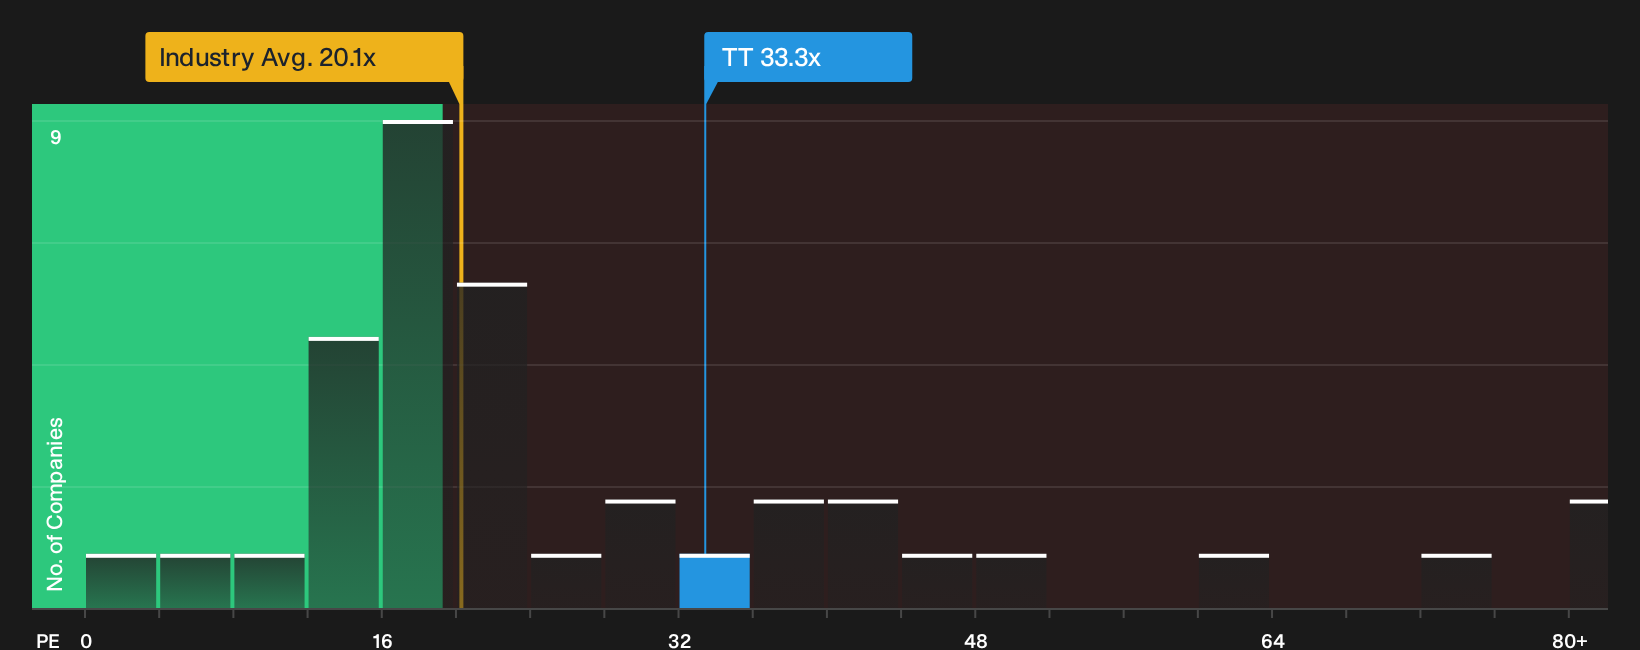
Fair value models point to Trane Technologies trading 9.4% below an estimated worth, yet the P/E ratio of 33.3x tells a different story. The stock trades above a 31.8x fair ratio, the 20.1x industry average, and a 29.4x peer level. Is that a quality premium or valuation risk?
To see how those P/E gaps could close over time and what that might mean for Trane Technologies, take a closer look at the valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Trane Technologies is mixed enough that it pays to interrogate the numbers yourself and not just the headlines. To move quickly, review the upside factors in 3 key rewards.
Looking for more investment ideas beyond Trane Technologies?
If Trane Technologies has sharpened your focus, do not stop there. Broader opportunity often sits just outside the headline stock everyone is watching.
- Target resilient compounding potential by scanning a 32 high quality undervalued stocks that combines quality fundamentals with prices that sit below estimated worth.
- Strengthen capital preservation by filtering for a 30 resilient stocks with low risk scores that screens out fragile balance sheets and erratic earnings profiles.
- Spot future market favorites early by running through a 16 high quality undiscovered gems that highlights strong businesses still flying under most investors’ radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com