


Avolta (SWX:AVOL) just announced a partnership with Hawaii’s Department of Transportation to revamp dining across three major island airports, tying its food and beverage presence more closely to Hawaii’s local culinary brands.
Avolta’s latest Hawaii agreement lands as the share price trades at CHF42.72, with a 1-day share price return of 2.15% and a 7-day share price return of 2.10%. This follows a 90-day share price decline of 20.52% and a 1-year total shareholder return decline of 3.10%, suggesting short term momentum is improving while longer term sentiment remains more cautious.
Scan how Avolta compares with other travel and consumer stocks that are trying to turn recent share price pressure into a rebound using the hand picked 182 high quality undervalued stocks.
Avolta now trades at CHF42.72 while analyst targets and intrinsic estimates point to a higher midpoint, raising a simple question: Is the current discount a genuine value gap or a fair reflection of the risk profile?
Most Popular Narrative: 18% Undervalued
Avolta is trading at CHF42.72 against a widely followed fair value estimate of about CHF51.94, which frames the current Hawaii deal against a wider story of long term contract wins and measured expectations for growth and profitability.
Expansion into high-growth markets, particularly Asia-Pacific and the Middle East, is expected to increase Avolta's exposure to rising air travel volumes and international passenger flows, thus supporting sustained revenue growth and diversifying earnings streams. The strong consumer shift toward premium, experiential, and localized travel retail (as seen in high-margin products, flexible "sense of place" stores, and hybrid F&B/retail formats) is anticipated to drive higher average transaction value and support margin expansion.
See why 9 investors see Avolta as 18% undervalued.
Result: Fair Value of CHF51.94 (UNDERVALUED)
Still, the Avolta story can change quickly if airport concession renewals become more competitive or if geopolitical shocks hit passenger flows harder than analysts expect.
Find out about the key risks to this Avolta narrative.
Another View On Avolta’s Valuation
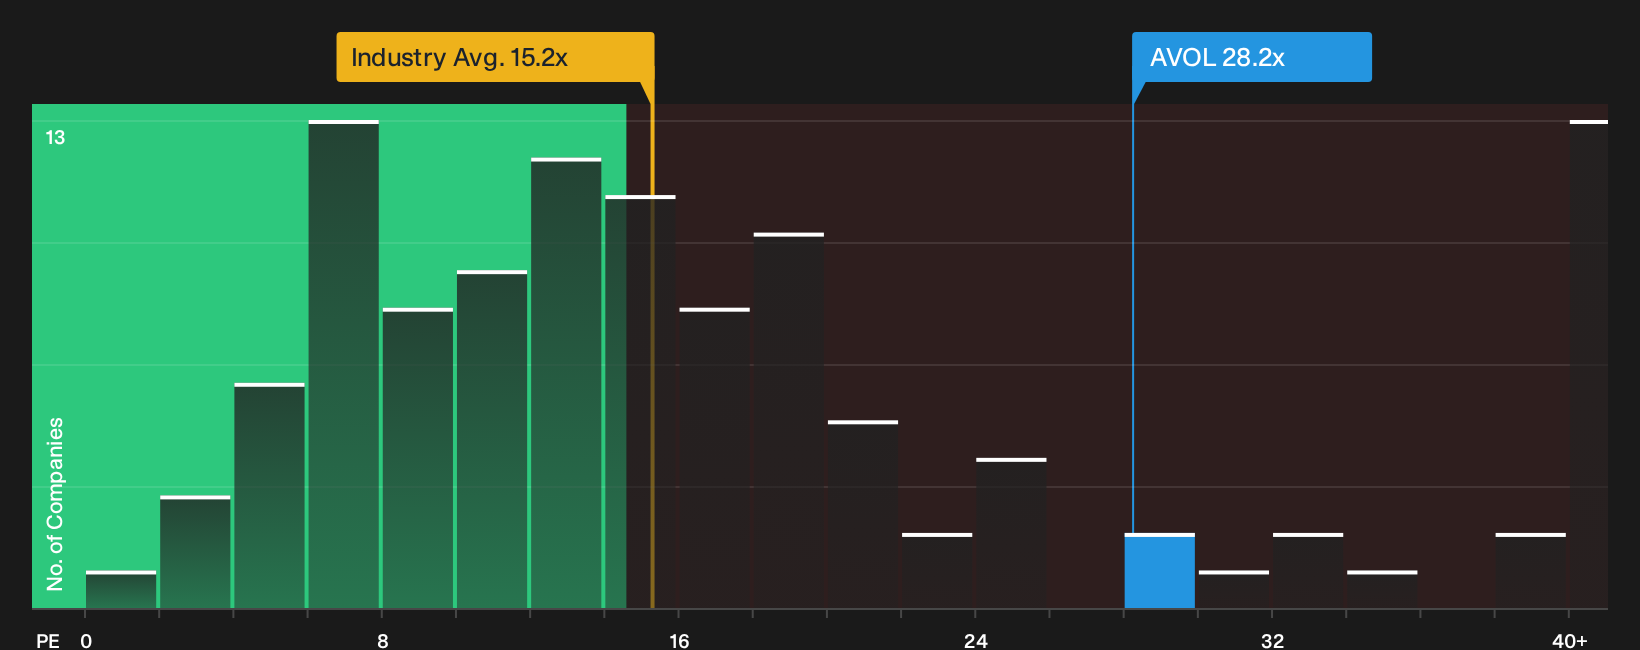
Analysts frame Avolta as 18% undervalued versus an estimated fair value of CHF51.94, yet the market is already paying a rich P/E of 28.2x compared with about 15x for European Specialty Retail peers and 15.2x for its direct comparison group.
That premium suggests investors are already paying up for execution and future earnings quality, which reduces the margin for error if the airport contract pipeline or profit forecasts disappoint.
It raises a simple question for anyone looking at the stock today: Is this a quality premium that still leaves upside on the table, or a valuation that now gives you less protection if the story stumbles?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Avolta so far. If you want to move quickly rather than follow the crowd, weigh both sides of the story with the 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Avolta?
Do not stop with Avolta. Broaden your watchlist with a few focused stock ideas that match different risk profiles and income goals using the Simply Wall Street Screener.
- Target resilient income by reviewing companies that aim to offer strong regular payouts through the 160 dividend fortresses.
- Spot resilient balance sheets and steady fundamentals before the crowd by checking the list of solid balance sheet and fundamentals (201 results).
- Hunt for under the radar opportunities with strong financial profiles inside the 619 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com