


- Atlanticus Holdings recently reported solid quarterly results that supported its consumer credit and auto finance operations, even as earnings per share remained broadly flat over roughly four years.
- The lender’s high net-debt-to-EBITDA ratio of 27.7x now sits beside a forward P/E of 8.2x. This puts the trade off between balance sheet risk and current earnings valuation squarely in focus for investors tracking the business model.
- We will look at how Atlanticus Holdings' solid results but elevated leverage reshape its investment narrative for long term holders today.
Atlanticus Holdings Investment Narrative Recap
To own Atlanticus Holdings, you need to be comfortable with a lender leaning into near prime and underserved borrowers while carrying very high leverage. The key underpinning is that the enlarged CaaS and auto finance platform can keep generating solid interest income and fees, even though EPS has stayed broadly flat for about four years.
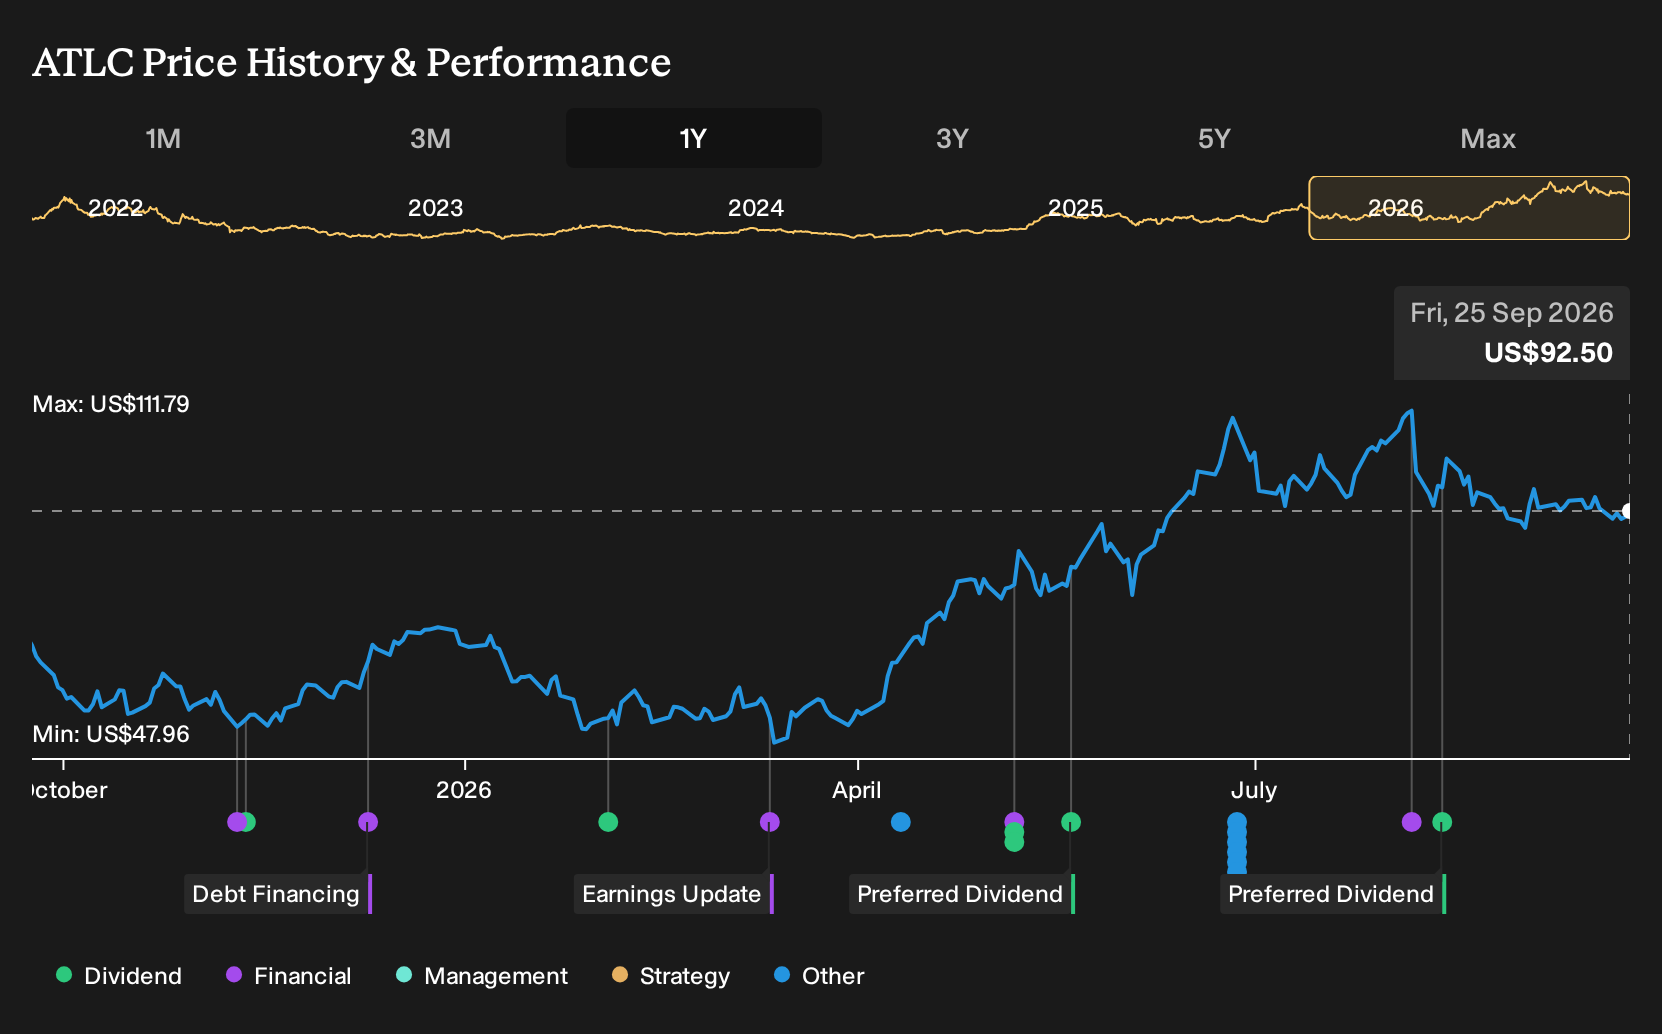
The recent price jump on solid results reinforces that the near term story is mostly about execution on existing receivables rather than unexpected new growth. The main catalyst is whether integration and servicing efficiencies appear in cleaner credit performance and lower costs. The largest risk remains the elevated net debt position combined with any deterioration in customer payment behavior.
The most relevant recent development is the strong quarterly report that helped push Atlanticus Holdings up about 62.4% over six months. That update confirmed ongoing support from its CaaS and auto finance segments and kept the forward P/E at 8.2x in focus against a balance sheet carrying net debt of 27.7x EBITDA.
For you as a shareholder, that mix sets up a straightforward tension. Solid operating momentum and high forecast revenue and earnings growth need to coexist with heavy reliance on external funding and debt that is not well covered by operating cash flow. Execution on credit quality, funding access and integration of acquired portfolios remains central to how this catalyst develops.
Atlanticus Holdings' narrative projects US$5.5b revenue and US$451.9m earnings by 2029. That path assumes revenue growth of 96.2% a year and an earnings increase of about US$307.1m from US$144.8m today.
Uncover why Atlanticus Holdings' fair value indicates a 44% potential upside to its current price. This gap could narrow quickly if sentiment improves.
Exploring Other Perspectives
One alternate view on Atlanticus Holdings focuses on the risk that the long Mercury integration could weigh on results. The most cautious analysts were still estimating about US$5.2b of revenue and US$490.5m of earnings by 2029, yet only assigning a US$110 price target. That is a much more skeptical outlook. Use this latest earnings surprise as a prompt to compare those prior assumptions with your own and consider how opinions might change from here.
Explore 4 other Atlanticus Holdings fair value estimates, including one that suggests as much as 7% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Atlanticus Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Atlanticus Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Atlanticus Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Atlanticus Holdings?
Once you have a view on Atlanticus Holdings, it often helps to compare it with other businesses that fit different risk and return profiles. The Simply Wall St Screener can surface stocks that match what you want in areas like quality, balance sheet strength, and income potential.
- If capital preservation sits high on your list, start with a group of companies that score well on stability by reviewing 30 resilient stocks with low risk scores.
- For investors who want quality at a reasonable price, scan a focused set of opportunities that pair stronger balance sheets with appealing valuations using the 32 high quality undervalued stocks.
- Income focused portfolios can benefit from consistent payers, so filter for businesses with higher yields and sturdier payouts through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com