


- Danieli & C. Officine Meccaniche recently presented at the 15th China International Steel Congress in Shanghai and hosted Italian diplomatic outreach at its new green-technology focused headquarters in the UK, highlighting its engineering capabilities in low emission steel production.
- The combination of Shanghai conference exposure and the Sheffield hub’s zero emission laboratories places Danieli & C. Officine Meccaniche directly in front of global steelmakers that are under pressure to decarbonise heavy industry.
- We will now look at how Danieli & C. Officine Meccaniche’s growing green steel footprint could influence the broader investment narrative around the group.
Scan Danieli & C. Officine Meccaniche’s push into low emission steel against a curated group of peers shaping cleaner heavy industry through our 19 nuclear energy infrastructure stocks.
What Is Danieli & C. Officine Meccaniche's Investment Narrative?
To own Danieli & C. Officine Meccaniche, you have to believe that heavy industry will keep paying for complex plant making and cleaner steel solutions, even as projects are large, slow and capital intensive. The recent Shanghai congress slot and the Sheffield zero emission hub keep the group in the room when big producers scope future capex. That helps the demand pipeline story, although it does not alter the near term reality that execution quality, delivery timing and pricing discipline drive returns on a €3.6b business.
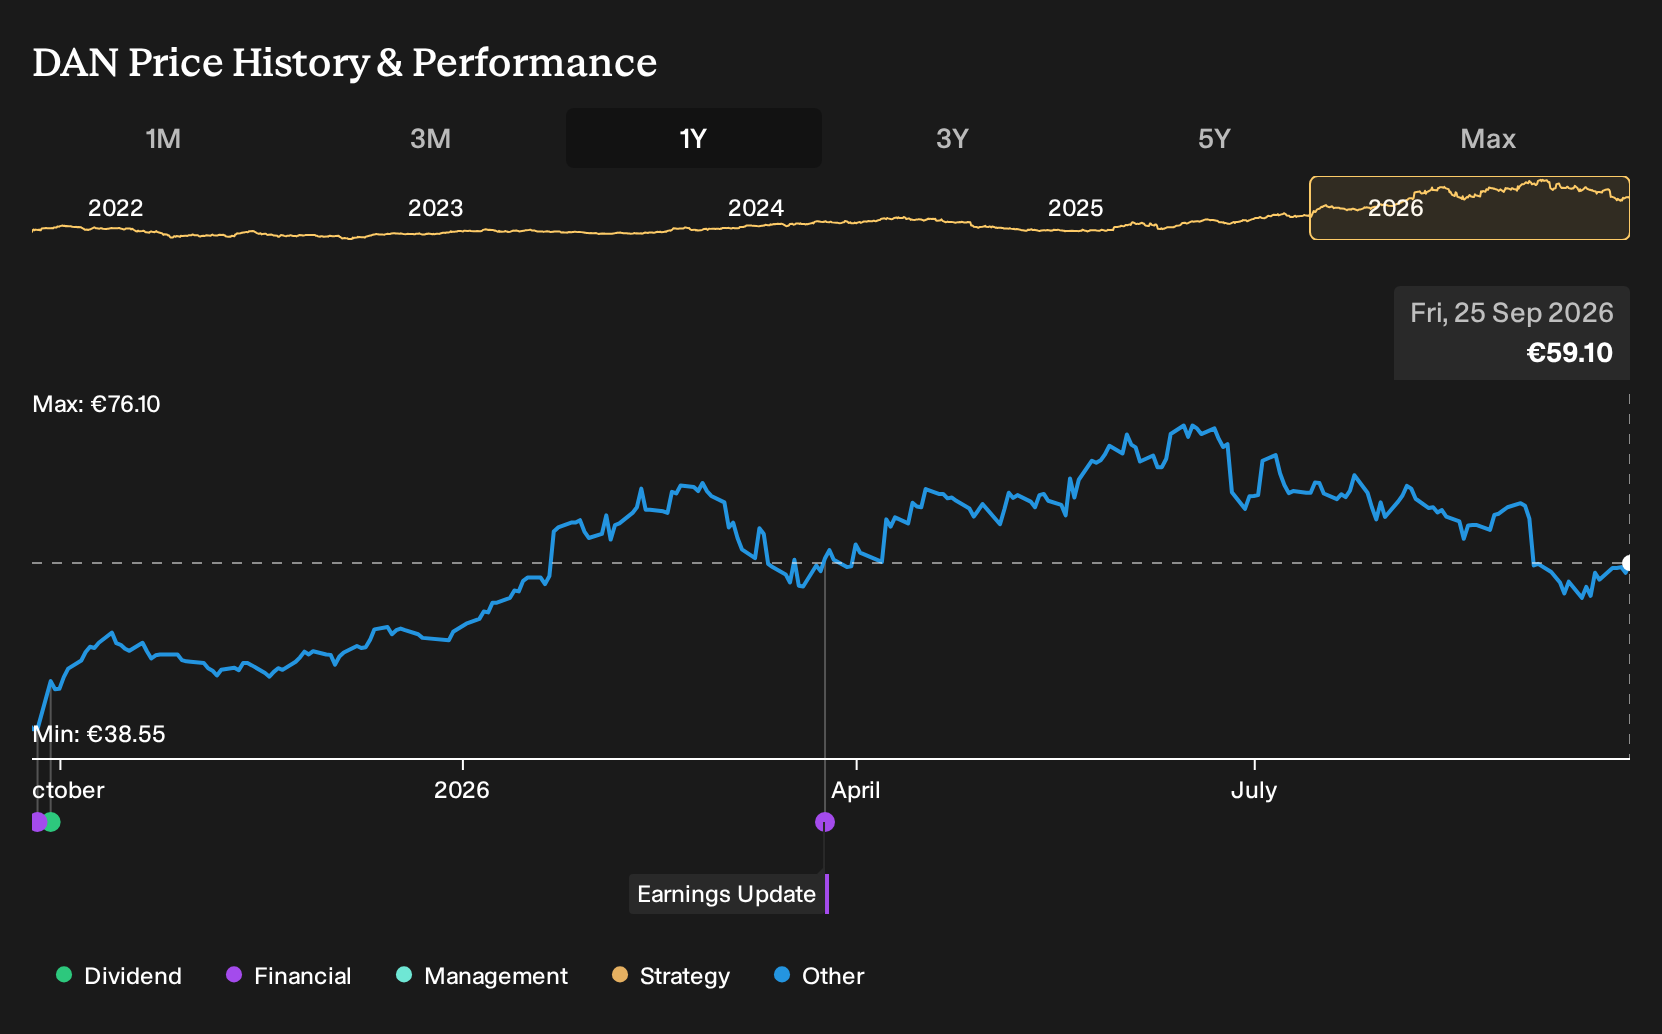
Right now, the share price is up over the past year but has retreated about 10% over the last month. Analysts still see upside and call Danieli & C. Officine Meccaniche good value on a P/E of 18.7x versus their fair multiple of 21.1x. The UK and China visibility supports the medium term order book narrative. The harder part is turning a 5.7% net margin and relatively low 7.9% ROE into consistently better economics in a sector that relies heavily on external funding.
That said, one thing could still undermine that whole green steel pitch if...
There's only one way to know the right time to buy, sell or hold Danieli & C. Officine Meccaniche. Head to Simply Wall St's company report for the latest analysis of Danieli & C. Officine Meccaniche's Fair Value.
Exploring Other Perspectives
The three fair value views from the Simply Wall St Community cluster between €63.5 and €77, so you are already seeing a wide spread from a small group of retail modellers. When you set that against Danieli & C. Officine Meccaniche’s fresh visibility in Shanghai and Sheffield, the gap in expectations could widen. Explore those different takes.
Explore 2 other Danieli & C. Officine Meccaniche fair value estimates, including one that suggests as much as 30% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Danieli & C. Officine Meccaniche research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Danieli & C. Officine Meccaniche. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Danieli & C. Officine Meccaniche's overall financial health at a glance.
Looking For More Investment Ideas Beyond Danieli & C. Officine Meccaniche?
Once you have a view on Danieli & C. Officine Meccaniche, it can help to widen the lens and see how other businesses stack up on income, value and balance sheet strength using the Simply Wall St Screener.
- If reliable income is high on your list, check out a hand picked set of higher yield opportunities through 159 dividend fortresses.
- For investors who care most about quality at a sensible valuation, scan a focused group of candidates flagged as potentially mispriced using the 185 high quality undervalued stocks.
- If resilience matters more than excitement, review companies that score well on financial robustness through the 226 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com