


BridgeBio Pharma (BBIO) is back in focus after publishing the first peer reviewed, real world comparative study of transthyretin stabilizers in Cardiology and Therapy. The study highlights acoramidis outcomes versus rival therapy tafamidis for ATTR cardiomyopathy.
BridgeBio Pharma’s latest acoramidis data landed against a softer tape, with the share price down 14.4% over the past 30 days and 16.2% year to date, even as the 1 year total shareholder return of 31.0% and 3 year total shareholder return of about 1.5x highlight strong longer term momentum that recent weakness has tempered rather than erased.
Spot opportunities around BridgeBio Pharma’s ATTR-CM catalyst by scanning a curated set of resilient healthcare and biotech stocks with 30 resilient stocks with low risk scores.BridgeBio Pharma now trades well below both its average analyst target and an intrinsic value estimate after a sharp pullback. The real question is where fair value sits within that gap.
Most Popular Narrative: 162.3% Overvalued
BridgeBio Pharma closed at $65.57, while the most followed narrative on the stock, according to AnimalDoctorKwon, pins fair value at $25. The gap frames acoramidis and the broader ATTR-CM franchise as a test of whether current expectations are overreaching.
The "BridgeBio Commercial Bonanza" is priced for perfection, treating the upcoming Acoramidis launch as an automatic cash cow while ignoring a brutal multi-front commercial dogfight.
Here is why the market is mispricing the structural hurdles for BBIO:
1. The Pfizer Moat & SG&A Bleed: Outperforming Vyndaqel in a clinical trial does not guarantee market share. Pfizer’s commercial entrenchment in the ATTR-CM space is institutional. For BBIO to compete, marketing and launch expenses will likely need to rise significantly, which could severely depress free cash flow and delay true profitability relative to current expectations.
2. The Silencer Paradigm Shift: The real threat is not Pfizer; it is Alnylam. With Amvuttra’s recent HELIOS-B Phase 3 data, the ATTR-CM landscape appears to be shifting from TTR stabilizers to TTR silencers. BBIO is launching a stabilizer into a market that some investors view as moving toward gene-silencing approaches.
3. Incumbent Monopolies in Rare Disease: Infigratinib for achondroplasia looks promising, but BioMarin’s Voxzogo already has an established position and clinical loyalty. Entering a rare disease market as a later entrant can require substantial capital, with potentially diminishing returns on early market penetration.
BBIO’s hub-and-spoke model mitigated some early-stage risk, but it does not eliminate the capital requirements of independent commercial execution. At these levels, some investors see the margin of safety against Alnylam and Pfizer as thin.
See why 4 investors see BridgeBio Pharma as 162% overvalued.
Result: Fair Value of $25 (OVERVALUED)
Still, BridgeBio Pharma could upend this bearish script if the launch economics of acoramidis prove more efficient than feared or if late stage programs secure stronger pricing power.
Find out about the key risks to this BridgeBio Pharma narrative.
Another View on BridgeBio Pharma’s Value
The user narrative tags BridgeBio Pharma as overvalued at $25 per share. Our DCF model lands in a very different place, with a future cash flow value estimate of $281.61 and the current $65.57 price at a 76.7% discount. Which lens do you trust when views are this far apart?
Look into how the SWS DCF model arrives at its fair value.
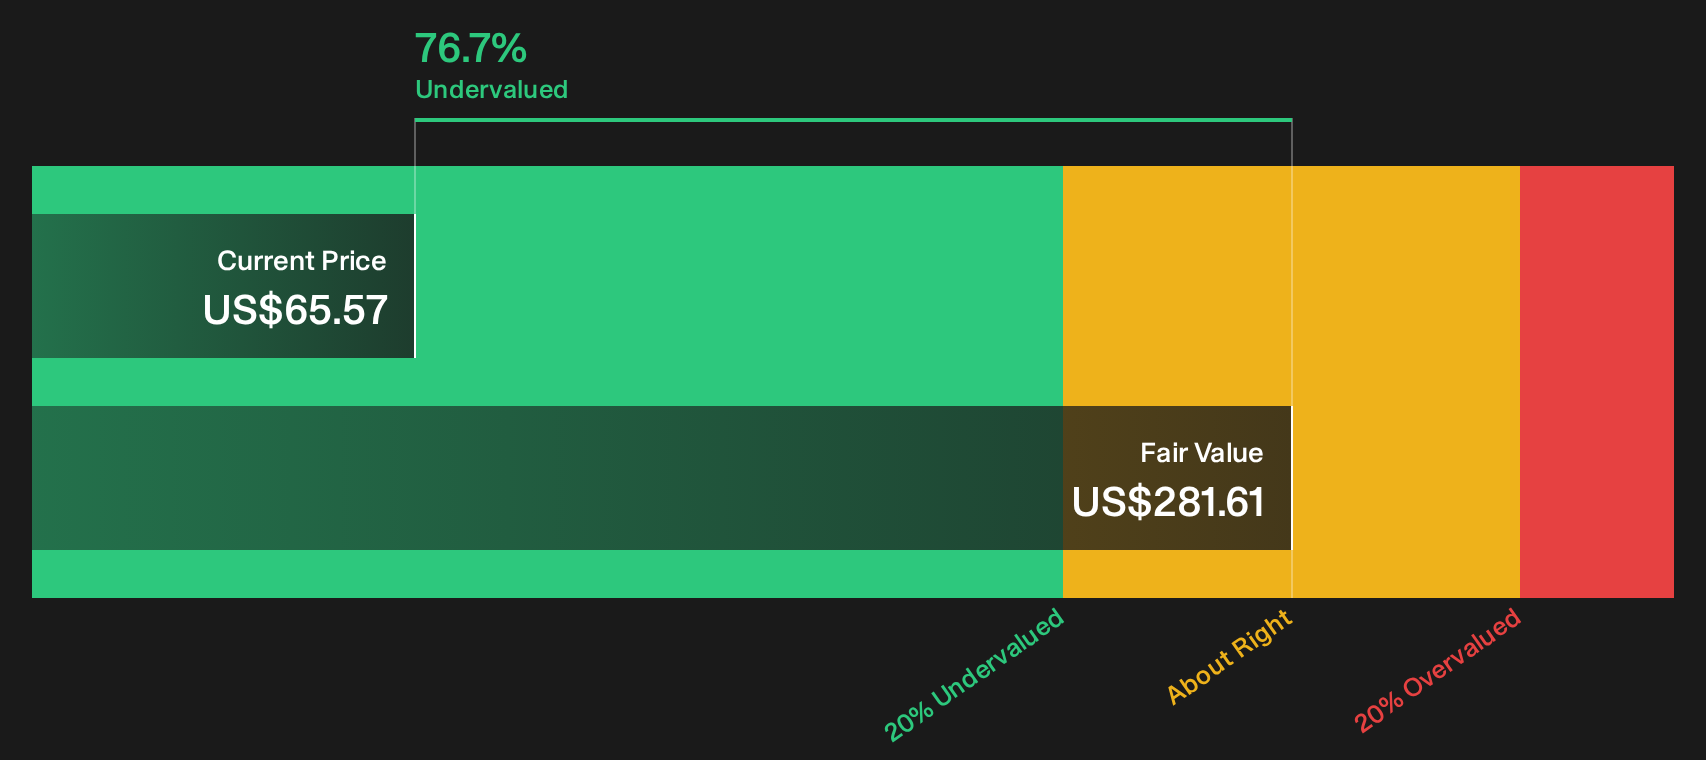
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BridgeBio Pharma for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around BridgeBio Pharma’s value can pull you in different directions, so move quickly. Review the underlying data and weigh both sides of the story with 3 key rewards and 1 important warning sign.
Hunting for more ideas beyond BridgeBio Pharma?
If BridgeBio Pharma has your attention, do not stop there. Broader context across sectors and styles can sharpen your next move and help you spot mispriced stories early.
- Target resilience by scanning a list of solid balance sheet and fundamentals (24 results) that can better handle shocks and funding stress.
- Chase value by checking a 16 high quality undiscovered gems that the wider market might not be watching yet.
- Build income by reviewing a 8 dividend fortresses that could support more predictable cash returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com