


Hub Group (HUBG) is back in the spotlight after receiving a Nasdaq staff delisting determination tied to delayed SEC filings. This move now sits alongside fresh leadership changes and updated 2026 revenue guidance.
Investors have reacted sharply to the Nasdaq notice and accounting overhang, with Hub Group’s share price down 23.4% over the past month and 31% over 90 days, while the 1 year total shareholder return has declined 11.3%. This points to fading momentum as governance and reporting risks move to the foreground.
Compare Hub Group’s regulatory setback and reset in leadership with a curated group of resilient transport and logistics businesses using the list of solid balance sheet and fundamentals (24 results) as a starting point for ideas.
After a one month fall of 23.4% and a 32% gap to the average analyst target, Hub Group now trades in a wide band of opinions. Where does a reasonable estimate of fair value actually land relative to that spread?
Most Popular Narrative: 28% Undervalued
Hub Group closed at $30.34, while the most followed valuation storyline pegs fair value at $42.20, creating a sizable gap that rests on specific growth and margin assumptions rather than sentiment alone.
The company's strategy of targeted, accretive acquisitions (for example, Marten Transport's refrigerated intermodal business), along with a strong balance sheet and cash flow generation, provides catalysts for both inorganic top-line growth and earnings acceleration, as Hub Group leverages synergies, broadens its service offering, and scales differentiated solutions across its national footprint.
See why 2 investors see Hub Group as 28% undervalued.
Result: Fair Value of $42.20 (UNDERVALUED)
Still, the accounting restatements and ongoing securities law investigations around Hub Group create real uncertainty, and leadership turnover adds another layer of execution risk for this story.
Find out about the key risks to this Hub Group narrative.
Another View: Hub Group Through The P/E Lens
There is a clear split in how Hub Group is priced. On one side, our cash flow work points to value support. On the other, the earnings multiple paints a tougher picture.
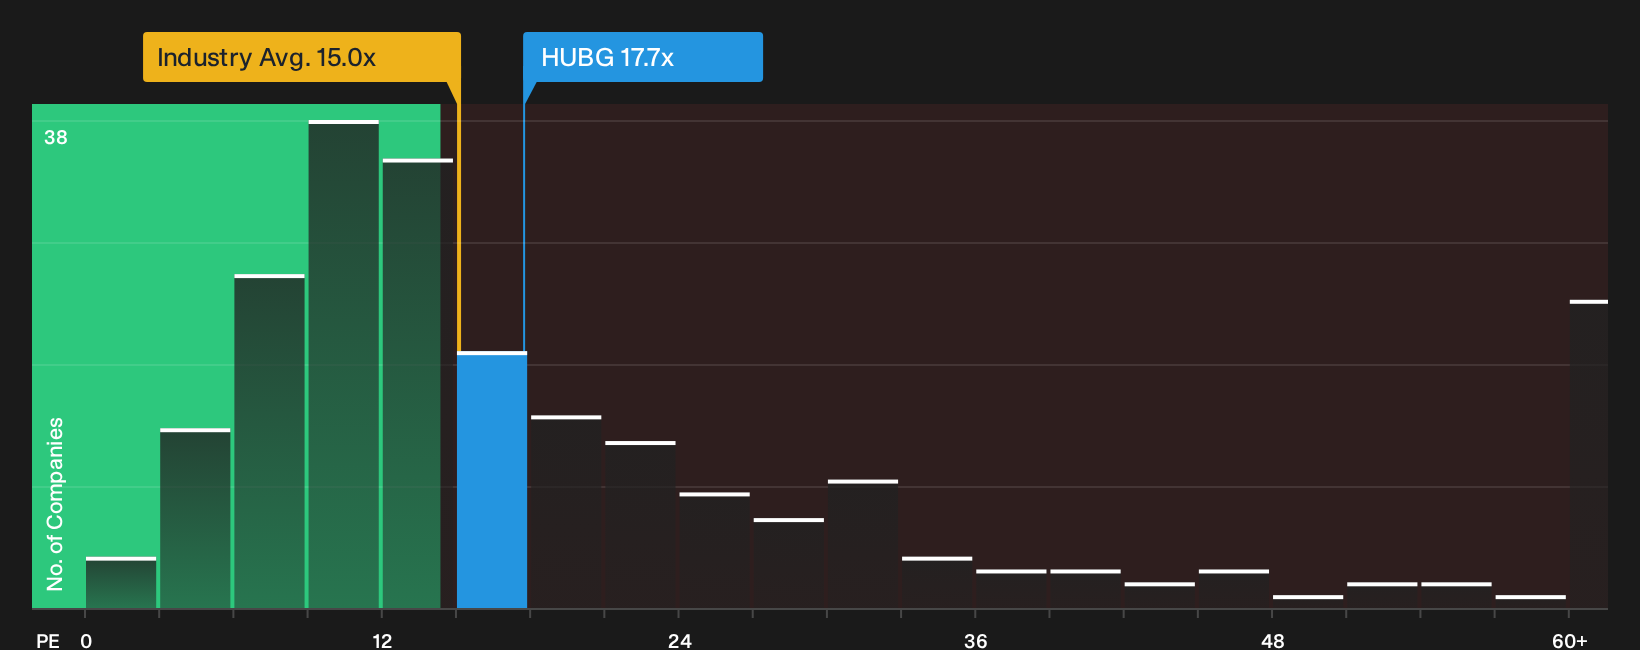
The stock trades on a P/E of 17.7x. That is above the global logistics group at 15x, and above the fair ratio of 13.2x that the regression work suggests the market could gravitate toward. In practice, that means Hub Group carries valuation risk if sentiment cools, even though it screens cheaper than its direct peer set at 24.4x.
For investors who prefer earnings based yardsticks over cash flow models, this second view raises a simple question: Is the current premium to the industry worth paying while the market debates Hub Group’s accounting clean up and profit trajectory.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Hub Group does not need to dictate your view. Act while the facts are fresh and stress test the positives for yourself with the 2 key rewards
Looking for more investment ideas beyond Hub Group?
If Hub Group has you rethinking your watchlist, use this moment to line up fresh ideas that match your risk tolerance and income goals.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (24 results) that filters for financially grounded businesses.
- Hunt for potential value opportunities by running through a 32 high quality undervalued stocks that highlights companies with quality metrics and compressed valuations.
- Build a cash flow focused watchlist by checking a 8 dividend fortresses that surfaces higher yielding payouts backed by underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com