


The European markets have recently experienced a tug-of-war between optimism surrounding AI advancements and concerns over potential monetary tightening due to high energy prices and resilient economic data. As investors navigate this complex landscape, growth companies with high insider ownership often stand out for their potential alignment of management interests with shareholder value, making them an intriguing focus in today's market environment.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| Kuros Biosciences (SWX:KURN) | 25.9% | 60.3% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 20.5% | 41.1% |
| CD Projekt Red (WSE:CDR) | 35.2% | 53.9% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.2% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 30% |
Let's take a closer look at a couple of our picks from the screened companies.
MilDef Group (OM:MILDEF)
Simply Wall St Growth Rating: ★★★★★★
Overview: MilDef Group AB (publ) develops, manufactures, and sells rugged IT solutions across several countries including Sweden, the United Kingdom, and the United States, with a market cap of SEK11.72 billion.
Operations: The company generates revenue of SEK2.66 billion from its Computer Hardware segment.
Insider Ownership: 10.3%
Earnings Growth Forecast: 32.5% p.a.
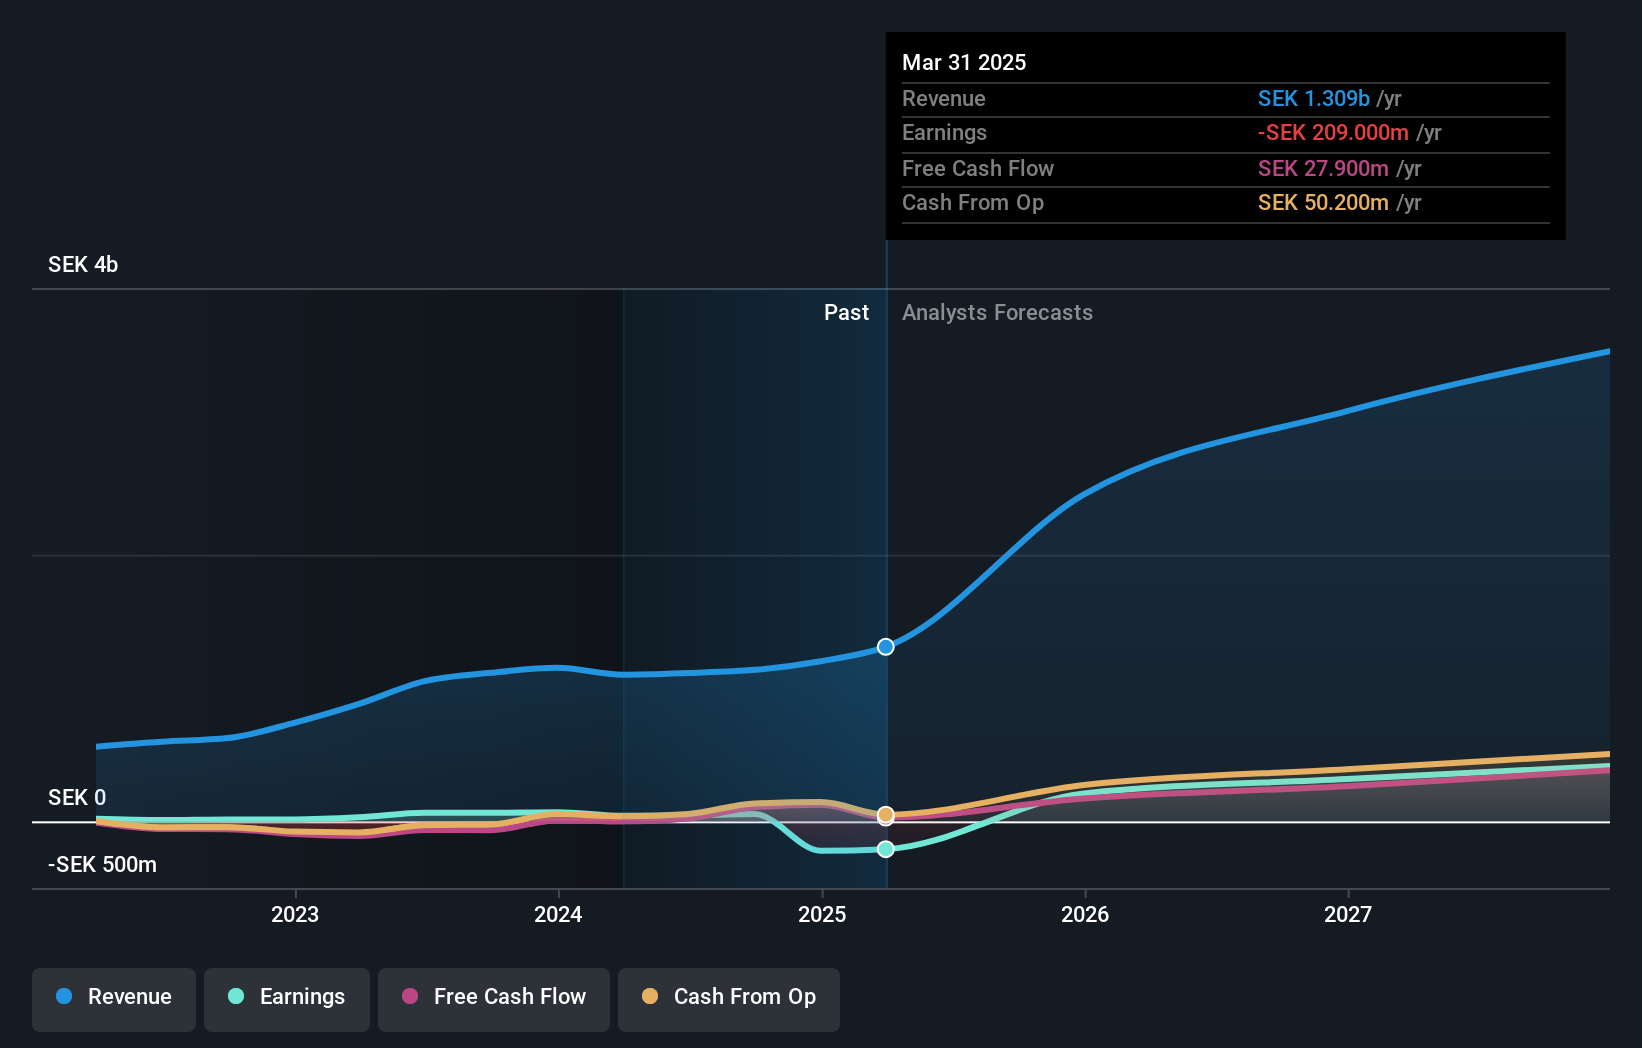
MilDef Group is experiencing robust growth, with revenue forecasted to increase 21.2% annually, outpacing the Swedish market. Despite recent insider buying not being substantial, the company trades significantly below its estimated fair value and became profitable this year. Recent expansions in Rosersberg and a major NATO hardware contract highlight strategic positioning in defense markets. Earnings are expected to grow significantly at 32.5% annually, supported by increased defense spending and a strong order book.
- Click here and access our complete growth analysis report to understand the dynamics of MilDef Group.
- Our comprehensive valuation report raises the possibility that MilDef Group is priced lower than what may be justified by its financials.
Rejlers (OM:REJL B)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Rejlers AB (publ) is an engineering consultancy firm operating in Sweden, Finland, Norway, and Abu Dhabi with a market cap of SEK3.21 billion.
Operations: The company's revenue is derived from its engineering consultancy services, with SEK3.09 billion from Sweden, SEK1.46 billion from Finland, and SEK404.70 million from Norway (including Embriq).
Insider Ownership: 17.6%
Earnings Growth Forecast: 24.9% p.a.
Rejlers is poised for substantial earnings growth, with forecasts suggesting a 24.93% annual increase, outpacing the Swedish market's 7.3%. Despite trading at a significant discount to its estimated fair value, recent financial results show some challenges, including lower net income compared to last year. Insider activity has seen more buying than selling in the past three months. Recent agreements in Sweden and Finland bolster its engineering and infrastructure services portfolio.
- Navigate through the intricacies of Rejlers with our comprehensive analyst estimates report here.
- Insights from our recent valuation report point to the potential undervaluation of Rejlers shares in the market.

Yubico (OM:YUBICO)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Yubico AB offers authentication solutions for computers, networks, and online services and has a market cap of SEK9.13 billion.
Operations: The company generates revenue of SEK2.12 billion from its Security Software & Services segment.
Insider Ownership: 22.9%
Earnings Growth Forecast: 33% p.a.
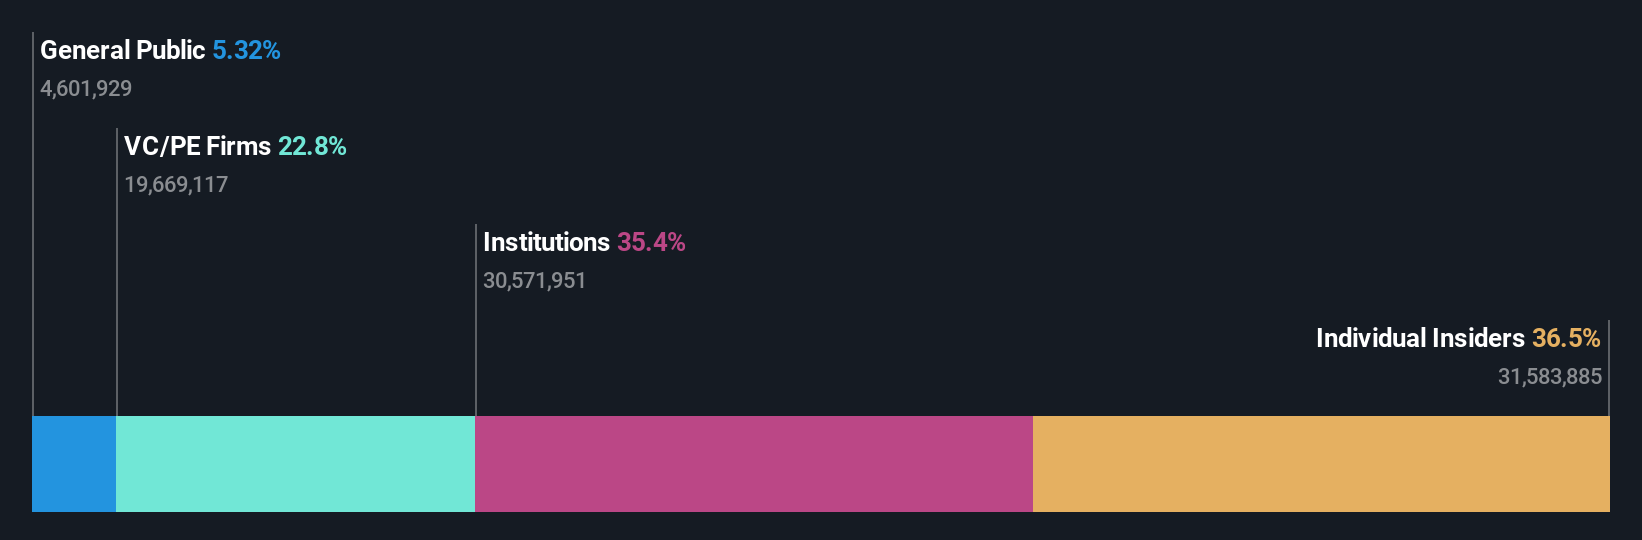
Yubico's earnings are projected to grow significantly at 33% annually, surpassing the Swedish market's growth. Despite a volatile share price and declining profit margins from 10.9% to 7.1%, recent earnings show improvement with net income rising sharply in Q2 2026. The launch of YubiKey 5.8 enhances its product offerings, supporting digital identity and security innovations, while its membership in the European Cyber Security Organisation underscores its commitment to advancing cybersecurity standards across Europe.
- Unlock comprehensive insights into our analysis of Yubico stock in this growth report.
- In light of our recent valuation report, it seems possible that Yubico is trading beyond its estimated value.
Key Takeaways
- Explore the 213 names from our Fast Growing European Companies With High Insider Ownership screener here.
- Interested In Other Possibilities? AI is about to change healthcare. These 135 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com