


Yakult HonshaLtd (TSE:2267) has drawn fresh attention after its recent share performance, with the stock roughly flat over the past month but showing a 2.2% gain in the past 3 months.
For context, Yakult HonshaLtd now trades at ¥2,809.5, with a 14.53% year to date share price return and a 16.81% total shareholder return over the past year. The 3 year total shareholder return is down 18.11% and the 5 year figure sits at 7.93%, which indicates that recent momentum has been stronger following a weaker period for longer term holders.
Scan how Yakult HonshaLtd compares with other consumer-focused businesses showing recent price momentum and solid fundamentals using our curated list of 74 high quality undiscovered gems.
Yakult HonshaLtd shares have climbed this year, yet the stock still trades above both analyst targets and some intrinsic value estimates. Is that gap a sign of overreach or a premium investors are prepared to keep paying?
Most Popular Narrative: 15% Undervalued
On the most followed narrative, Yakult HonshaLtd screens as undervalued, with a fair value estimate of ¥3,318.84 against a last close of ¥2,809.5. This sets up a fairly punchy gap for a stock already trading above some other intrinsic value estimates.
Analyst consensus already expects international growth, but the robust double-digit volume increases in key high-potential markets like Vietnam indicate broader, more sustainable demand acceleration than currently priced in, setting the stage for outsized, compounding topline growth as Yakult's addressable market expands rapidly.
See why 0 investors see Yakult HonshaLtd as 15% undervalued.
That storyline rests on a discount rate of 4.91%, combined with assumptions that Yakult HonshaLtd can gradually lift revenue to ¥559.4b by around 2029 while accepting slimmer profit margins and a higher future P/E multiple of 24.2x than the current industry reference of 15.9x.
Supporters of this view also lean on capital allocation, with planned buybacks and treasury stock disposal expected to reduce the share count and potentially amplify earnings per share even if total profit does not rise meaningfully from the current ¥44.2b level.
Against that, the same narrative flags pressure points such as weaker dairy volumes in Japan, rising input costs and foreign exchange swings. These could all work against those bullish revenue and margin assumptions if conditions move against Yakult HonshaLtd.
Result: Fair Value of ¥3,318.84 (UNDERVALUED)
Still, if dairy volumes in Japan keep weakening and input costs stay elevated, the bullish Yakult Honsha Ltd scenario could quickly look too optimistic.
Find out about the key risks to this Yakult HonshaLtd narrative.
Another View: Yakult HonshaLtd On Earnings Multiples
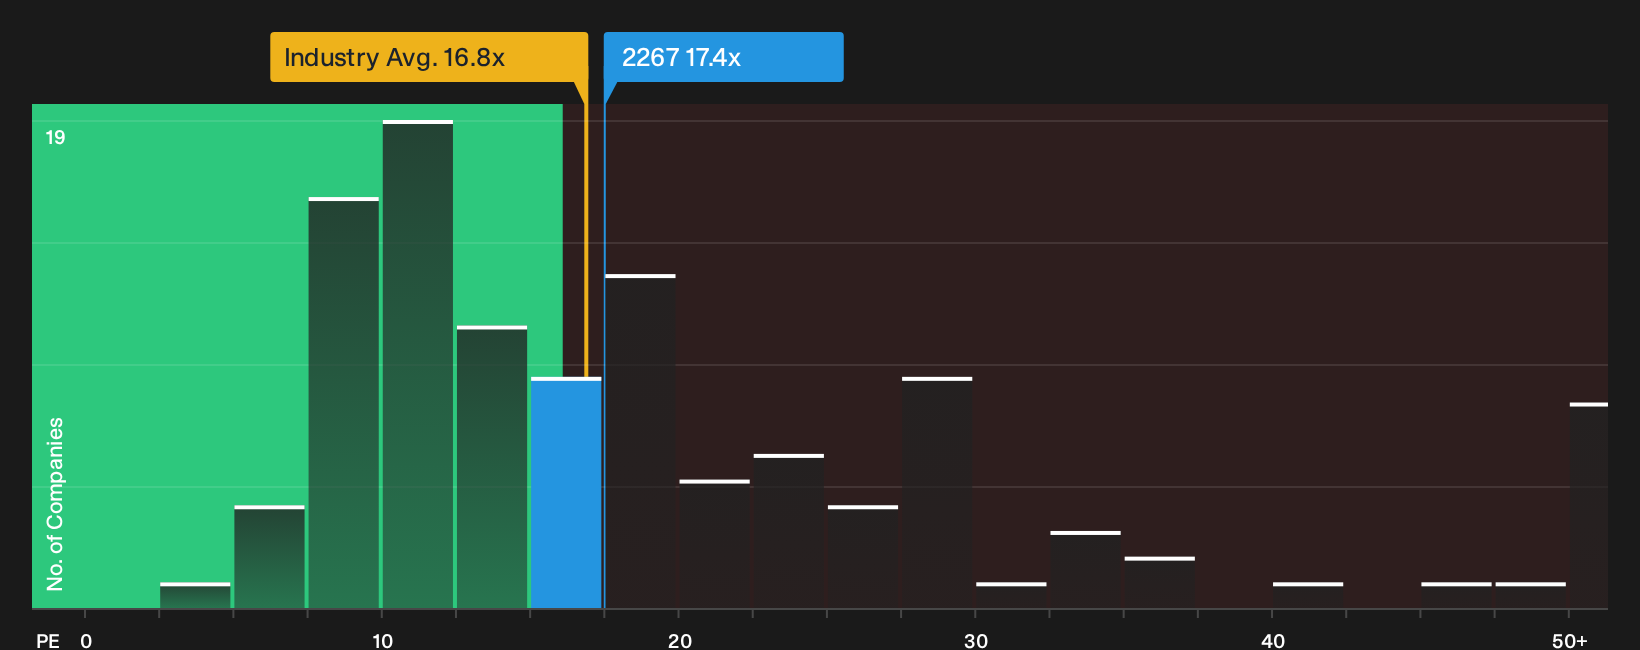
While the popular story frames Yakult HonshaLtd as 15% undervalued on a fair value of ¥3,318.84, the current P/E of 17.4x tells a cooler story. It sits above the JP Food industry at 16.8x, the peer average at 16.6x, and even the fair ratio of 17.2x. This suggests there may be less of a safety cushion than the bullish narrative implies. Investors may wish to consider whether this valuation gap is acceptable or whether it warrants a more cautious view of the upside case.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Yakult HonshaLtd's valuation and prospects can be hard to weigh, so check the data yourself and move fast to frame your own stance. To see both the upside arguments and the downside flags side by side, start with 1 key reward and 3 important warning signs.
Looking for more Yakult HonshaLtd investment ideas?
If Yakult HonshaLtd has your attention, do not stop here. Broaden your watchlist with fresh ideas that fit your risk, income and quality preferences.
- Target potential mispricings by scanning a curated set of 19 high quality undervalued stocks that pair stronger balance sheets with attractive valuations.
- Build an income focused watchlist by reviewing a hand picked group of 14 dividend fortresses that may suit investors who prioritise yield.
- Prioritise resilience by checking a curated 21 resilient stocks with low risk scores that filters for businesses with steadier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com