


Innodata (INOD) just added retired Admiral Michael S. Rogers, former Director of the NSA and Commander of U.S. Cyber Command, to its board, sharpening the focus on AI safety and federal opportunities.
The appointment comes after a volatile period for Innodata, with the share price falling 3.7% on the day to US$69.21, but posting a 7-day share price return of 13.4% and a 30-day share price return of 22.3%. The 3-year total shareholder return is roughly 7x and the 5-year total shareholder return is a little over 6x, signaling long-term momentum even though the 1-year total shareholder return is down 8.9%.
Scan other AI and data engineering plays that are building similar momentum with our hand picked 85 AI infrastructure stocks.
Innodata has moved sharply in both directions, with strong multi year returns sitting alongside a recent pullback. Does the current setup still leave enough upside potential to compensate for the obvious volatility risk as valuation comes into focus?
Most Popular Narrative: 44% Undervalued
The most followed Innodata narrative suggests a fair value of $122.75 per share, well above the last close at $69.21. This frames the board move and recent volatility against a valuation story that still leans optimistic despite clear execution and concentration risks.
Increasing adoption of AI across industries requires curated and high-quality datasets. Innodata's evolving role from simple data provider to strategic partner (sitting "at the table" with clients' data scientists) is likely to support premium pricing, recurring contracts, and market share gains, with potential impact on both revenue stability and net margins.
See why 84 investors see Innodata as 44% undervalued.
Result: Fair Value of $122.75 (UNDERVALUED)
Still, Innodata’s reliance on a small group of large tech clients, along with rising spending on talent and infrastructure, could quickly pressure earnings if expected AI contracts slow.
Find out about the key risks to this Innodata narrative.
Another View: Innodata Looks Expensive On Earnings
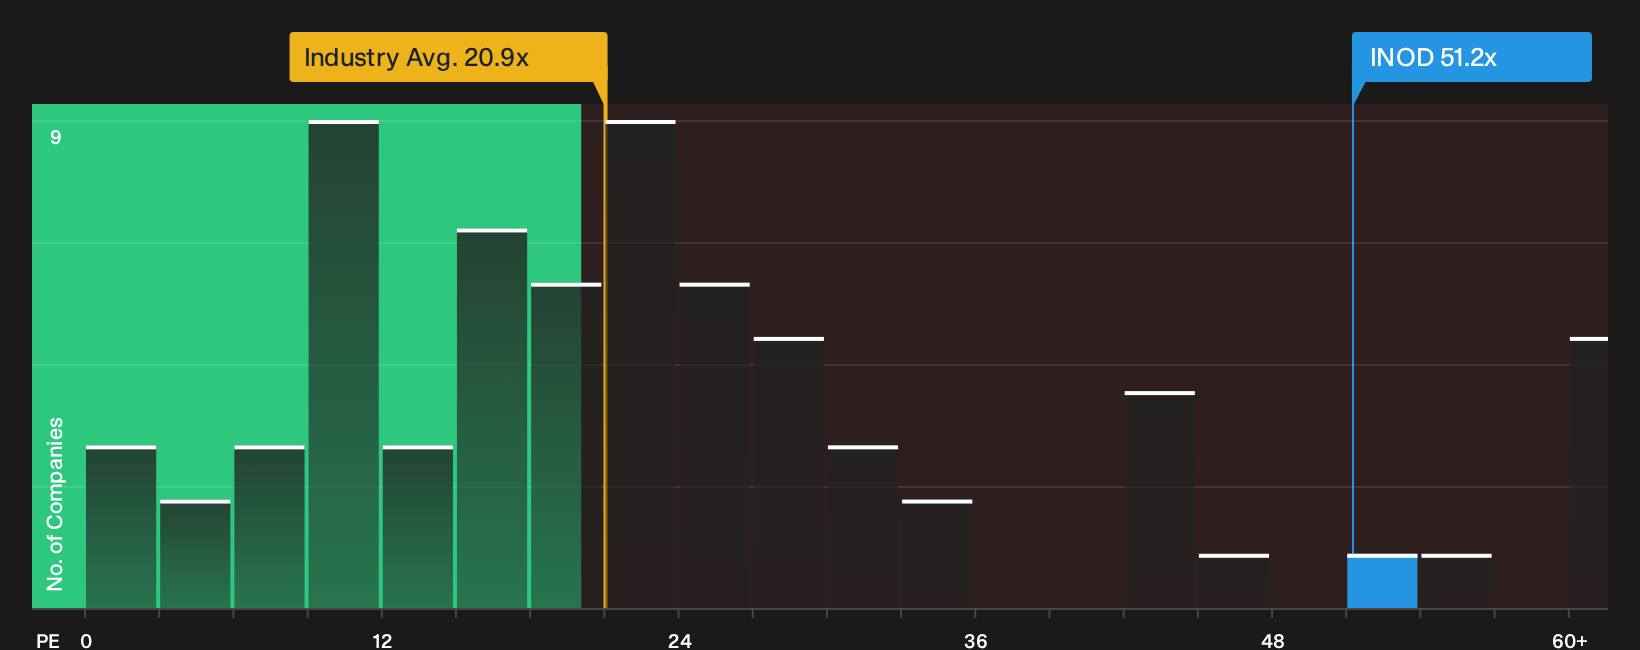
The first Innodata narrative leans on analyst targets and growth expectations to argue the stock is undervalued. A simpler check using the current P/E tells a different story. Innodata trades on 51.2x earnings, while direct peers sit at 23.6x and the wider US Professional Services group is at 20.9x.
The fair ratio for Innodata is 30.7x. That is still higher than the industry, but well below where the stock currently changes hands. For investors, that gap points to valuation risk if sentiment cools or earnings do not build as quickly as forecast. Which yardstick do you trust more for your own hurdle rate?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed messaging around Innodata has you torn, use that tension as a prompt to move quickly, pull up the numbers, and test the narrative against your own hurdle rates by checking the 3 key rewards.
Looking for more Innodata sized opportunities?
If Innodata has sharpened your focus on pricing power, risk, and long term compounding, do not stop here. Put that momentum to work with a few targeted screens today.
- Chase mispriced potential and scan a curated set of companies trading below their implied worth through the 32 high quality undervalued stocks.
- Strengthen your downside protection by filtering for businesses with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for early stage prospects with quality foundations before the crowd spots them by checking the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com