


CME Group (CME) just expanded its derivatives menu with S&P UBS USD Liquid Leveraged Loan Index futures, while weekend gold and silver contracts logged strong activity, drawing fresh attention to the stock.
Recent price action has been choppy for CME Group, with the share price down 7.46% over the past month and 4.01% over the last week, even after a 19.77% 90-day share price return and a 5-year total shareholder return of 67.58% that points to longer term momentum. These new leveraged loan futures and the strong uptake in 24/7 precious metals trading arrive as the share price cools in the short term. This can reflect investors reassessing near term expectations even while a 3-year total shareholder return of 50.16% suggests that the broader investment case has rewarded patient holders.
Spot 16 high quality undiscovered gems that, like CME Group’s new leveraged loan and 24/7 metals contracts, are expanding their product reach while price momentum cools in the short term.CME Group appears to be a powerful franchise on the product side while the share price has eased off recent highs. The key question now is whether that quality is already fully reflected in the valuation.
Most Popular Narrative: 7% Undervalued
CME Group last closed at $264.48, while the most followed narrative pegs fair value at $283.60. This frames the recent pullback as a move away from that reference point rather than a break in the story.
New product introductions, such as single stock futures, compute futures on NVIDIA H100 rental costs, E mini Equity Factor futures, wind power contracts, leveraged loan index futures and a planned entry into European dairy, together with ongoing technology driven efficiencies from cloud migration and tokenization projects, give CME Group more ways to grow transaction and market data revenue while supporting high net margins.
See why 51 investors see CME Group as 7% undervalued.
Result: Fair Value of $283.60 (UNDERVALUED)
Still, the CME Group story can be knocked off course if rivals chip away at key energy and rates contracts, or if sentiment turns on valuation after recent gains.
Find out about the key risks to this CME Group narrative.
Another View: CME Group Through A DCF Lens
The fair value narrative around CME Group leans on analyst targets, yet the SWS DCF model paints a different picture. At $264.48, the shares sit above an estimated future cash flow value of $248.59, which frames the stock as expensive on this cash based yardstick. That gap raises a simple question for you as an investor: Which set of assumptions feels more realistic?
For a closer look at how the cash flow work is done, and where the inputs could be challenged or adjusted to fit your own view, Look into how the SWS DCF model arrives at its fair value.
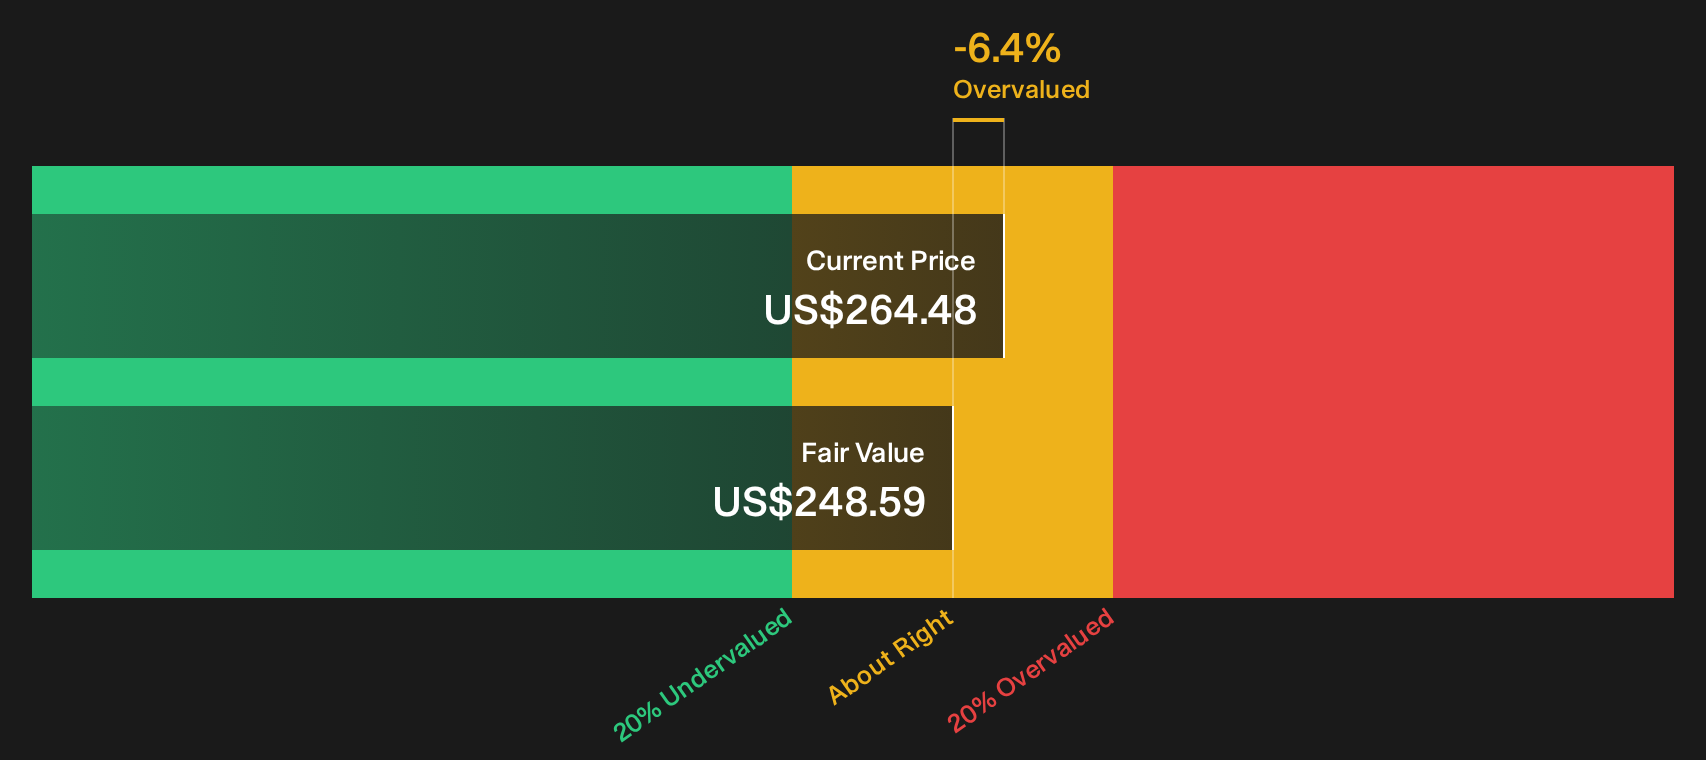
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CME Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on CME Group so far. If you want to move fast and ground your own view in hard numbers, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CME Group?
If CME Group has your attention, do not stop here. Broader context from other opportunities can sharpen your judgment and keep your watchlist ahead of the curve.
- Target resilient value opportunities by scanning companies that score well on quality and valuation using the 32 high quality undervalued stocks.
- Prioritize capital preservation by reviewing the 30 resilient stocks with low risk scores that combine sturdier fundamentals with gentler drawdown profiles.
- Hunt for future market leaders by checking the 16 high quality undiscovered gems before attention and pricing fully catch up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com