


- WuXi Biologics reported that its Wuxi Mashan drug substance and drug product facilities recently cleared a two week unannounced U.S. FDA GMP inspection covering multiple approved biologics, reinforcing its ability to support commercial supply to the U.S. market.
- The Wuxi Mashan site integrates drug substance and drug product manufacturing and has maintained a perfect record across hundreds of audits. This points to a deeply embedded quality system that matters for long term client confidence and operational resilience at WuXi Biologics.
- We will now assess how WuXi Biologics' successful unannounced FDA GMP inspection may influence the broader investment narrative around its business.
Compare WuXi Biologics' FDA-ready profile with other high quality, resilient operators by scanning our curated list of 226 resilient stocks with low risk scores that prioritise robust systems and audit track records.
WuXi Biologics (Cayman) Investment Narrative Recap
To own WuXi Biologics, you need to believe the global biologics outsourcing trend has room to run and that the group can keep converting its broad project base into late stage and commercial work. The unannounced FDA success at Wuxi Mashan supports that operational story, but it does not remove geopolitical exposure or client concentration in North America.
In the near term, the key swing factor is how quickly WuXi Biologics fills its expanding capacity in Ireland, the US, and Singapore with commercially relevant projects. The biggest risk remains a policy or regulatory setback that curbs US related revenue, which could matter more to the business than any single inspection outcome.
The recent FDA inspection result ties most directly to the long running push into higher complexity modalities like bispecifics and ADC related work, already a large share of the project mix. Consistent regulatory acceptance at a flagship site makes it easier for big pharma partners to place more late stage programs into WuXi Biologics' network.
For you as an investor, this matters because the main catalysts are still backlog conversion, utilization across the global footprint, and the scaling of IP linked revenue streams. The Mashan track record helps on the execution side, while the core risks of geopolitical pressure, pricing competition, and potential insourcing by major customers still need close watching.
WuXi Biologics (Cayman)'s current analyst narrative points to revenue of CN¥38.0b and earnings of CN¥9.1b by 2029. This implies forecast revenue growth of 17.2% a year and an earnings increase of CN¥4.1b from current earnings of CN¥5.0b.
Uncover why WuXi Biologics (Cayman)'s fair value indicates a 9% potential upside to its current price that may not last much longer.
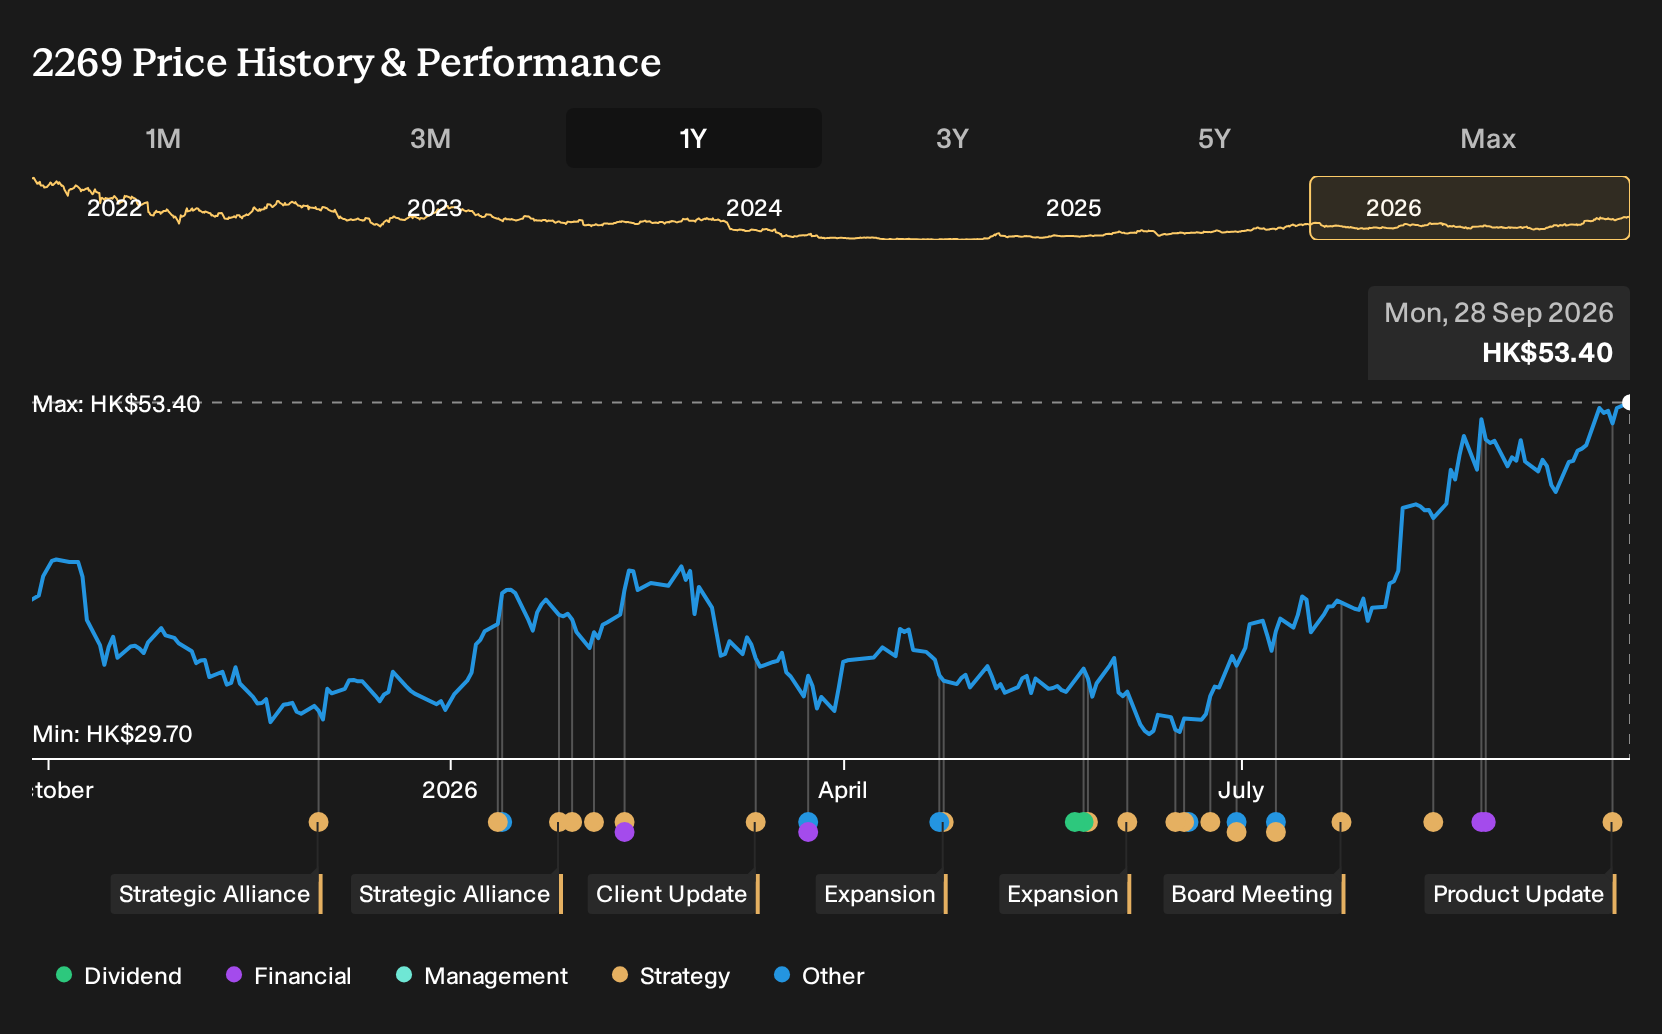
Exploring Other Perspectives
The more bullish analysts focus on WuXi Biologics’ pipeline as the real swing factor. They were already modelling revenue of CN¥44.8b and earnings of CN¥11.1b by 2029, far above the CN¥38.0b and CN¥9.1b in the baseline view. This fresh FDA success could push those optimistic narratives even further. It is therefore important to explore a full range of forecasts before deciding what you believe.
Explore another WuXi Biologics (Cayman) fair value estimate, including one that suggests as much as 80% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your WuXi Biologics (Cayman) research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for WuXi Biologics (Cayman). The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WuXi Biologics (Cayman)'s overall financial health at a glance.
Looking For More Ideas Beyond WuXi Biologics?
If WuXi Biologics has sharpened your focus on quality, systems, and long term execution, it can be useful to widen the lens and see how other companies stack up on different dimensions using the Simply Wall St Screener.
- If capital preservation is your priority, start with a basket of resilient operators screened for lower risk profiles through the 226 resilient stocks with low risk scores.
- If value is your theme right now, scan a curated universe of what our filters flag as attractively priced quality companies by using the 193 high quality undervalued stocks.
- If stable income matters most to you, focus on businesses that pair higher yields with more robust fundamentals via the 159 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com