


- Shenzhen International Holdings has completed the fifth tranche of its 2026 medium term notes, issuing RMB 1,000 million of 5 year debt at a 1.65% coupon, further extending its onshore funding stack.
- This relatively low funding cost gives Shenzhen International Holdings more room to manage interest expenses and timing of capital projects without immediately tapping higher cost sources of finance.
- Next we will look at how Shenzhen International Holdings' investment narrative could be influenced by this low coupon, 5 year funding move.
Scan other companies using similar low cost funding playbooks with the hand picked 226 resilient stocks with low risk scores that prioritize resilience and balance sheet strength alongside measured expansion plans.
What Is Shenzhen International Holdings' Investment Narrative?
To own Shenzhen International Holdings, you need to be comfortable with a capital heavy story anchored in toll roads, logistics hubs and ports across the PRC. The big belief is that steady infrastructure usage and logistics demand can support earnings while the group manages a complex funding base. The new RMB 1,000 million, 5 year notes at 1.65% fit that picture. Cheaper onshore borrowing can ease near term interest pressure and give management more room to time maintenance, upgrades and logistics park projects.
In the short term, the real swing factors stay on the ground. Traffic volumes, port throughput and pricing discipline across concessions matter more than any single bond issue. The notes do speak directly to the biggest financial risk. Debt is not well covered by operating cash flow, dividend coverage by free cash flow is thin and recent results include large one off items and a drop in profit margins. If Shenzhen International Holdings uses this low cost funding to refinance rather than stretch the balance sheet further, that could help sentiment, especially with the share price down 41.4% year to date and trading on about 8x earnings.
That said, there is still a sticking point in the story that only really comes into focus once you look closely at ...
There's only one way to know the right time to buy, sell or hold Shenzhen International Holdings. Head to Simply Wall St's company report for the latest analysis of Shenzhen International Holdings's Fair Value.
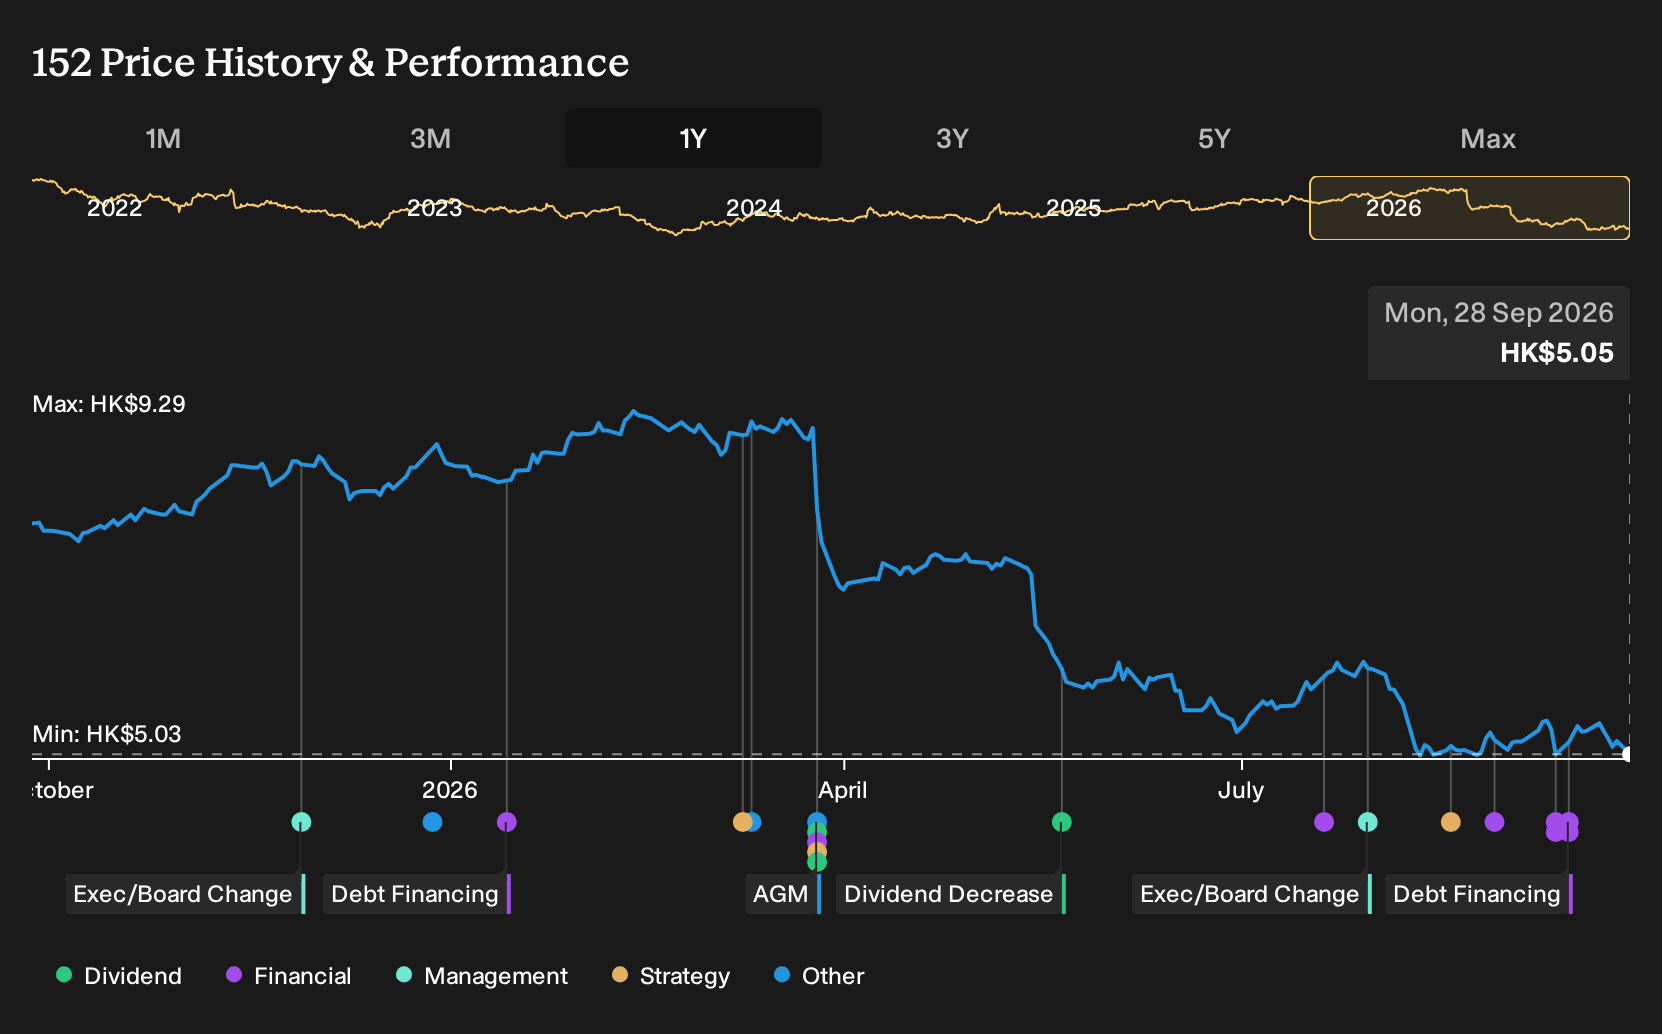
Exploring Other Perspectives
Community members on Simply Wall St have posted 2 fair value views for Shenzhen International Holdings, ranging from HK$7.62 to HK$9.49. That cluster gives you a tight but still varied set of anchor points. These opinions all predate the new 1.65% debt, so fresh funding terms could reshape how you and other investors judge future resilience.
Explore another Shenzhen International Holdings fair value estimate, including one that suggests as much as 88% upside from the current price.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Shenzhen International Holdings research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Shenzhen International Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Shenzhen International Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Shenzhen International Holdings?
If the Shenzhen International Holdings story has you thinking about portfolio upgrades, it can help to scan a wider field of opportunities using the Simply Wall St Screener and look for businesses that better match your risk tolerance and income goals.
- Prioritize financial resilience by reviewing a list of solid balance sheet and fundamentals (201 results) and see which businesses pair prudent leverage with steady fundamentals.
- If income is the focus, scan for companies in the 159 dividend fortresses and weigh their yields against balance sheet strength and cash generation.
- For those hunting for the next underfollowed opportunity, filter through a 618 high quality undiscovered gems that combines quality metrics with limited current attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com