


With a market cap of $40.3 billion, Ares Management Corporation (ARES) is a leading global alternative investment manager providing primary and secondary investment solutions across credit, real estate, private equity, and infrastructure. The company seeks to support businesses and create long-term value through flexible capital and collaboration across its investment groups.
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and Ares Management fits this criterion perfectly. As of June 30, 2026, Ares managed more than $671 billion in assets across North America, South America, Europe, Asia Pacific, and the Middle East.
Shares of the Los Angeles, California-based company have declined 34.7% from its 52-week high of $181.19. ARES stock has risen 8.9% over the past three months, outperforming the State Street Financial Select Sector SPDR ETF’s (XLF) 1.7% gain over the same time frame.
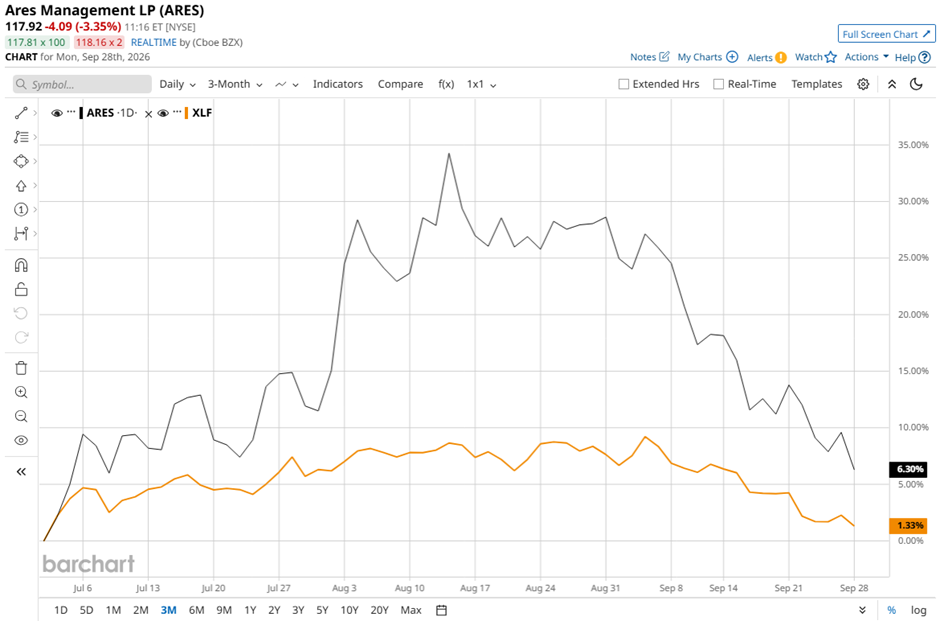
The stock is down 26.5% on a YTD basis, a steeper decline than XLF’s marginal drop. In the longer term, shares of Ares Management have decreased 27.1% over the past 52 weeks, compared to XLF’s 1.1% return over the same time frame.
Yet, ARES stock has been trading above its 50-day moving average since April.
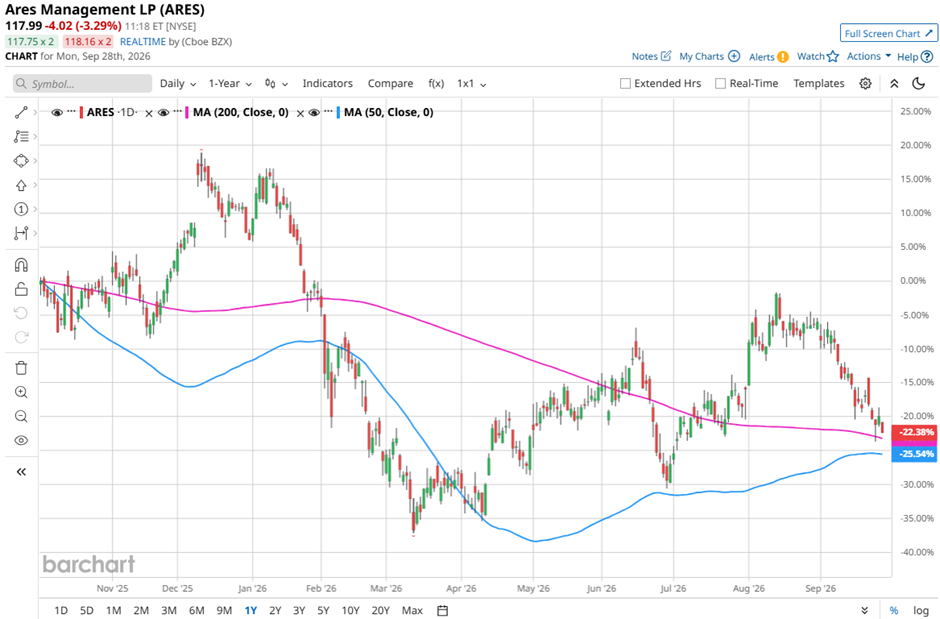
Ares Management has underperformed over the past year as concerns over AI disruption have weighed on alternative asset managers, particularly due to exposure to software companies that could face disruption from artificial intelligence. The stock has also been pressured by broader concerns around private credit, including elevated fund withdrawal requests and questions about lending standards and the ability of heavily indebted software companies to withstand AI-driven disruption.
In comparison, rival BlackRock, Inc. (BLK) has outpaced ARES stock. BLK stock has risen marginally on a YTD basis and declined 7.3% over the past 52 weeks.
Despite the stock’s weak performance over the past year, analysts remain moderately optimistic on Ares Management. The stock has a consensus rating of “Moderate Buy” from 21 analysts in coverage, and the mean price target of $153.09 is a premium of 29.7% to current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.