


Meridian Energy (NZSE:MEL) just reported its August 2026 operating update, with total generation at 1,432 GWh compared with 1,179 GWh a year earlier, which is drawing fresh attention to the stock.
Meridian Energy’s NZ$5.58 share price has seen a 6.29% 1 month share price return, even as the 3 month share price performance declined 4.12%. A 5 year total shareholder return of 37.55% signals that longer term momentum has been stronger than the recent pullback.
Compare Meridian Energy’s latest move in generation and share price with a hand-picked group of resilient utilities and infrastructure players in the 221 resilient stocks with low risk scores.
Given Meridian Energy’s strong recent generation figures and mixed share price performance, the real tension now is simple: Does the current valuation still leave enough upside to justify the risk you are taking on?
Price-to-Earnings of 113.7x: Is it justified?
On simple multiples, Meridian Energy carries a heavy valuation tag. The stock trades on a P/E of 113.7x, while the last close was NZ$5.58. This raises the question of whether investors are paying far ahead of current earnings power.
The P/E ratio compares what the market is willing to pay today for each dollar of reported profit. For a renewable utility like Meridian Energy, a high P/E can signal that shareholders are focusing on expected profit growth and cash flow stability rather than current earnings alone.
Here the gap is large. The P/E of 113.7x is far above both the Global Renewable Energy industry average of 14.9x and the estimated fair P/E of 35.5x. That spread indicates that the market is already pricing in a strong earnings path and may be assigning a richer valuation than the level our fair ratio implies the market could move towards over time.
Explore the SWS fair ratio for Meridian Energy.
Result: Preferred multiple of Price-to-Earnings of 113.7x (OVERVALUED)
Still, the story could change quickly if wholesale electricity prices soften or if earnings growth fails to catch up with Meridian Energy’s premium P/E multiple.
Find out about the key risks to this Meridian Energy narrative.
Another View On Meridian Energy’s Value
That steep P/E ratio paints one picture. A very different one comes from our DCF model, which suggests Meridian Energy’s shares at NZ$5.58 are trading below an estimated future cash flow value of NZ$9.85, implying the stock screens as undervalued on that measure.
This kind of gap between earnings based pricing and a cash flow based estimate can cut both ways. It may signal a genuine opportunity if cash generation holds up, or it may highlight that the model is baking in assumptions you would not be comfortable with. Which lens feels more realistic to you as a shareholder or potential buyer?
Look into how the SWS DCF model arrives at its fair value.
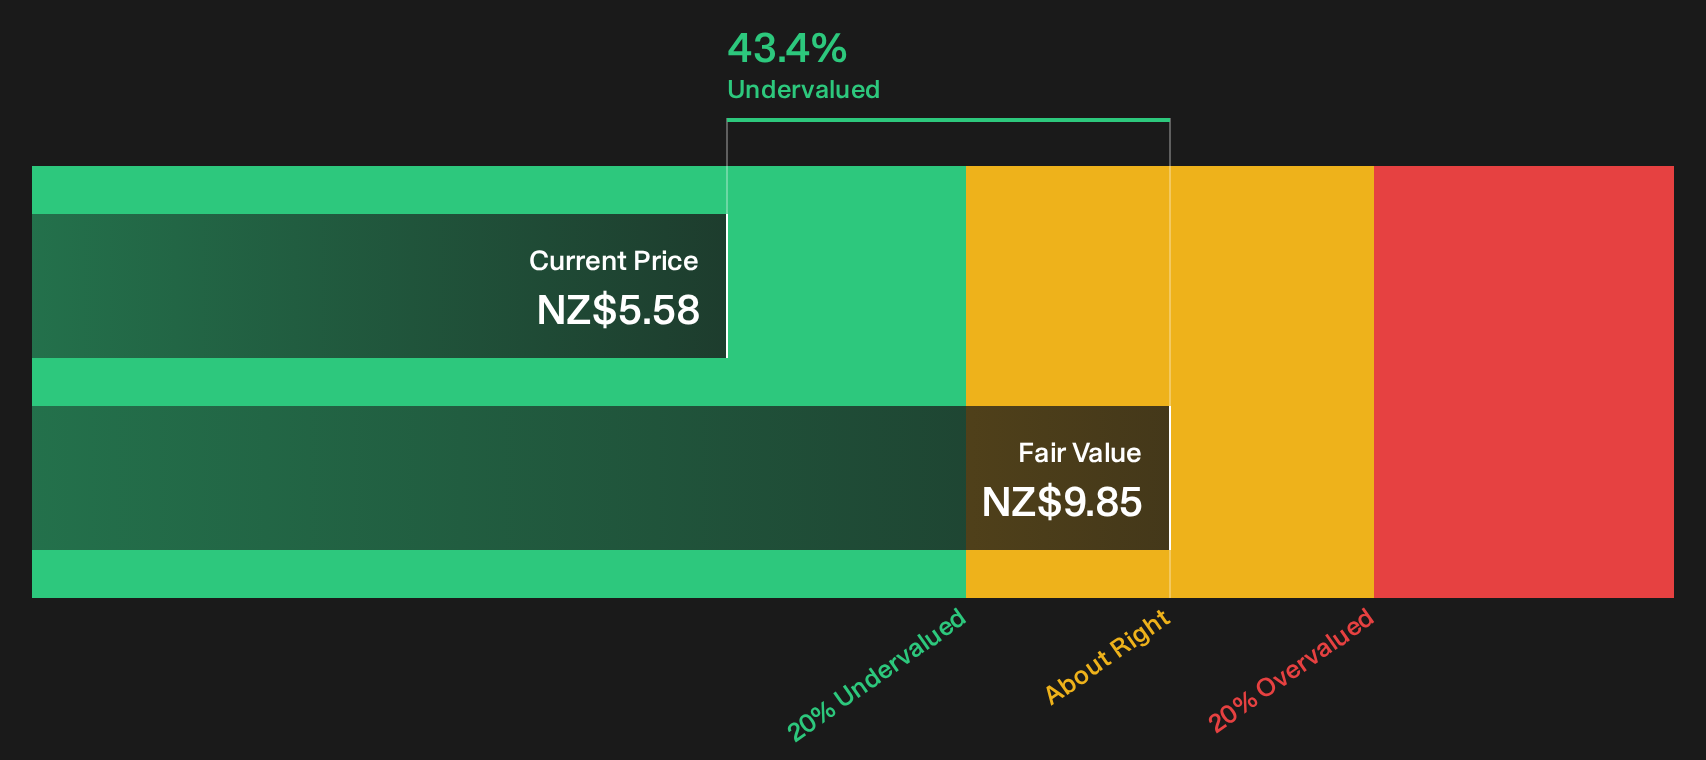
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Meridian Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Meridian Energy’s valuation and risks call for your own judgment, so move quickly, stress test the assumptions, and weigh both sides with the 3 key rewards and 1 important warning sign.
Looking for more Meridian Energy investment ideas?
If Meridian Energy has sharpened your focus on pricing and cash flows, do not stop here. Use fresh screens to widen your watchlist and pressure test your next move.
- Target potential bargains by scanning a curated group of resilient businesses in the 194 high quality undervalued stocks.
- Zero in on income opportunities by reviewing companies that feature in the 167 dividend fortresses.
- Prioritise resilience by tracking financially robust candidates highlighted in the list of solid balance sheet and fundamentals (201 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com