


KeyBanc’s senior analyst Sophie Karp says it’s now time for investors to start building a long-term position in First Solar (FSLR). She upgraded the utility-scale solar company this morning to “Sector Weight,” electing not to assign a price target, which suggests FSLR should perform roughly in line with the broader clean energy space in the months ahead.
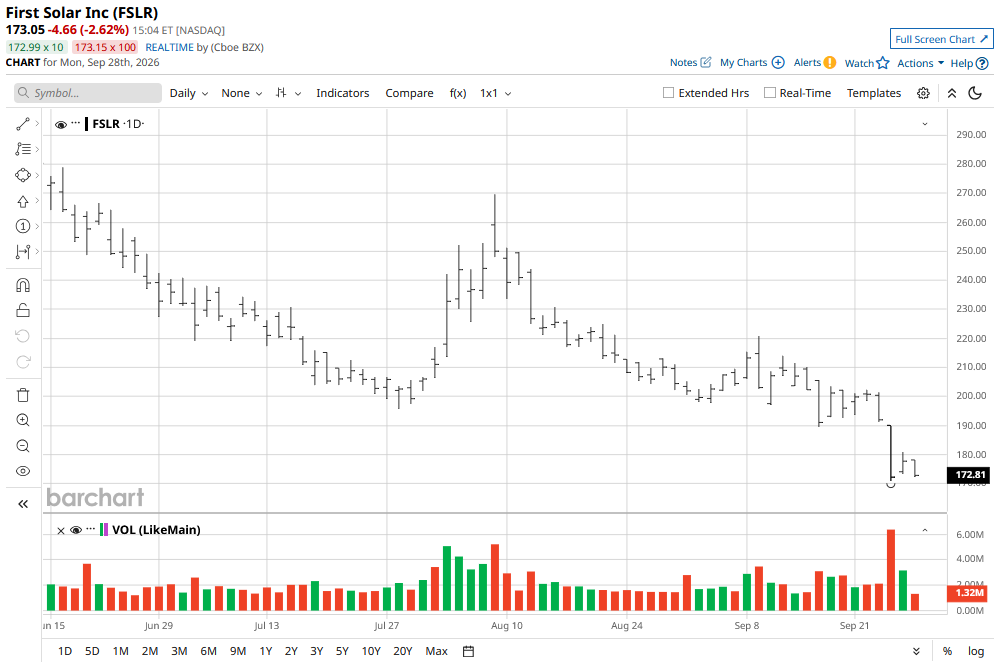
Karp’s bullish call brings a much-needed reprieve to First Solar stock, which is currently down more than 40% versus its year-to-date high in early June.
What Made KeyBanc Upgrade First Solar Stock?
Karp’s upgrade centers on the belief that FSLR shares’ massive retreat in recent months has reset valuation to levels that limit meaningful further downside.
At a forward price-to-earnings (P/E) ratio of less than 10x, the firm’s multiple currently sits notably below its historical averages.
The KeyBanc analyst, however, emphasized that her change of heart is based purely on valuation metrics, and not a surprise improvement in First Solar’s operational backdrop.
In fact, Barchart currently has an “88% SELL” average opinion on First Solar, indicating that the technical setup still cautions against buying the clean energy stock at current levels.
The Math Behind Karp’s Improving View
Reinforcing KeyBanc’s improving view on First Solar shares is the company’s formidable tangible asset backing.
According to Sophie Karp, its combined cash reserves and the capitalized value of its Section 45X advanced manufacturing tax credits amount to roughly $135 per share.
In her research note, she dubbed that a durable valuation floor, offering shareholders a downside cushion even as domestic markets grapple with two years of excess inventory and sluggish project starts.
In short, while domestic oversupply and policy headwinds persist, KeyBanc believes these tangible assets insulate the clean energy stock against severe incremental selloffs.
How Wall Street Recommends Playing FSLR Shares
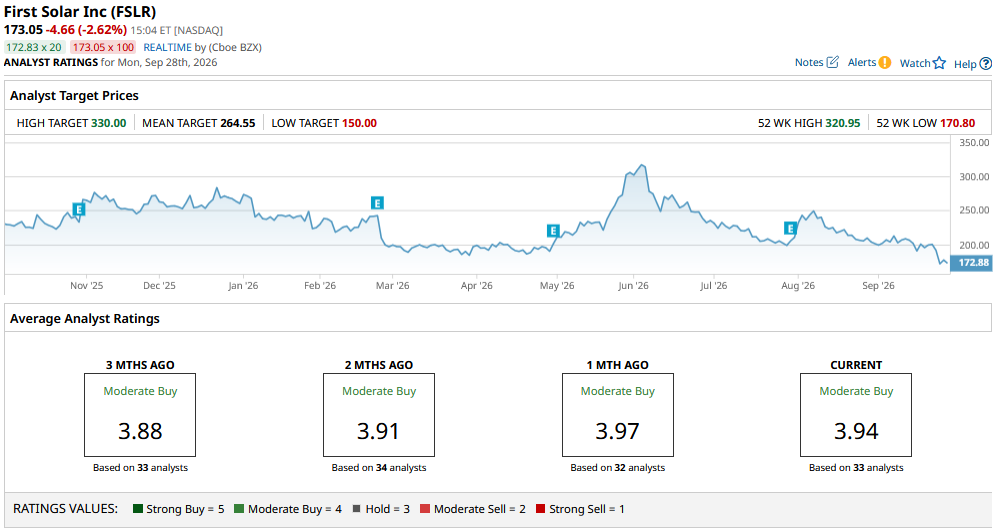
Despite First Solar’s disappointing performance in 2026, other Wall Street firms largely agree with KeyBanc’s bullish stance on FSLR stock as well.
According to Barchart, the consensus rating on First Solar remains at “Moderate Buy,” with the mean price target of about $265 indicating potential upside of more than 50% from current levels.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.