


Dollarama (TSX:DOL) drew fresh attention after raising its fiscal 2027 same-store sales outlook to 4% to 4.5%, alongside higher second quarter revenue and earnings compared with the previous year.
Despite the upbeat guidance and higher recent sales and earnings, Dollarama’s share price tells a mixed story. The stock has gained 4.35% on a 1 month share price basis and 2.73% over 7 days, yet it remains down 10.96% year to date. At the same time, the 3 year total shareholder return of 98.55% and 5 year total shareholder return of 245.09% point to strong longer term momentum that investors are weighing against current expectations.
Scan the retail momentum shaping Dollarama’s peer group by checking our hand-picked 5 high quality undervalued stocks that combine cash generation with balance sheet strength.
Dollarama’s higher guidance and Q2 earnings point to a business that is still producing growth, yet the share price is lagging recent fundamentals. Is this latest move about operations, sentiment, or the price now attached to both?
Most Popular Narrative: 21% Undervalued
Against a last close of CA$183.57, the most followed narrative sets Dollarama’s fair value at CA$232.00, which points to a meaningful gap that depends on how durable its store rollout and supply chain economics prove to be.
Dollarama's expanding private label and direct sourcing capabilities in both North America and new markets like Australia and Latin America enable product margin control and pricing flexibility compared to peers, which may support net margin improvement as these efforts scale globally.
The company's integration and transformation of acquired and newly entered markets, supported by its corporate culture and real estate optimization, may contribute to multi-geography operating leverage and a longer potential runway for earnings growth beyond what is currently capitalized in the share price.
See why 6 investors see Dollarama as 21% undervalued.
Result: Fair Value of CA$232.00 (UNDERVALUED)
Still, the bullish Dollarama narrative runs into real friction if wage and compliance costs climb faster than expected, or if digital lightweights start chipping away at store traffic.
Find out about the key risks to this Dollarama narrative.
Another View On Dollarama’s Valuation
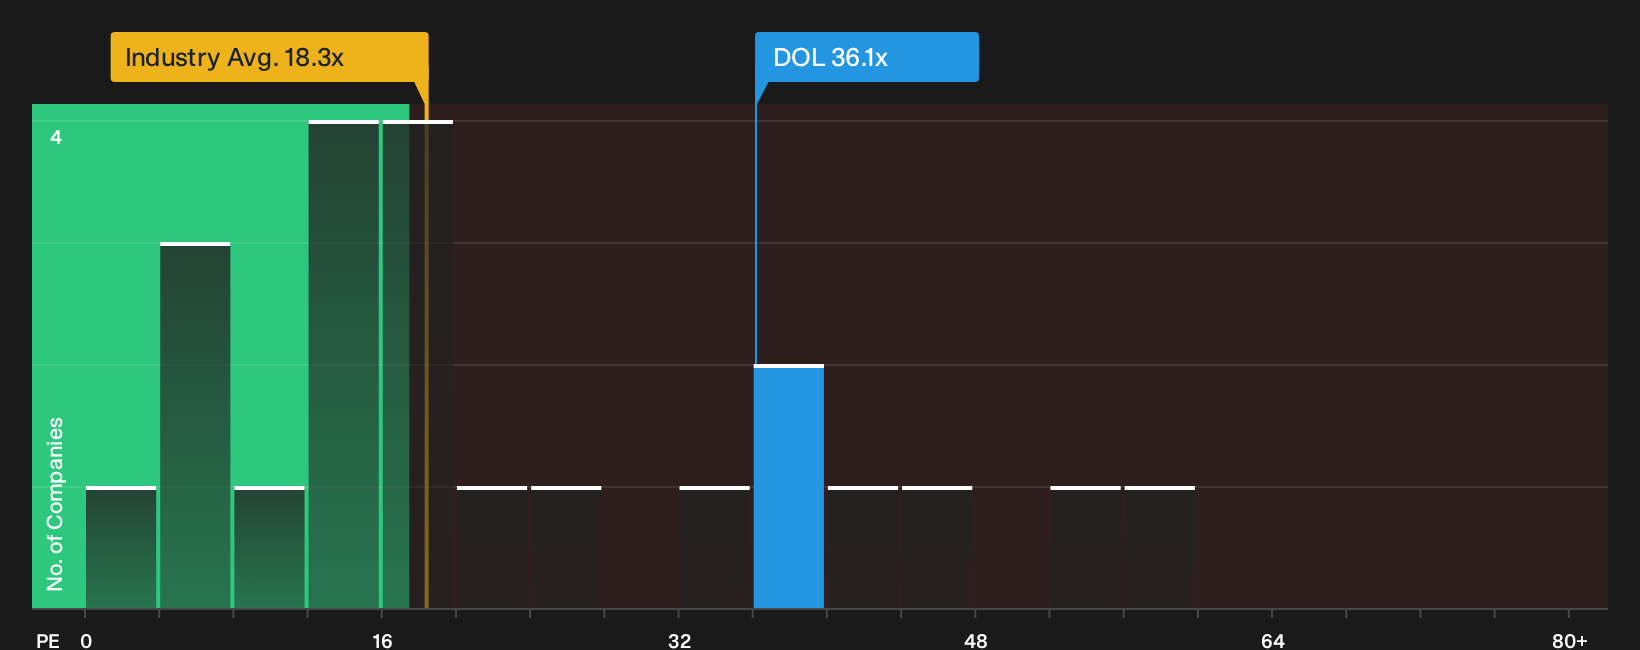
The bullish narrative pegs Dollarama’s fair value at CA$232.00, yet the current P/E of 36.1x sits far above the fair ratio of 25.3x, the Canadian Multiline Retail industry at 26.7x, and peers at 16.7x. That richer multiple raises a simple question: How much optimism is already built into today’s price?
Investors who want to see how those earnings multiples stack up across the sector can review the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Dollarama feels familiar, you can move quickly from headline narratives to your own verdict by reviewing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Dollarama?
If Dollarama has sharpened your focus, do not stop here. Broader ideas can help you stress test your thinking and avoid leaning on a single story.
- Target future upside with disciplined criteria by scanning a curated 9 high quality undiscovered gems that highlight companies with strong fundamentals flying under most investors’ radars.
- Prioritize resilience by reviewing a 8 resilient stocks with low risk scores that filters for businesses with sturdier profiles when markets start testing conviction.
- Strengthen your core holdings by assessing a list of solid balance sheet and fundamentals (7 results) that focuses on companies with cleaner finances supporting long term compounding potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com