


Littelfuse (LFUS) stock is back in focus after the company outlined a multi year leadership transition, with longtime executive Deepak Nayar retiring and Dr. Karim Hamed expanding his responsibilities.
Littelfuse shares have climbed strongly over 2026, with a year to date share price return of 63.48% and a 1 year total shareholder return of 67.97%. However, the 90 day share price return declined 5.74%, suggesting momentum has cooled slightly as investors digest leadership changes and earlier gains.
Scan how Littelfuse compares to other industrial and electronics plays showing strong recent strength with the hand picked 33 high quality undervalued stocks.
Littelfuse now trades near record territory after a strong run, yet recent cooling in the chart and a fresh leadership roadmap raise a simple issue: Is most of the upside already in the rearview, or not?
Most Popular Narrative: 12% Undervalued
Littelfuse is framed as undervalued in the most widely followed narrative, with a fair value of $488.75 against a last close of $429.21. This puts the focus firmly on whether the current price reflects its longer term earnings potential.
The rapid buildout of renewable energy infrastructure, grid storage, and sustainable grid ecosystems is resulting in double-digit sales growth and a robust opportunity pipeline for Littelfuse, positioning the company to benefit from continued secular tailwinds and expanding its addressable market, which should positively impact both revenues and margins.
See why 6 investors see Littelfuse as 12% undervalued.
Result: Fair Value of $488.75 (UNDERVALUED)
Still, two pressure points could knock this Littelfuse narrative off course: weaker power semiconductor demand and tougher automotive and industrial cycles than analysts currently assume.
Find out about the key risks to this Littelfuse narrative.
Another View: Littelfuse Looks Expensive On Sales
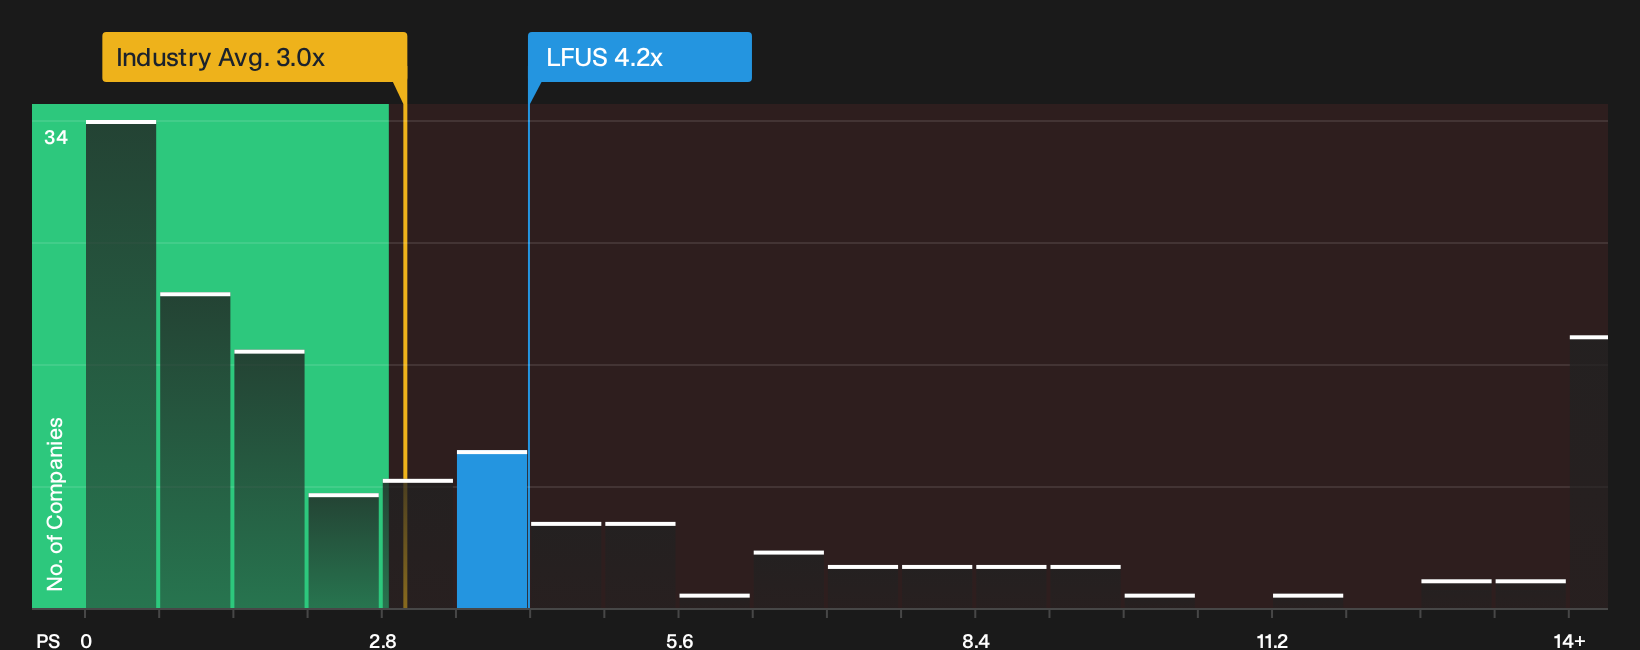
DCF and analyst targets point to Littelfuse trading below estimated fair value. The picture shifts when you look at the price tag on its sales. The stock changes hands at a P/S of 4.2x, compared with both the US Electronic industry and peer average at 3x, and a fair ratio of 2.7x.
That gap suggests investors are already paying a premium for Littelfuse on revenue today, even though one model signals upside on long term cash flows. The question for you is simple: Are you comfortable paying well above the fair ratio for each dollar of sales, or not?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed sentiment on Littelfuse so far feels unresolved, treat that as your cue to move quickly. Weigh the evidence yourself, then pressure test those positives with the 2 key rewards.
Looking for more Littelfuse style investment ideas?
If Littelfuse has your attention, do not stop there. Use the screener to surface fresh opportunities before they move out of reach.
- Target dependable income streams by reviewing companies in the 6 dividend fortresses that may appeal if dividends matter to your plan.
- Hunt for mispriced potential by scanning the 16 high quality undiscovered gems that might not yet be on most investors' radar.
- Prioritise resilience in choppy conditions by filtering for businesses in the 30 resilient stocks with low risk scores that show stronger risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com