


San ju San Financial Group Inc (TSE:7322) just paired a higher earnings outlook with richer dividend guidance, tying both moves to stronger expected net interest income at its main banking subsidiary.
The higher guidance has landed in a market that was already leaning in San ju San Financial Group Inc's favor, with the share price climbing 3.31% over the past day and 10.78% across the last week to ¥2,312.0, contributing to a 34.42% 90 day share price return and a 1 year total shareholder return of 168.30%. This builds on a multi year total shareholder return of more than 7x over five years and indicates that momentum has been building rather than fading as investors reassess both earnings potential and dividend capacity.
Look beyond San ju San Financial GroupInc's upgraded outlook and compare it with other financial stocks that have rising return profiles using the hand picked 20 resilient stocks with low risk scores for your next round of ideas.
San ju San Financial GroupInc now carries a much richer track record and a fatter dividend forecast, so the move raises a simple issue: Are you paying for better fundamentals or just hotter sentiment as we look at valuation next?
Price-to-Earnings of 20x: Is it justified?
San ju San Financial GroupInc trades on a P/E of 20x, which sits above the averages for both the Japan banks sector and its closest peers at the current ¥2,312 share price.
The P/E multiple compares what investors are paying for each unit of earnings. For a lender like San ju San Financial GroupInc, this often reflects how the market views the consistency of profit, the quality of its loan book, and the stability of net interest income.
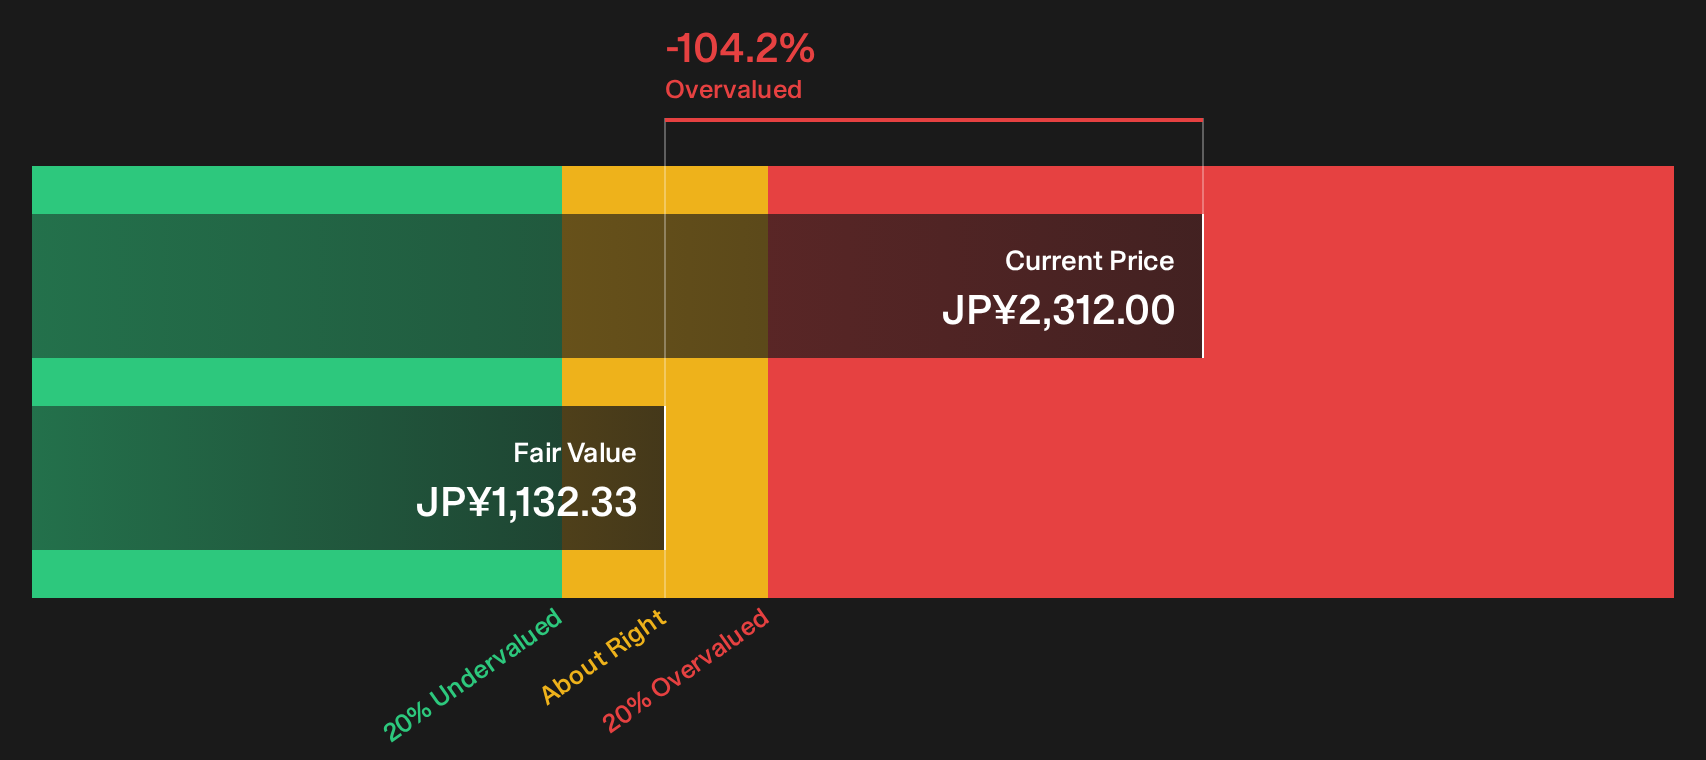
Earnings growth of 19.4% per year over the past 5 years, with profit margins currently at 13.8% compared with 12.4% a year ago, suggests the higher valuation is tied to a stronger earnings profile rather than a flat profit base. At the same time, the SWS DCF model points to a future cash flow value of ¥1,132.33, which is well below the present market price. This indicates that the current P/E implies investors are willing to pay a premium well above that cash flow estimate.
Compared with the JP Banks industry average P/E of 16x and a peer group average of 18.7x, the 20x ratio for San ju San Financial GroupInc is materially richer. This signals that the market is assigning this bank a higher tag than both its direct competitors and the broader sector.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 20x (OVERVALUED)
Still, the story around San ju San Financial GroupInc can change quickly if credit quality weakens or funding costs rise faster than net interest income.
Find out about the key risks to this San ju San Financial GroupInc narrative.
Another view on San ju San Financial GroupInc's value
The SWS DCF model paints a very different picture for San ju San Financial GroupInc. On this cash flow view, estimated value clusters around ¥1,132 per share, which is far below the current ¥2,312 price. That gap raises a blunt question for investors: Is this strength in the stock or just optimism stretching the valuation?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out San ju San Financial GroupInc for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on San ju San Financial GroupInc so far. If you want to act before sentiment swings again, consider both sides of the story with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond San ju San Financial GroupInc?
If San ju San Financial GroupInc has caught your attention, do not stop here. Fresh ideas often come from comparing strong performers with other quality opportunities.
- Target resilience by scanning companies that show stronger balance sheets and cleaner fundamentals through the list of solid balance sheet and fundamentals (22 results).
- Hunt for value by reviewing the 18 high quality undervalued stocks that may offer stronger fundamentals at prices the market has not fully recognised yet.
- Focus on income potential by checking the 22 dividend fortresses that may combine higher yields with more durable payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com