


- Hudbay Minerals updated its Snow Lake mine plan after increasing mineral reserves to 27.0 million tonnes with about 2.0 million ounces of gold and a reserve mine life that now extends to 2043.
- The refreshed plan focuses on higher mill throughput and gold recoveries across New Britannia and Stall, which reshapes how Hudbay Minerals uses its 6,300 tonnes per day processing capacity at Snow Lake.
- We will now assess how Hudbay Minerals' extended Snow Lake reserve life and gold production outlook could influence its broader investment narrative.
Scan Hudbay Minerals’ Snow Lake update and compare it with other potential gold and copper breakouts by reviewing the hand picked 36 elite gold producer stocks in the same space.
Hudbay Minerals Investment Narrative Recap
To own Hudbay Minerals, you need to believe the company can keep turning a concentrated set of assets into consistent cash flow, while managing permitting, cost and jurisdiction risks. The Snow Lake update supports that view by extending reserve life to 2043 and laying out a clearer gold production profile, which provides a longer operational runway in Manitoba.
The near-term swing factor still sits with execution on Snow Lake optimization and timing and cost control at Copper World. Higher throughput and recoveries at New Britannia and Stall are helpful, but wildfires, community issues or inflation in Canada and Peru remain key risks to that smoother production story.
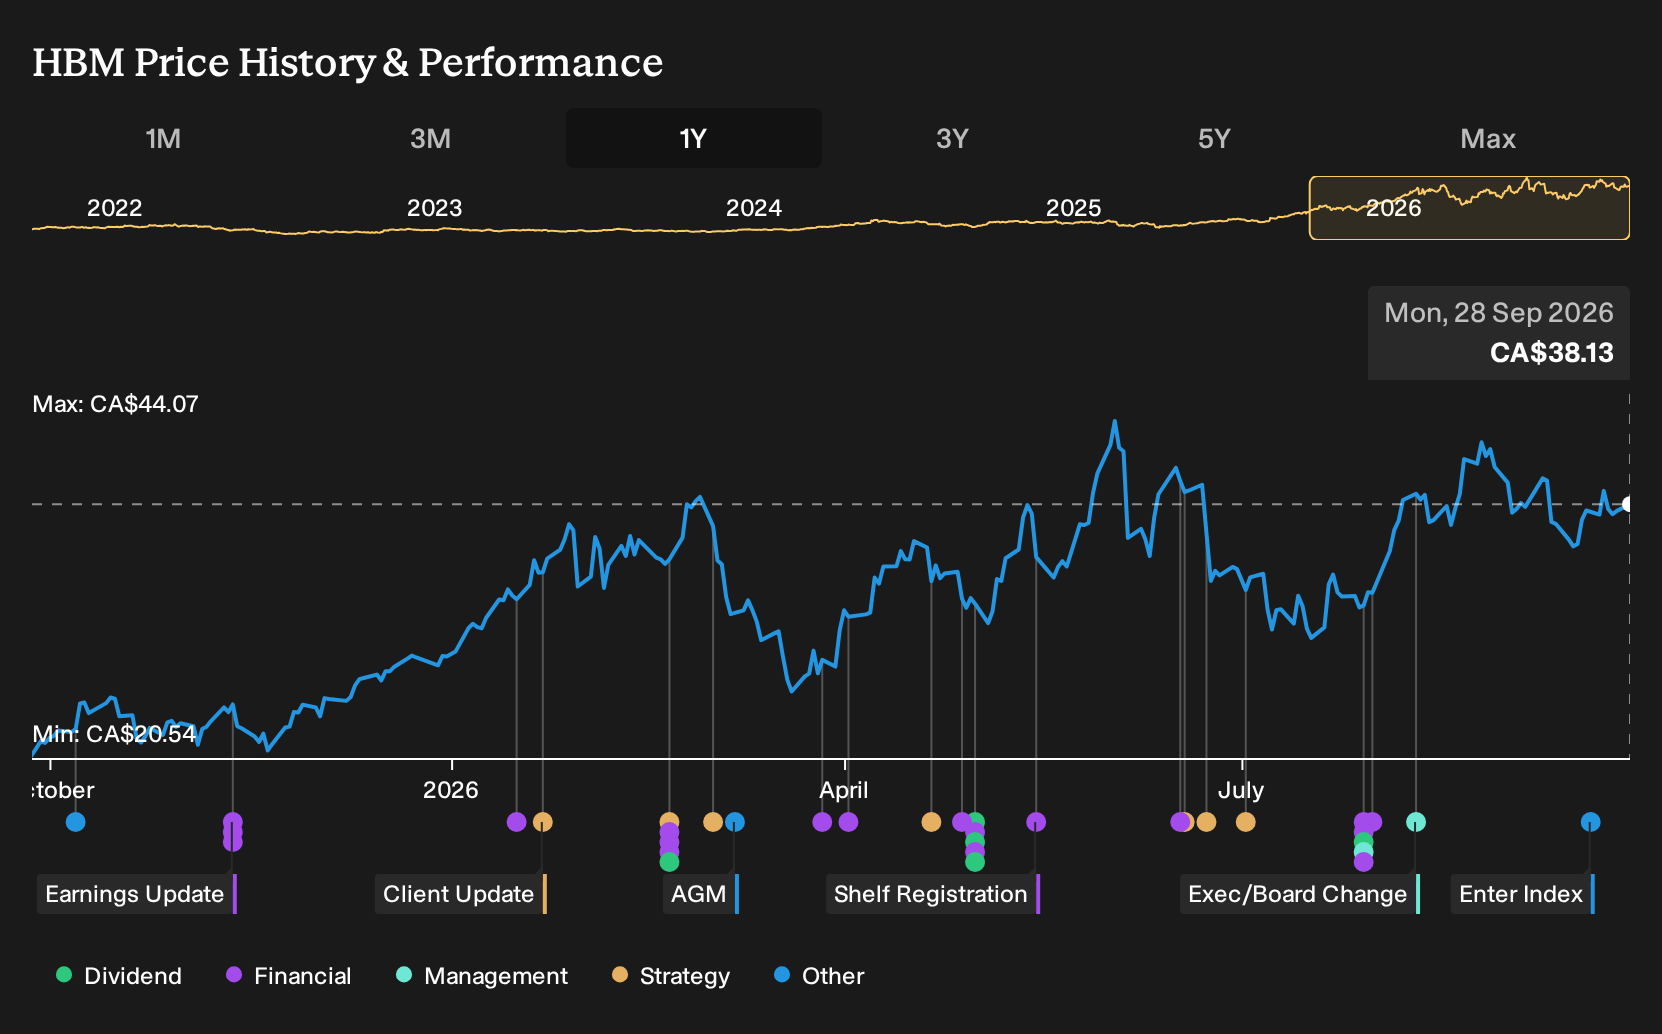
The recent inclusion of Hudbay Minerals in the FTSE All World Index is the development that most directly connects to Snow Lake for investors. A longer reserve life and a more detailed mine plan give larger institutions more visibility on volume and asset life, which can matter for index and benchmark-driven mandates.
Index inclusion can deepen liquidity and tighten trading spreads, which can make it easier for larger investors to build or reduce positions around operational catalysts. For Snow Lake, that means execution updates on mill performance, reserve conversion at Britannia Gold Project and progress toward the targeted late 2027 ramp at the 1901 zone may now take place with a somewhat broader shareholder base.
Hudbay Minerals' narrative projects $3.4 billion in revenue and $813.1 million in earnings by 2029, assuming 11.3% yearly revenue growth and an earnings increase of about $135 million from $678.2 million today.
Uncover why Hudbay Minerals' fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest analysts focus on Copper World risk rather than Hudbay Minerals’ Snow Lake upside. They were only pencilling in $3.0b of revenue and $448.8 million of earnings by 2029, far below the baseline. That more pessimistic script could shift as this fresh mine plan filters into updated views.
Explore 4 other Hudbay Minerals fair value estimates, including one that suggests the potential for as much as 83% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hudbay Minerals research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hudbay Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hudbay Minerals' overall financial health at a glance.
Looking for more investment ideas beyond Hudbay Minerals?
If Hudbay Minerals has sharpened your interest in metals and miners, it can help to compare this story with other listed businesses that match your risk appetite and income goals. The Simply Wall St Screener lets you quickly filter for different profiles so you can build a watchlist that fits how you like to invest.
- For investors who want quality and value in the same package, focus on companies flagged in the 7 high quality undervalued stocks that pair healthy fundamentals with prices that may not fully reflect them.
- If capital preservation is higher on your priority list, review companies highlighted in the 8 resilient stocks with low risk scores that score well on financial strength and business stability.
- When you want to cast the net wider for lesser known opportunities, scan the 9 high quality undiscovered gems that rarely attract headlines but still show solid underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com