


- Saipem SpA has been added to the FTSE All-World Index (USD), a global benchmark that often guides allocations for index-tracking and institutional portfolios.
- This index inclusion highlights Saipem’s business profile and may influence how investors evaluate its contract pipeline, capital intensity and project execution risks.
- We will now examine how Saipem’s investment narrative could evolve as global index inclusion draws additional attention from larger institutional investors.
Scan beyond Saipem and identify other potential index beneficiaries by reviewing the hand-picked 198 high quality undervalued stocks that may be drawing fresh attention from institutional capital.
What Is Saipem's Investment Narrative?
To own Saipem, you need to be comfortable with a heavy, project driven contractor that lives or dies by execution quality and capital discipline. The story leans on big, complex offshore and onshore projects, a sizeable presence in the Middle East, and an earnings profile that analysts expect to grow quickly, even if revenue forecasts are far more muted. That mix can create lumpier cash generation, which matters for a capital intensive group that still carries relatively low net profit margins of 1.7%.
The FTSE All World inclusion mainly affects who might own Saipem rather than how its yards or vessels operate. Index buying can support liquidity in the short term, but the real swing factors remain contract selection, pricing on new awards, and delivering projects without cost overruns. Dividend coverage already looks tight, with a 3.85% yield not well backed by earnings, and that pressure does not ease just because more passive funds may now hold the stock.
That said, one operational fault line still hangs over the Saipem equity story and it sits squarely in how the group handles...
There's only one way to know the right time to buy, sell or hold Saipem. Head to Simply Wall St's company report for the latest analysis of Saipem's Fair Value.
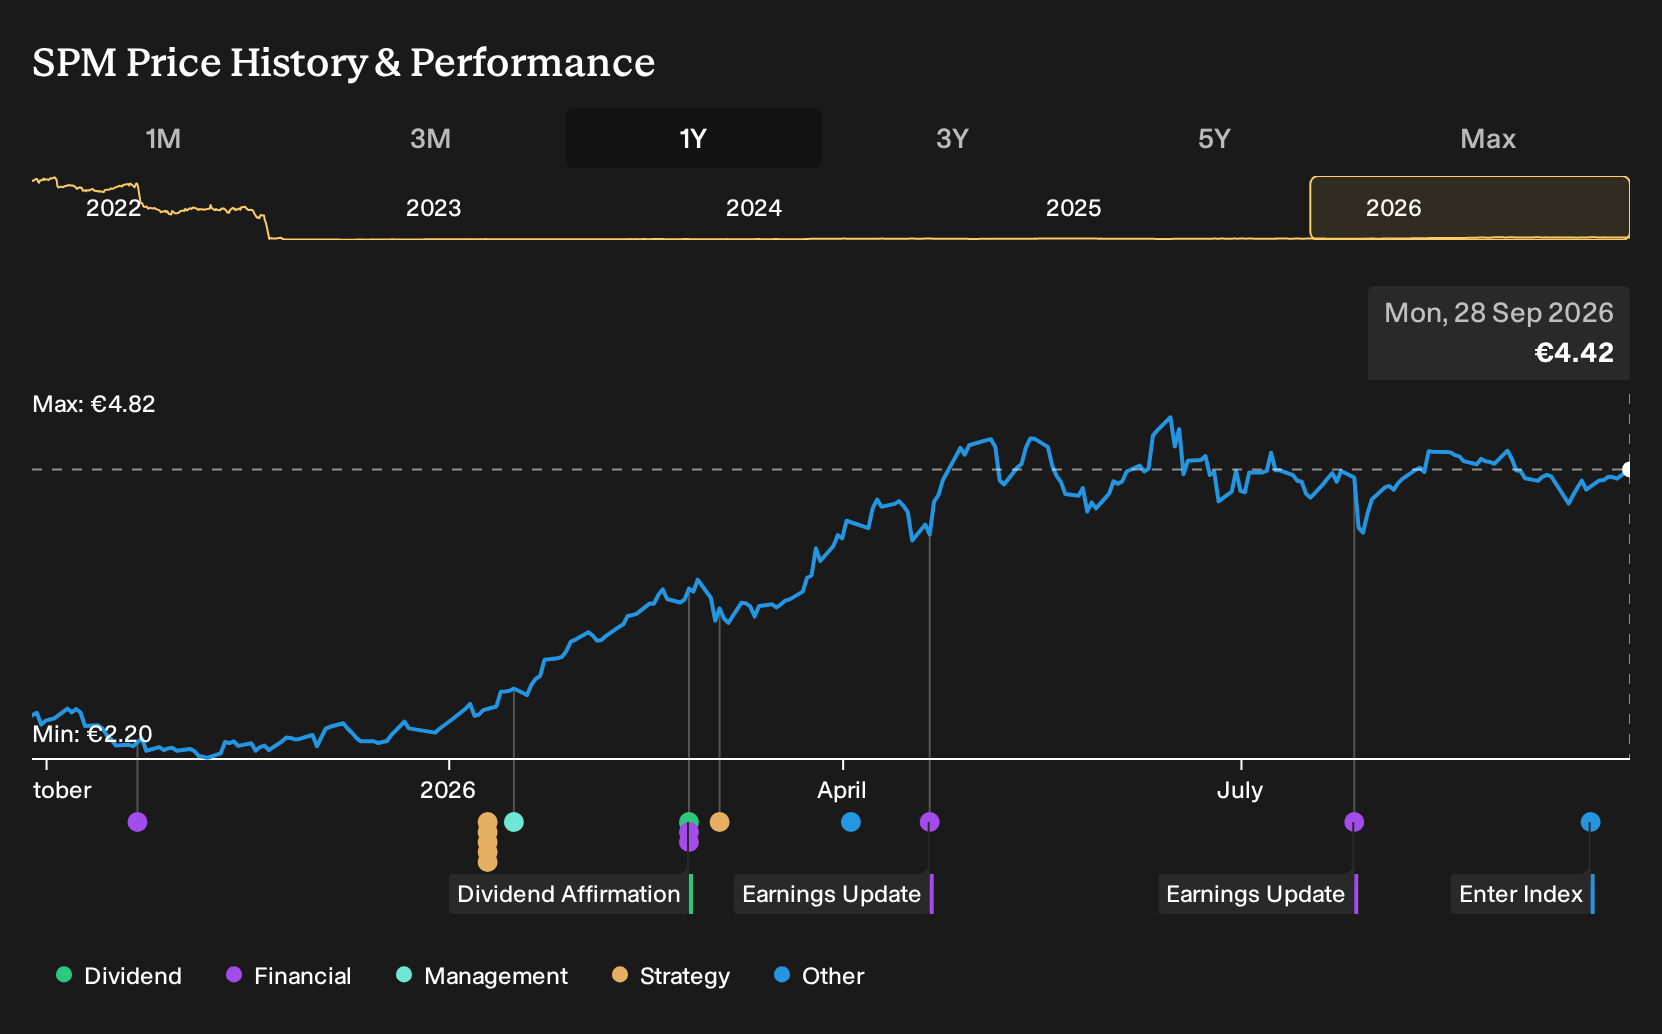
Exploring Other Perspectives
Energy transition risk sits at the center of the most bearish view on Saipem. Those analysts assume revenue shrinks by about 2.4% a year and still only reaches €14.5b by 2029, with earnings of €574.2m. That is far more cautious than consensus. Use the new index inclusion as a cue to compare these competing stories.
Explore 3 other Saipem fair value estimates, including one that suggests as much as 17% downside from the current price.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own judgment.
- A great starting point for your Saipem research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Saipem. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Saipem's overall financial health at a glance.
Looking For More Ideas Beyond Saipem?
If the Saipem story has sharpened your thinking on risk, return and balance sheet strength, use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- Target resilience first by focusing on businesses that pair healthier finances with lower risk profiles through the 221 resilient stocks with low risk scores.
- If a strong financial foundation matters most to you, filter for companies with sturdier balance sheets and cleaner fundamentals using the list of solid balance sheet and fundamentals (202 results).
- If you prefer hunting for underappreciated opportunities, where fundamentals look stronger than the current price implies, scan the 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com