


Global markets have been on edge after the BSE Sensex dropped over 1,000 points and the Nifty50 slipped below 22,900, driven in part by higher crude prices and foreign selling. Sharp swings like this often drag solid Indian businesses down with the pack, even when their cash generation looks healthy. This article highlights three Indian stocks where discounted prices may align with strong cash flow characteristics, based on our cash flow valuation screener.
The three stocks discussed below are only a small sample, and the full screen actually surfaced 3 more Indian businesses with equally compelling cash flow stories that are not covered here. To go past this shortlist and really pressure-test ideas, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and prioritize the highest conviction opportunities based on discounted cash flow signals.
Flair Writing Industries (NSEI:FLAIR)
Flair Writing Industries is a Mumbai based producer of pens, creative stationery and houseware. The writing instruments and allied products business, which generated about ₹12.8b in revenue, underpins the steady cash flows behind its place in this DCF based undervaluation screen, with the stock valued at roughly ₹24.8b.
Flair Writing Industries offers a useful test case for this cash flow focused list, because its core pen and stationery operations already generate the type of recurring cash flows that discounted cash flow models aim to capture, while newer categories reshape the growth profile.
"Scaling of high growth, higher margin creative and steel bottle and houseware portfolios, which together already contribute about 30% of revenue versus 15% last year, is expected to structurally lift consolidated revenue growth above prior guidance and sustain EBITDA margins near or above 18%."
This raises a key question: what happens to that cash flow story if a single assumption about future mix and pricing power shifts even slightly against expectations?
If that mix shift is what really moves the needle for Flair Writing Industries, the full narrative for Flair Writing Industries explains how pricing, categories, and cash flows could be decoupling.
Huhtamaki India (BSE:509820)
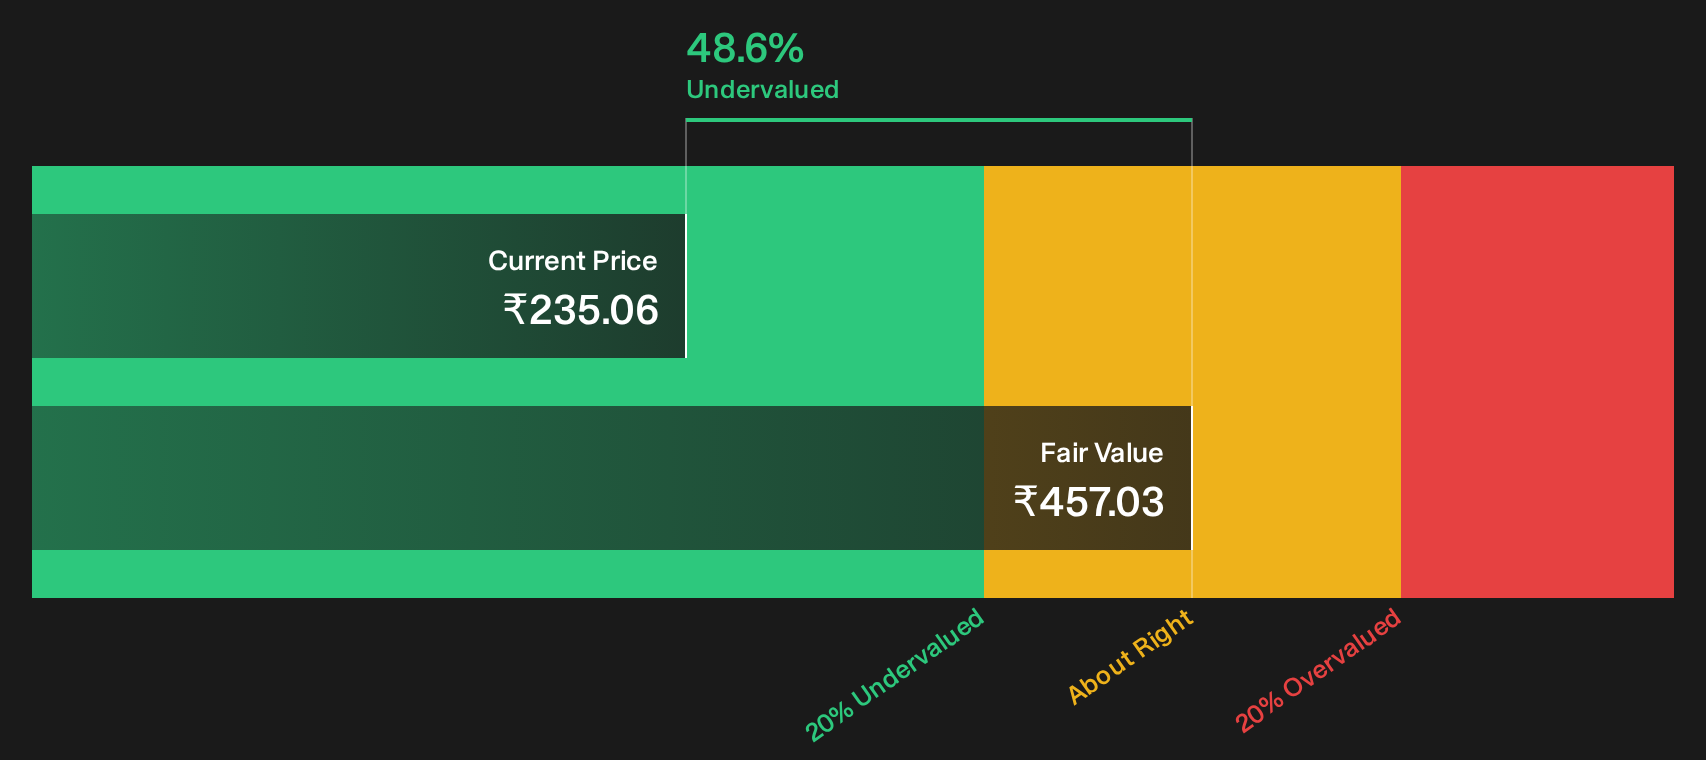
Huhtamaki India supplies flexible packaging and labelling for everyday products, with beverage and food solutions like its blueloop and blueLite PET/PE ranges creating the recurring manufacturing cash flows that suit this undervalued DCF screener. Consumer packaging brought in about ₹26.1b, and the business is valued at roughly ₹17.7b.
Huhtamaki India brings something slightly different to this undervalued cash flow list, because its consumer packaging engine is closely tied to long-term contracts with food, beverage and household brands, which gives real weight to any signal that cash generation is improving faster than the share price.
"Increasing focus on sustainable and recyclable packaging solutions (such as the blueloop portfolio, already contributing 27 to 30% of revenue) positions Huhtamaki India to capture future regulatory-driven growth and shift its product mix toward higher-margin, value-added categories, potentially supporting improved net margins and long-term revenue growth."
What really matters now is how one quiet shift in pricing power and product mix ultimately feeds through to those future margin assumptions.
That quiet shift is exactly what the full narrative for Huhtamaki India unpacks, showing where Huhtamaki India's cash flows could be accelerating faster than the headline story suggests.

TeamLease Services (NSEI:TEAMLEASE)
TeamLease Services runs large scale temporary and permanent staffing operations that create recurring cash flows from contractual staffing and payroll support, which is why it fits this undervalued cash flow screen. Most revenue comes from general staffing at about ₹110.1b, with specialised staffing at roughly ₹7b and other HR services near ₹2.5b, supporting a market value around ₹19.1b.
For investors looking at cash flow driven opportunities, TeamLease Services offers an HR services platform where recurring staffing contracts and payroll solutions help anchor visibility, while a newer education and skilling engine could change the mix of where future cash generation really comes from.
"The rapid growth of apprenticeship adoption, accelerating government skilling initiatives, and TeamLease's unique partnerships with 22 universities position it as the clear national leader in work-integrated learning, paving the way for a new, high-growth, higher-margin revenue stream that is underappreciated in current earnings estimates."
What ultimately happens to those future margins and cash flows will hinge on how one pressure on the wider staffing model plays out.
That pressure point is exactly where the real story starts, and the full narrative for TeamLease Services shows how TeamLease Services could turn staffing headwinds into accelerating cash generation and pricing power.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the next breakout ideas rarely stay under the radar for long. Scan these fresh stock shortlists before the momentum is fully caught and act now.
- Spot resilient performers that can keep moving when weaker tickers stall by scanning a curated set of 221 resilient stocks with low risk scores while the window is still open.
- Follow structural shifts in automation and AI by tracking curated leaders from the 92 robotics and automation stocks before capital chases the late momentum.
- Position ahead of potential infrastructure spending trends by scanning hand picked utilities and grid specialists inside the 39 power grid technology and infrastructure stocks while they are still dropping under most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com