


- Avolta AG partnered with Hawaii’s Department of Transportation to expand and operate food and beverage concepts across three of the state’s largest airports, working with local brands, producers and award-winning chefs to build menus around regional ingredients.
- The focus on Hawaiian culinary identity signals a push by Avolta into higher engagement, experience-led airport dining. This could influence concession economics, operating complexity and long term demand for its travel retail and hospitality offering.
- We will look at how Avolta's investment narrative interacts with this Hawaii airport dining partnership built around local culinary concepts.
Scan how Avolta’s Hawaii push compares with other travel and hospitality operators leaning into experience-led spending by reviewing our hand-picked 618 high quality undiscovered gems in adjacent consumer sectors.
Avolta Investment Narrative Recap
To own Avolta, you need to believe that physical travel hubs still matter and that higher quality, localized experiences can support earnings over time. The Hawaii partnership leans into exactly that thesis, but on its own probably does not shift the near term picture. The bigger swing factor remains how effectively Avolta converts passenger volumes into higher spend per traveler across regions.
The most immediate risk still sits with concession pressure and traffic sensitive volumes, especially if geopolitical events or weak North American flows hit spending. Experience heavy formats like Hawaii can raise operating complexity and upfront investment, so execution and cost discipline around new concepts matter just as much as headline contract wins.
The recent €350m senior notes issuance at a 5.25% coupon is the announcement that ties closest to these new projects. Avolta is leaning on external funding rather than customer deposits, and interest payments are not well covered by earnings according to existing analysis. As a result, each expansion move lands on a balance sheet that already carries meaningful obligations.
For you, the link between the Hawaii push and the bond issue is about capacity to fund growth while still working toward better interest cover and profitability. Analysts expect earnings to grow and see upside to the share price. That view depends heavily on Avolta turning experiential contracts into solid cash generation that comfortably services this debt stack.
Avolta's narrative projects CHF 15.2b revenue and CHF 322.1m earnings by 2029. This implies 2.8% yearly revenue growth and an earnings increase of about 60% from CHF 199.0m today.
Uncover why Avolta's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
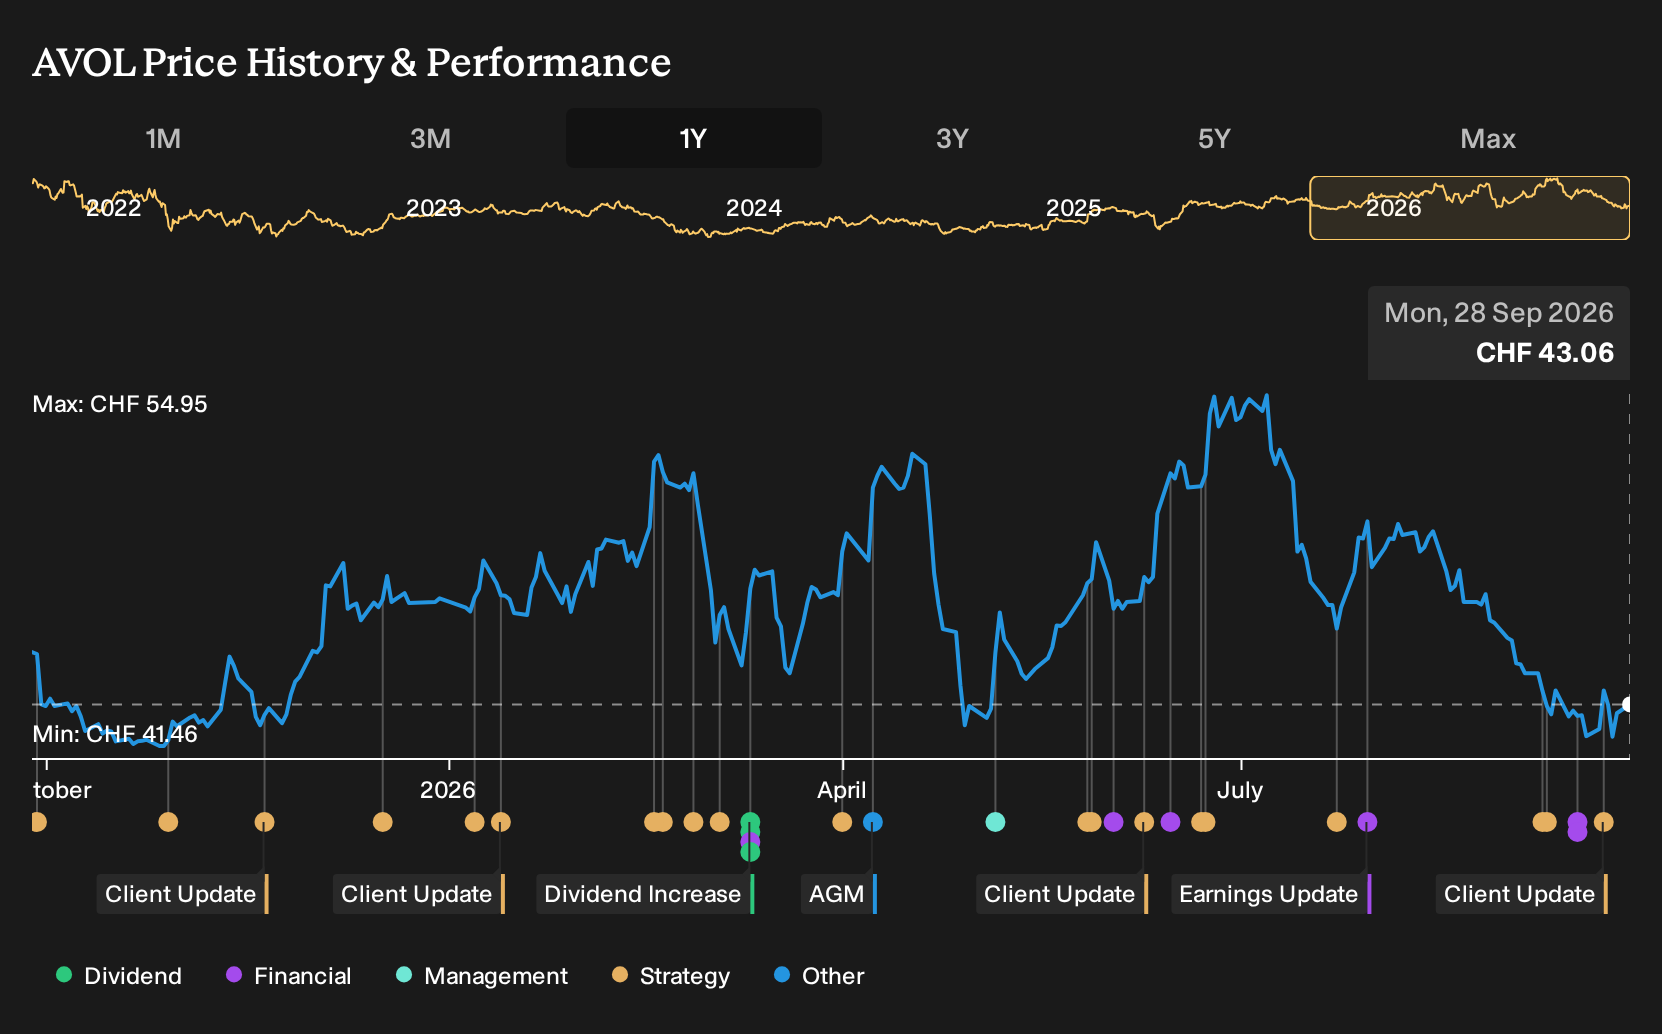
Two fair value views from the Simply Wall St Community span about €39.28 to €51.94, which already shows how far opinions on Avolta can stretch. Set that against risks from geopolitical shocks or concession competition, and you get a wide possible outcome range. Use these contrasting angles to test your own thesis.
Explore another Avolta fair value estimate, including one that suggests as much as 21% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Avolta research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avolta. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avolta's overall financial health at a glance.
Looking For More Investment Ideas Beyond Avolta?
Once you have a view on Avolta, it helps to compare that thesis with other opportunities that share similar qualities or offer very different risk profiles. The Simply Wall St Screener can surface stocks that line up with your preferences on quality, balance sheet strength, income potential or valuation.
- If you want a wider pool of potentially mispriced opportunities with solid fundamentals, scan our 197 high quality undervalued stocks and see which companies deserve a closer look.
- For investors who care most about resilience and capital preservation, shortlist candidates from our 221 resilient stocks with low risk scores to find businesses with steadier profiles.
- If you lean toward stronger financial foundations and cleaner balance sheets, start your search with the list of solid balance sheet and fundamentals (202 results) to spot companies that might better fit a quality first approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com