


- Sensirion Holding recently expanded its air quality portfolio by launching the SEN68 and SEN69C multi-parameter sensor modules and confirming broader distribution of formaldehyde and refrigerant detection solutions through partners such as Mouser Electronics.
- The push into compact, multi-sensor platforms for HVACR, smart buildings, and indoor monitoring highlights Sensirion’s focus on regulation-driven use cases and integration into space-constrained devices.
- We will now look at how Sensirion Holding's investment narrative intersects with its new multi-parameter air quality modules and wider distribution.
Sensirion Holding Investment Narrative Recap
To hold Sensirion Holding, you need to be comfortable with a sensor specialist that leans heavily on regulation driven air quality and HVACR demand and is priced on relatively rich expectations. The key near term catalyst is execution on newer platforms such as multi parameter air quality modules that can offset normalization in A2L refrigerant leakage sensors and soften any cooling in Chinese stimulus supported end markets.
The biggest risk right now is that momentum in industrial and consumer sensing does not replace that earlier one off A2L surge, while currency swings and trade policy changes weigh on reported earnings. The latest product and distribution news helps operational diversification but does not fundamentally change those near term dependencies or macro sensitivities.
The SEN68 and SEN69C launch looks most relevant when thinking about Sensirion Holding and its next phase of growth in environmental sensing. These compact modules extend the SEN6x family by packing up to ten parameters, including particulate matter, VOC, NOx, formaldehyde and CO2 on the SEN69C, into a footprint that fits space constrained air quality devices.
For an investor, that matters because the main operational question is whether new platforms can take over as fresh drivers once A2L refrigerant sensors settle into a steadier run rate. Broader use across indoor air monitors, smart buildings and vape detection can help diversify revenue sources, but adoption speed, pricing, and any slowdown in building and appliance demand still sit as execution and end market risks.
Sensirion Holding's current earnings are CHF 28.6 million and analysts see earnings reaching CHF 42.5 million by 2029, an increase of about CHF 13.9 million. Based on the same consensus view, Sensirion Holding would generate CHF 437.5 million of revenue and CHF 42.5 million of earnings in 2029, which assumes revenue growing at about 9.1% a year over the next few years.
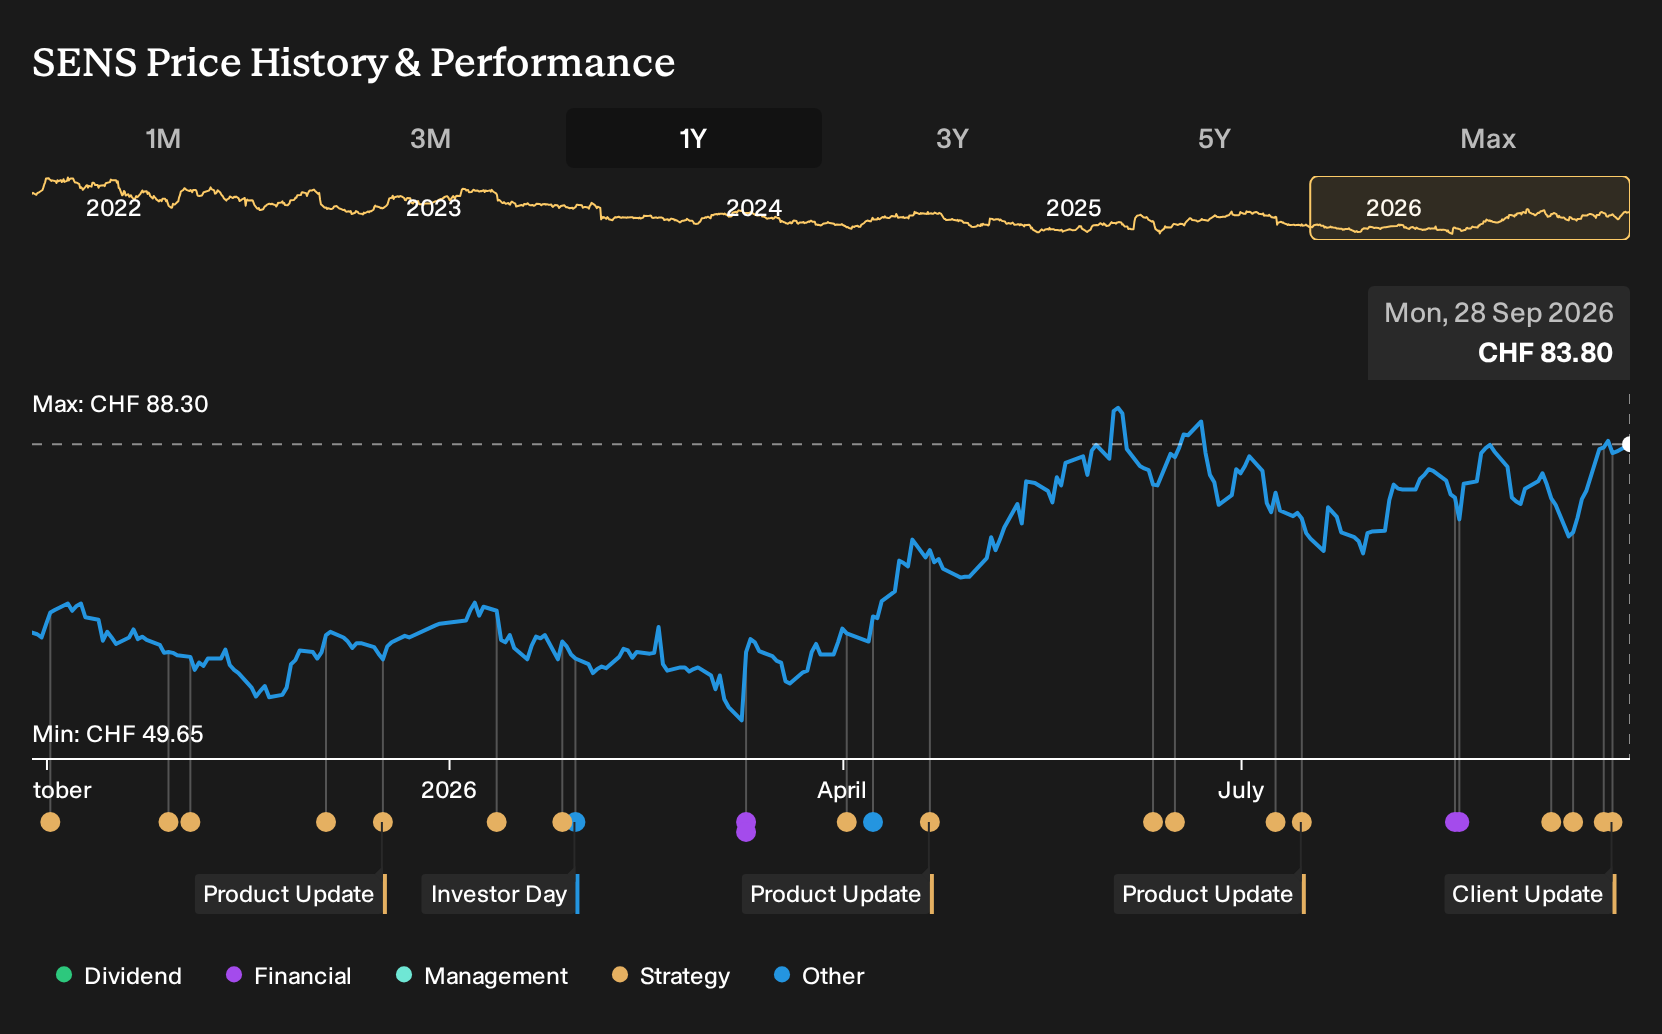
Uncover why Sensirion Holding's fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community cluster between CHF 77.80 and CHF 89, with some contributors implying limited upside while others see the stock priced more aggressively. Those views sit against real risks around currency swings and post stimulus demand, so you are wise to compare several contrasting takes on Sensirion Holding.
Explore 2 other Sensirion Holding fair value estimates, including one that suggests as much as 6% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sensirion Holding research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sensirion Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sensirion Holding's overall financial health at a glance.
Looking for more Sensirion Holding style ideas?
If the Sensirion Holding story has you thinking about where else regulation, balance sheet strength, or underappreciated fundamentals might matter, it can help to cast a wider net with a focused stock screener.
- For investors who want stronger downside protection, start with companies that score well on financial resilience by scanning our 221 resilient stocks with low risk scores.
- If you prefer businesses that already generate cash and look overlooked by the market, check out 618 high quality undiscovered gems, which pairs quality with underfollowed stories.
- Income focused investors who still care about fundamentals can filter for payout strength and balance sheet support using 164 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com