


- Recent commentary highlights Ameriprise Financial as a diversified advice, asset management, and protection provider, with fixed income and annuity offerings that have become more compelling as long term Treasury yields remain at elevated levels.
- An interesting angle is how Ameriprise Financial is using its AI enabled advice platform and planning tools to keep clients engaged with income and protection solutions while markets adjust to higher government bond yields.
- The discussion then turns to how Ameriprise Financial's investment narrative could be reshaped by higher long term Treasury yields, which may make its income products more appealing.
Scan how Ameriprise Financial fits into the higher yield story, then size up other income focused players in our curated 6 dividend fortresses for ideas beyond a single stock.
Ameriprise Financial Investment Narrative Recap
Owning Ameriprise Financial usually means you believe its advice-led model, fee-based wealth business and protection products can keep attracting assets even as higher yields reset client expectations. The key near-term swing factor is whether adviser productivity tools and AI-led planning keep offsetting a tougher recruiting and retention battle and softer net flows in certain channels.
The biggest operational risk right now is further leakage of assets from adviser departures or lost institutional relationships on top of earlier Comerica-related outflows. The latest focus on higher long-term Treasury yields is important context, but it does not materially change that the near term hinges more on asset retention and flow trends than on rates alone.
Recent commentary around Ameriprise Financial has highlighted its embedded AI tools, such as eMeeting, automated summaries and Copilot Premium, as an operational lever. These are already flagged as potential drivers of higher adviser productivity, with management estimating roughly 30 hours a week of possible time savings that can be redirected into client work and prospecting.
That same AI-enabled platform sits at the center of today’s higher-yield environment. It gives advisers structured ways to discuss fixed income, annuities and protection products when clients are rethinking risk and income. Execution risk remains around keeping flows positive while institutional asset management still faces outflows, but the combination of technology and advice is a core catalyst to watch.
Ameriprise Financial’s current earnings of $3.9b sit against analyst projections of $4.8b by 2029, implying an increase of about $0.9b. Those same forecasts point to revenue of $22.9b by 2029, based on an assumed 4.8% yearly revenue growth rate.
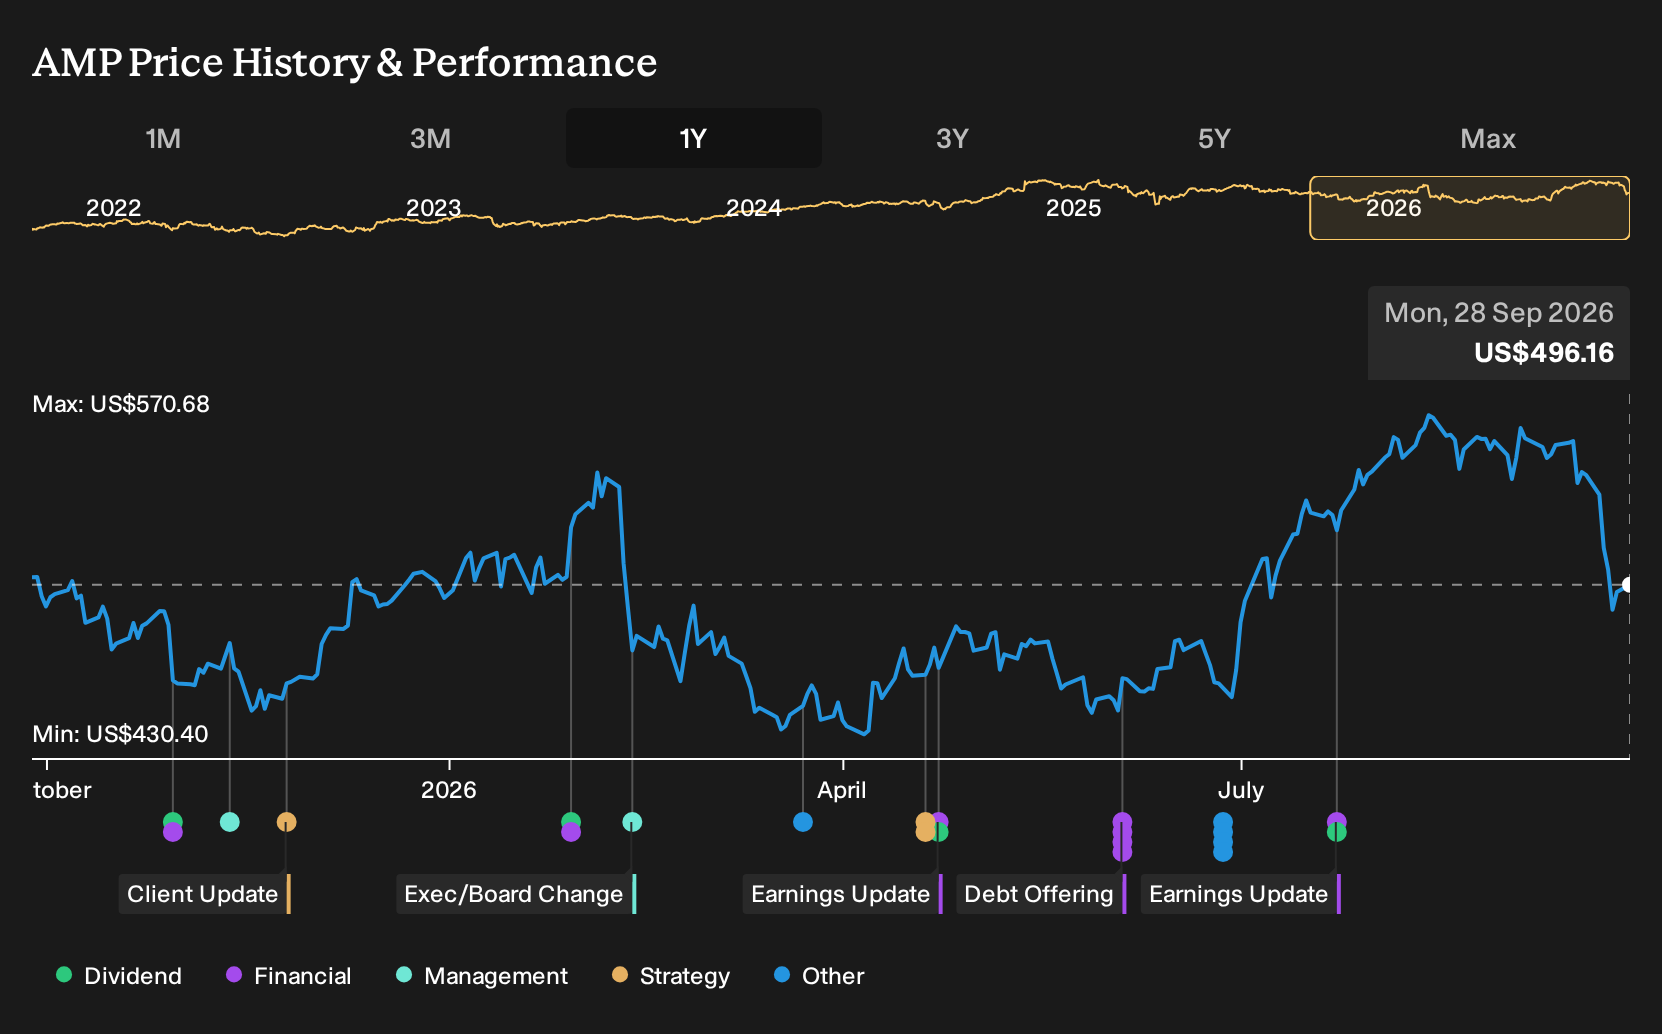
Discover why Ameriprise Financial's fair value indicates a 17% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on Ameriprise Financial puts more weight on regulatory and high rate risks. Those analysts worry that interest sensitive products could see choppier profitability, even though they were still projecting about US$21.5b in revenue and US$4.6b in earnings by 2029. Treat that as one more lens, and compare it with other viewpoints before reacting to the latest news.
Explore 2 other Ameriprise Financial fair value estimates, including one that suggests there could be as much as 70% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ameriprise Financial research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ameriprise Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ameriprise Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ameriprise Financial?
After you have formed a view on Ameriprise Financial, it can help to compare it with other businesses that share some of the same income, quality or risk characteristics. The Simply Wall St Screener lets you filter for traits that match your own preferences rather than relying on a single story.
- If you want income that aims to balance yield with resilience, start with a curated group of 6 dividend fortresses that focus on dependable payouts.
- If value is your priority, scan a focused universe of 32 high quality undervalued stocks where fundamentals and pricing are put side by side.
- If balance sheet strength matters most to you, filter for companies in the list of solid balance sheet and fundamentals (25 results) to find businesses with financial cushions that may handle stress better.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com