


- Castle Biosciences recently reported new clinical data showing its TissueCypher Barrett's Esophagus test led physicians to change management plans in 90% of modeled cases, aligning care more closely with each patient's progression risk.
- In the same period, Castle Biosciences also reported new evidence for its AdvanceAD-Tx atopic dermatitis test and opened a new Scottsdale lab, indicating heavier investment in precision diagnostics infrastructure and broader test-menu execution.
- The next area of focus is how these additional TissueCypher data points could influence Castle Biosciences' investment narrative related to scale, reimbursement, and test adoption.
Scan beyond Castle Biosciences and size up other precision medicine players by reviewing our hand picked 37 healthcare AI stocks that could benefit as molecular diagnostics gain traction in clinical practice.
Castle Biosciences Investment Narrative Recap
For you to own Castle Biosciences, you need to buy into a simple idea. The business is trying to turn strong clinical evidence in Barrett's esophagus and atopic dermatitis into routine test use across larger patient pools. The short term swing factor remains reimbursement clarity on its key assays, while mix shift into lower margin lines still hangs over profitability.
The new AdvanceAD-Tx and TissueCypher data points strengthen the clinical story but do not on their own resolve payer risk around DecisionDx-SCC or broader coverage. If reimbursement outcomes disappoint or spending keeps running ahead of adoption, operating leverage could stay weak even as reported revenue rises.
The fresh study on AdvanceAD-Tx looks most relevant if you care about Castle Biosciences evolving beyond dermatologic cancer testing. It highlights that 83% of surveyed atopic dermatitis patients and caregivers were interested in molecular tests to guide systemic treatment choices, with even higher interest among those open to new therapies.
Operationally, that kind of stated demand supports the case that AdvanceAD-Tx could become a material growth driver, alongside TissueCypher, if physicians and payers accept it. The main catalysts then sit around real world ordering patterns and coverage decisions, while the key risk is that interest at conferences does not translate into durable, reimbursed test volume.
Castle Biosciences' current analyst setup points to US$443.2 million in revenue and US$27.0 million in earnings by 2029. That profile lines up with a 9.2% yearly revenue growth rate and an earnings swing of about US$39.8 million from a loss of US$12.8 million today.
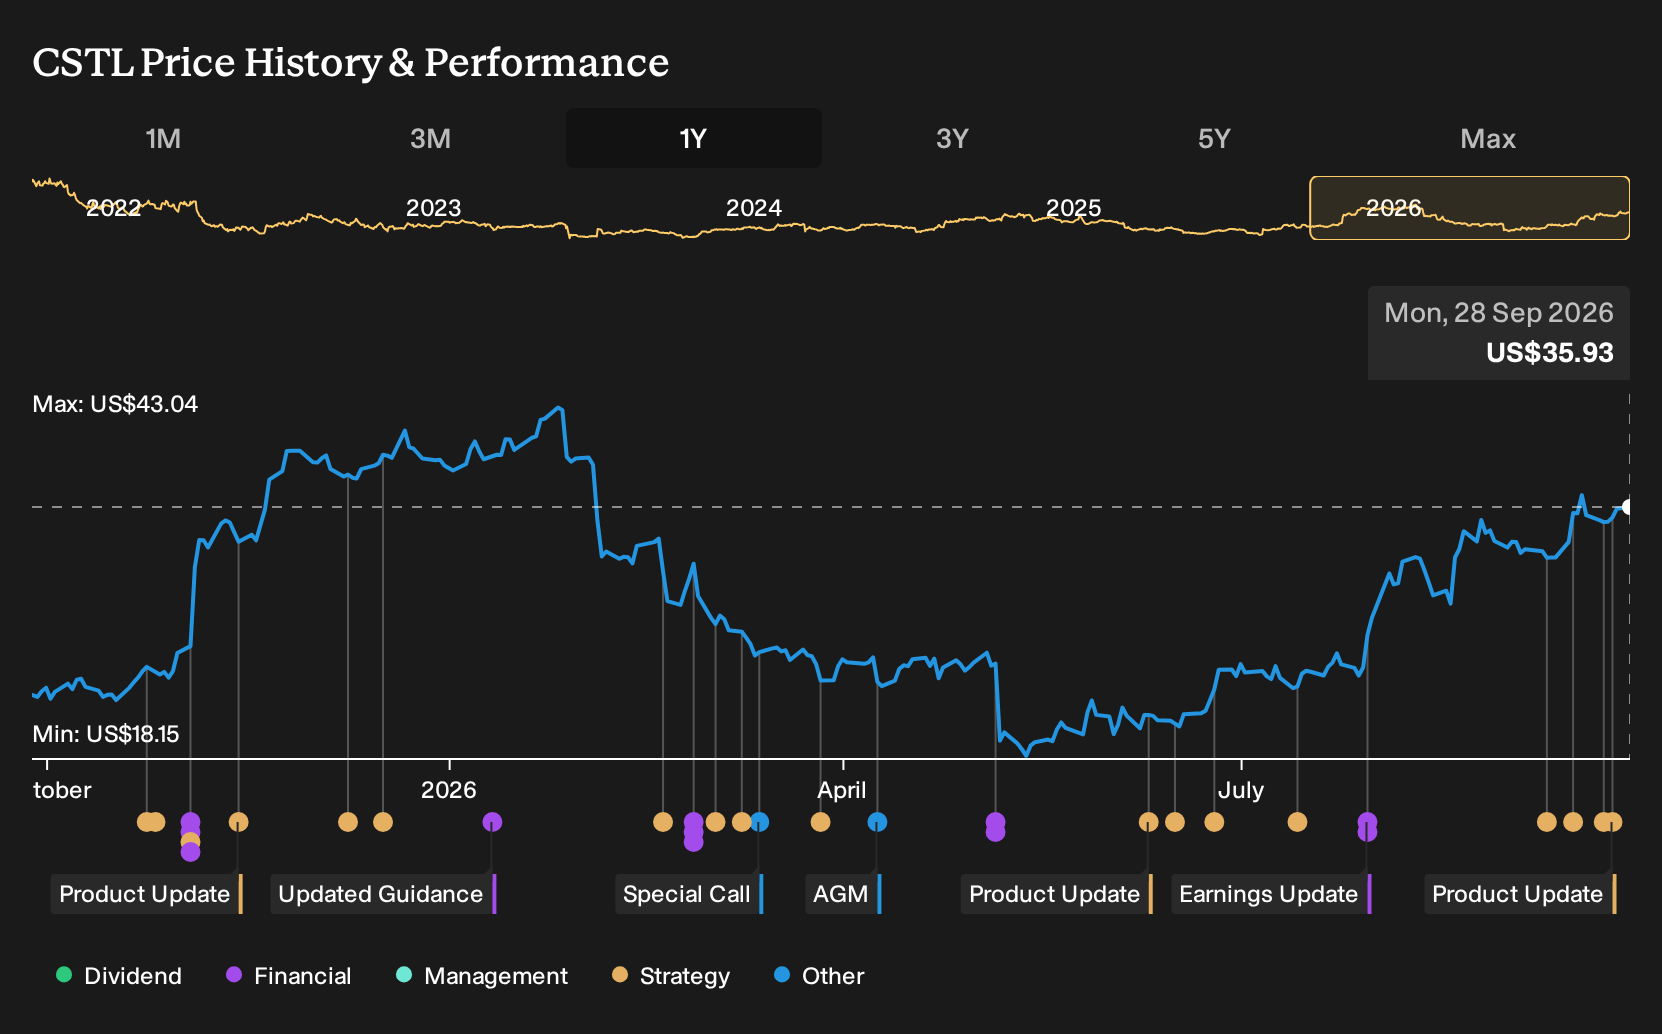
Uncover why Castle Biosciences' fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Castle Biosciences focuses on reimbursement risk around AdvanceAD-Tx. Those analysts were working off slower 7.5% annual revenue growth and earnings of about US$25.8 million by 2029. That view is more cautious than the baseline. It illustrates how far opinions can differ and why it helps to compare several narratives after news like this.
Explore 2 other Castle Biosciences fair value estimates, including one that suggests it could be worth just $44.00!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Castle Biosciences research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Castle Biosciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Castle Biosciences' overall financial health at a glance.
Looking For More Ideas Beyond Castle Biosciences?
If the Castle Biosciences story has sharpened your interest in healthcare and diagnostics, it can help to widen the lens and compare it with other opportunities that match your risk tolerance and income goals. The Simply Wall St Screener gives you a structured way to do that without getting lost in tickers.
- For investors hunting for deep value with quality fundamentals, review our 32 high quality undervalued stocks that already clear strict balance sheet and cash flow tests.
- If capital preservation matters most to you, start with a 30 resilient stocks with low risk scores that filters for resilient businesses with lower risk scores.
- Income focused readers who want steady cash returns can scan a 6 dividend fortresses that currently yield 5% or more.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com