


Innovent Biologics (SEHK:1801) just secured China NMPA approval for Jaypirca as a monotherapy across all chronic lymphocytic leukemia and small lymphocytic lymphoma treatment lines, giving investors a fresh, data-backed regulatory catalyst to assess.
Even with the NMPA decision on Jaypirca, Innovent Biologics’ 1-day share price return fell 3.56% and the 7-day move is down 6.10%. However, the 90-day share price return of 20.79% and 3-year total shareholder return of 151.37% point to momentum that has been building over a longer horizon.
Scan beyond Innovent Biologics and see how other healthcare names with fresh catalysts are lining up in our curated list of 134 healthcare AI stocks.
Innovent Biologics just picked up a major approval while the share price stepped back in the short term. Is this the moment to lean in, or does patience make more sense once the valuation is laid out next?
Price-to-Earnings of 116.2x: Is it justified?
On standard P/E maths, Innovent Biologics looks expensive, with the share price at HK$96.15 translating to a 116.2x earnings multiple that sits well above common benchmarks.
The P/E ratio compares what investors are paying today for each unit of current profit. It is especially closely watched in pharmaceutical and biotech stocks where earnings can be volatile around product launches and R&D cycles.
For Innovent Biologics, a 116.2x P/E places a heavy emphasis on future earnings growth expectations and the quality of cash generation, even though the firm is currently described as having high quality earnings and forecast annual profit growth of 33.5%.
The contrast is sharp when stacked up against the Hong Kong Biotechs industry at 18.5x P/E and a peer average of 25.6x. This means the market is valuing Innovent Biologics at a multiple that is several times higher than both its sector and peer benchmarks and well above an estimated fair P/E of 35x that the market could shift toward over time.
Explore the SWS fair ratio for Innovent Biologics.
Result: Price-to-earnings of 116.2x (OVERVALUED).
Still, the narrative around Innovent Biologics can change quickly if future Jaypirca uptake disappoints or if ongoing R&D spending puts additional pressure on earnings.
Find out about the key risks to this Innovent Biologics narrative.
Another view on Innovent Biologics’ valuation
The story changes when the SWS DCF model is considered. On this view, Innovent Biologics at HK$96.15 trades about 35.6% below an estimated fair value of HK$149.23, which presents the 116.2x P/E as a potential opportunity rather than just a warning sign. Which lens do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
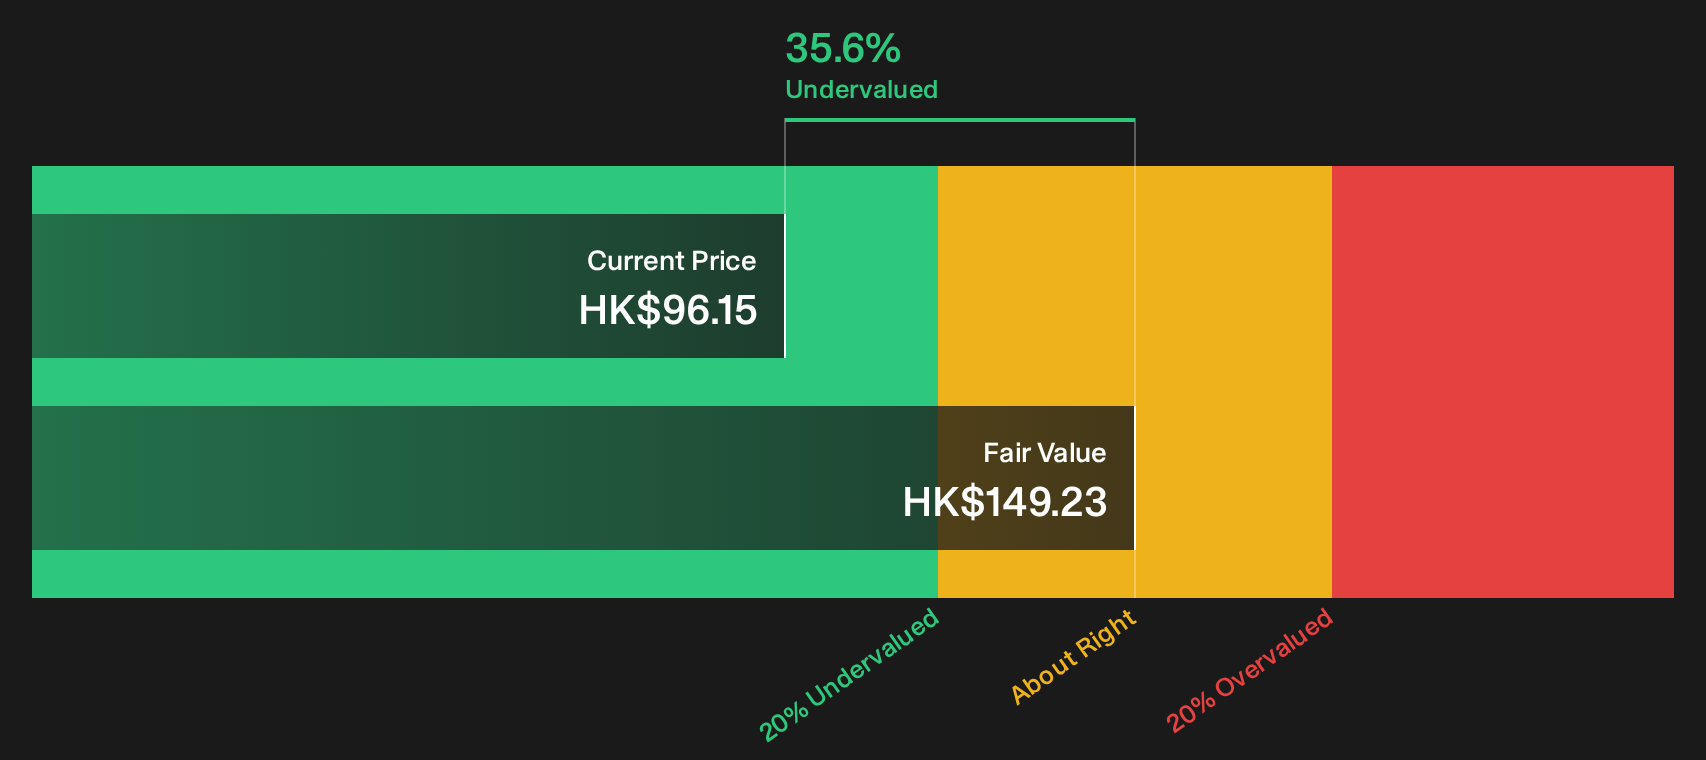
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Innovent Biologics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Innovent Biologics feels familiar, consider acting promptly and testing the data against your own thesis using the 4 key rewards.
Looking for more investment ideas beyond Innovent Biologics?
Do not stop with Innovent Biologics. Cast a wider net so you can compare this story with other opportunities that may fit your style and risk limits.
- Spot potential breakout candidates early by scanning a focused group of 124 elite penny stocks with strong financials that already meet stricter financial quality checks.
- Zero in on value by reviewing a curated set of 196 high quality undervalued stocks that combine stronger balance sheets with healthier cash flows.
- Prioritise resilience by checking a hand picked 221 resilient stocks with low risk scores that may help smooth out portfolio swings when markets get choppy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com