


Rivian Automotive (RIVN) is back in focus after confirming a slot at Evercore's 9th Annual ADAS, AV & AI Forum on September 29, where its autonomy leadership will brief institutional investors.
Rivian Automotive’s recent recall and the focus on its Software and Services gross profit have come against a weaker tape, with the share price down 23.8% year to date and about 14.8% over 90 days, while the 1-year total shareholder return has fallen a milder 3.0%. This points to pressure in the short term but a less severe picture for patient holders.
Scan how Rivian Automotive compares across the electric and software focused peer group by reviewing hand picked 16 high quality undiscovered gems that are also building recurring revenue beyond hardware sales.
Rivian Automotive now trades well below analyst targets after a sharp year-to-date slide, yet the software and services story is only starting to show through the numbers. Has most of the rerating already happened, or is the real upside still ahead?
Most Popular Narrative: 23% Undervalued
The most followed narrative on Rivian Automotive compares a fair value of about $19.23 to the last close at $14.79, framing a stock that the model treats as materially cheaper than its long term assumptions imply. That view leans heavily on what the R2 platform and autonomy partnerships could do to shift the business mix toward higher margin software and services.
Vertical integration in technology, especially in autonomy, battery, and software, combined with growing software & services revenue (including licensing via partnerships like with Volkswagen) is expected to open new high-margin revenue streams and diversify earnings, potentially strengthening EBITDA and net margins over time.
See why 254 investors see Rivian Automotive as 23% undervalued.
Result: Fair Value of $19.23 (UNDERVALUED)
Still, the whole Rivian Automotive narrative can wobble quickly if high cash burn forces fresh equity raises, or if policy changes blunt EV incentives and pressure margins.
Find out about the key risks to this Rivian Automotive narrative.
Another View: Rivian Automotive Looks Expensive On Sales
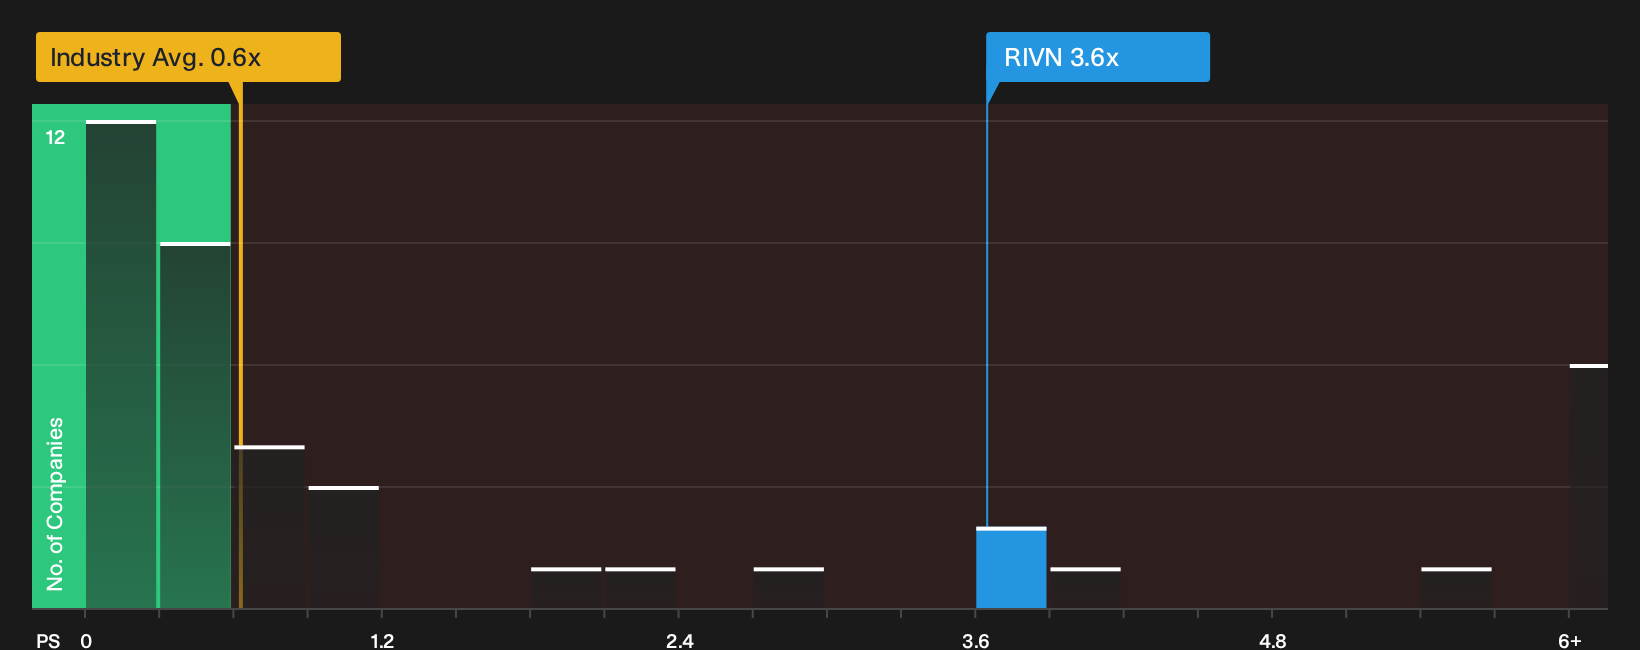
The fair value model paints Rivian Automotive as cheap, yet the market is already paying a rich tag for every dollar of revenue. The stock trades on a P/S of 3.6x, while the US Auto sector sits near 0.6x and close peers average 0.5x.
The fair ratio points to 2.1x as a level the P/S could move toward if sentiment cools. That wide gap suggests valuation risk as much as opportunity, so the real question is whether the software and services story fully justifies such a premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Rivian Automotive so far, right. If you want a clearer stance and to act before sentiment shifts again, weigh both sides of the story through the 3 key rewards and 2 important warning signs.
Looking for more Rivian Automotive sized ideas?
If you want to keep your edge and not leave potential opportunities on the table, let Simply Wall St's screeners surface fresh ideas for your watchlist.
- Target potential bargains with resilient fundamentals by scanning a 32 high quality undervalued stocks that filters for quality alongside pricing pressure.
- Secure more dependable income candidates by running through a curated 6 dividend fortresses focused on higher yielding companies with staying power.
- Dial down portfolio stress by reviewing a 30 resilient stocks with low risk scores tuned to highlight businesses with more durable risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com