


Why Qualcomm’s renewed Apple deal matters now
QUALCOMM (QCOM) just locked in a renewed global patent license agreement with Apple, effective April 1, 2027. This removes a major question mark around a core licensing customer relationship.
The extension gives investors a clearer line of sight on Qualcomm’s royalty stream tied to Apple devices. It also arrives as the chip designer pushes harder into AI, automotive, and robotics through its Snapdragon Summit announcements and the PickNik Robotics acquisition.
QUALCOMM’s renewed Apple agreement lands after a sharp pullback, with the share price down 7.17% over the past day and 3.48% over the week. This comes even though the 30-day share price return is 14.18% and the 1-year total shareholder return is 15.78%, supported by multi-year gains as the business leans into AI, automotive, data centers, and recent moves like the PickNik Robotics deal.
Scan other chip and AI suppliers that could benefit from similar long-term deals by checking our curated list of 84 AI infrastructure stocks today.
QUALCOMM now pairs a fresh Apple license with a sharp pullback in the share price. Investors may consider whether that combination supports buying after the drop or waiting for a more generous entry as the valuation case unfolds next.
Most Popular Narrative: 3% Undervalued
Against a last close of $187.48, the most followed QUALCOMM valuation view points to a fair value of $194.13, with that gap hinging on execution outside smartphones and new AI centric compute deals.
Execution on the AWS custom silicon and optical connectivity agreement, which could total up to US$60b of product purchases over ten years and is expected to start contributing from the December 2026 quarter, would support Qualcomm’s new data center revenue goals of US$5b in fiscal 2027 and US$15b in fiscal 2029 and could become a key driver of long term revenue growth. Scaling of Qualcomm’s High Bandwidth Compute architecture in data center AI workloads, supported by claimed step changes in bandwidth and capacity per watt and early interest from memory vendors and hyperscalers, has the potential to support the company’s target of more than 5% share of a roughly US$1t AI data center market and to influence QCT revenue and gross margin over the coming years.
See why 620 investors see QUALCOMM as 3% undervalued.
Result: Fair Value of $194.13 (UNDERVALUED)
Still, Qualcomm’s reliance on handsets and the risk that in-house chips at major customers could eat into Android and Apple related volumes may quickly challenge this upbeat narrative.
Find out about the key risks to this QUALCOMM narrative.
Another View: QUALCOMM Through a Cash Flow Lens
The analyst consensus tags QUALCOMM as modestly undervalued, yet Simply Wall St’s DCF model tells a different story. On that framework, QCOM at $187.48 screens above an estimated future cash flow value of $172.22, which implies investors are already paying a premium. That raises a simple question: Is the analyst fair value or the cash flow view closer to how you see this business?
Our DCF model is only as strong as the assumptions fed into it, so it is worth understanding how the method works before leaning on it in your own process. Look into how the SWS DCF model arrives at its fair value.
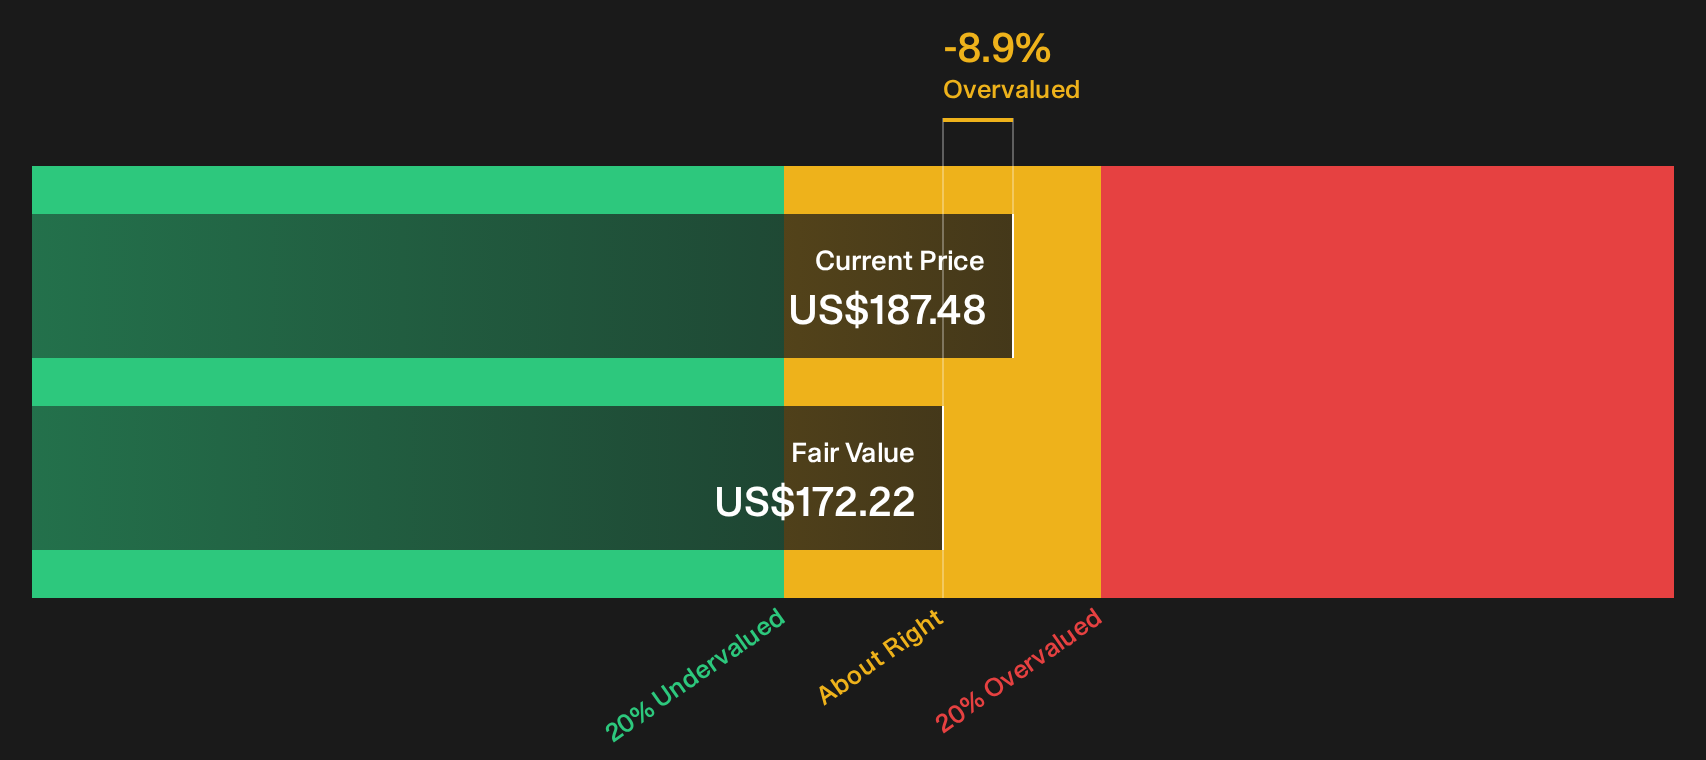
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out QUALCOMM for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on QUALCOMM so far. If you want to move quickly and base your stance on the underlying data, start by weighing the trade off between the 3 key rewards and 1 important warning sign.
Looking for more QUALCOMM sized investment ideas?
If QUALCOMM has you thinking harder about where to put fresh capital, do not stop at one opportunity. Use data backed shortlists to keep your watchlist sharp.
- Target resilient performers by scanning a 30 resilient stocks with low risk scores that prioritises stability when markets turn choppy.
- Hunt for potential bargains through a 32 high quality undervalued stocks that filters for strong fundamentals priced below intrinsic estimates.
- Spot future standouts early with a 16 high quality undiscovered gems focused on quality companies that many investors are still overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com