


Veeva Systems (VEEV) just expanded its AI toolkit with Veeva Study Builder Agent and Falcon Router, fresh offerings aimed at automating clinical data setup and safety triage for life sciences clients.
Recent product launches and new deals with Oxford Biomedica and Amgen sit alongside a sharp shift in sentiment toward Veeva Systems, with the share price gaining 57.75% over 90 days and a 3 year total shareholder return of 39.16%, even though the 1 year total shareholder return remains down 4.45%.
Spot 37 healthcare AI stocks that, like Veeva Systems, are using AI to reshape how healthcare and life sciences handle data, workflows, and compliance.After a 58% climb in 90 days and a mixed return record over 1 and 5 years, Veeva Systems now forces a simple choice: pay up today, or wait and risk the AI momentum running ahead without you.
Most Popular Narrative: 26.9% Undervalued
At a last close of $279.96, the most followed narrative on Veeva Systems pegs fair value closer to $383.14. This frames recent AI enthusiasm as only partially reflected in the price rather than fully priced in. That gap is where narrative, switching costs, and the new Falcon tools intersect.
Veeva is not simply another cloud-software company selling productivity tools. It has built deeply embedded software across the life-sciences value chain: clinical trials, regulatory submissions, drug safety, quality, medical affairs, and commercial operations. Its systems sit close to the operational core of pharmaceutical and biotechnology companies.
See why 49 investors see Veeva Systems as 27% undervalued.
According to John_Eric, the appeal of Veeva Systems rests less on eye-catching quarterly headlines and more on the practical cost of being wrong inside regulated workflows. That focus on switching costs and durability underpins the view that the fair value sits above the current share price, even after a sharp 90 day gain of 57.75%.
The same narrative treats Falcon, Veeva Systems' AI platform, as an extra layer rather than the sole pillar of the thesis. AI agents that sit inside existing clinical, safety, and regulatory workflows are framed as an upside option that could deepen customer relationships, not the only reason the stock might warrant a premium.
Investors reading that thesis get a simple checklist to stress test against their own views. The durability of the installed base, the scope to expand products per customer, the ability to keep margins healthy, and the price paid today all matter as much as the excitement around new AI tools.
Result: Fair Value of $383.14 (UNDERVALUED)
Still, Veeva Systems faces real pressure if large pharma clients consolidate software after mergers or if Falcon adoption fails to translate into meaningful, paid usage.
Find out about the key risks to this Veeva Systems narrative.
Another View On Veeva Systems Using P/E
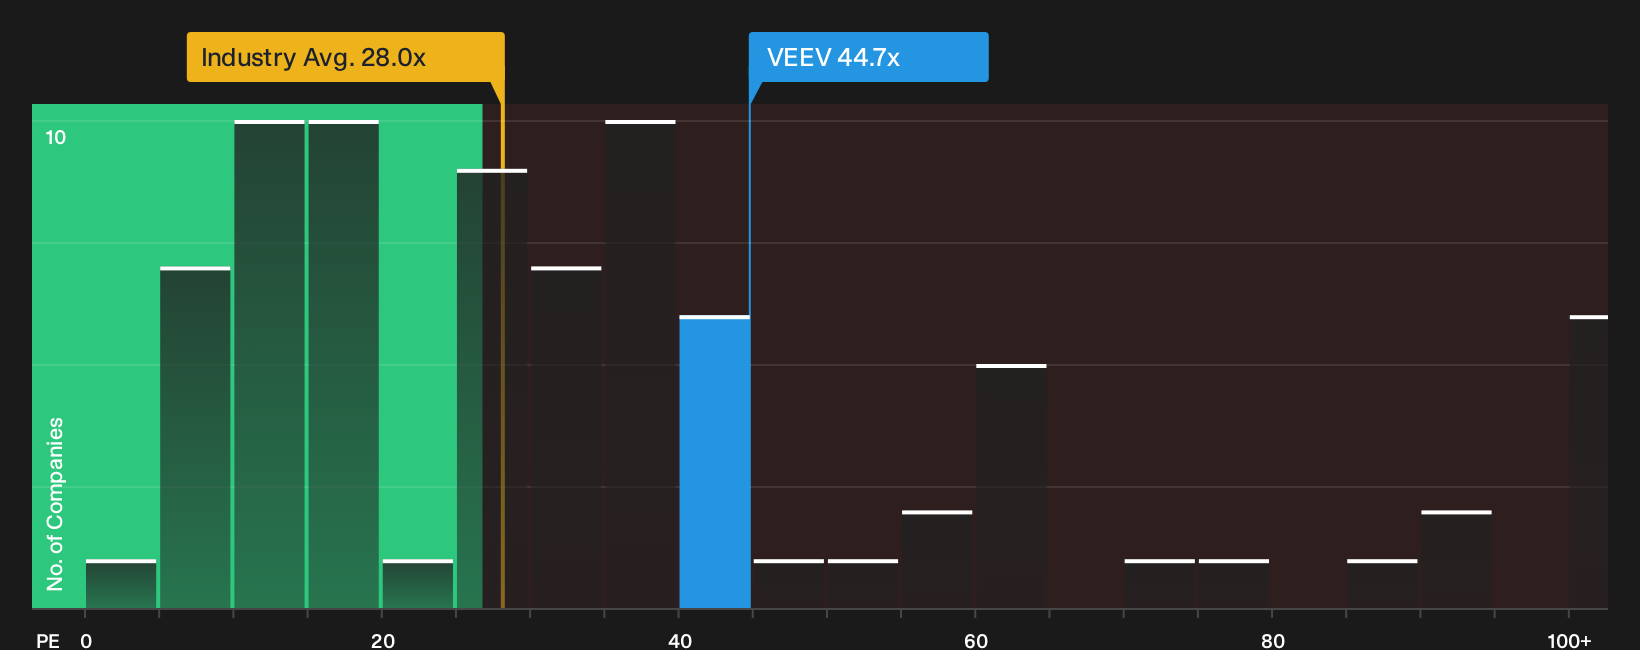
The DCF work points to Veeva Systems trading below fair value, but the P/E picture tells a different story. At 44.7x earnings, the stock trades richer than the Global Healthcare Services average on 28x, its peer group on 44x, and an estimated fair ratio of 33.4x.
That gap means buyers today are accepting valuation risk in exchange for quality and AI upside, rather than getting a clear bargain. The question is simple: How comfortable are you paying a premium multiple when the fair ratio suggests the market could one day settle closer to 33.4x?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of caution and optimism around Veeva Systems feels familiar, treat it as a prompt to inspect the numbers yourself and move quickly before sentiment shifts again. To see what investors are currently excited about in the data, start with the 3 key rewards.
Looking For More Investment Ideas Beyond Veeva Systems?
If Veeva Systems has sharpened your focus on quality, you can use the screener tools to spot other opportunities before they move without you.
- Target potential mispricing by scanning the market for quality companies trading below their estimated worth using 32 high quality undervalued stocks.
- Prioritise resilience by finding businesses with strong finances and low risk profiles with the help of 30 resilient stocks with low risk scores.
- Hunt for underfollowed opportunities by filtering for financially robust prospects that the crowd may have overlooked using 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com