


Oil majors sit in the crosshairs of the latest U.S. Iran talks, where a ceasefire framework, shifting sanctions, and changing Middle East exports could reshape pricing power across global energy markets. This kind of reset can punish some stocks and reward others, often faster than headlines suggest. This article explains those catalysts and highlights 3 integrated giants with direct exposure to these moving parts.
The stocks covered below are just a sample of the larger integrated oil and gas opportunity set, and the wider screen surfaced 92 more companies with equally compelling narratives that are not included in this article. To identify and analyze the highest conviction plays across this universe, head straight into the Global Integrated Oil & Gas Majors screener.
Valero Energy (VLO)
Valero Energy plugs straight into the Global Integrated Oil & Gas Majors theme through its huge refining footprint, turning crude from multiple regions into everyday fuels while also scaling renewable diesel and ethanol. That mix puts future product yields and cash generation squarely in focus.
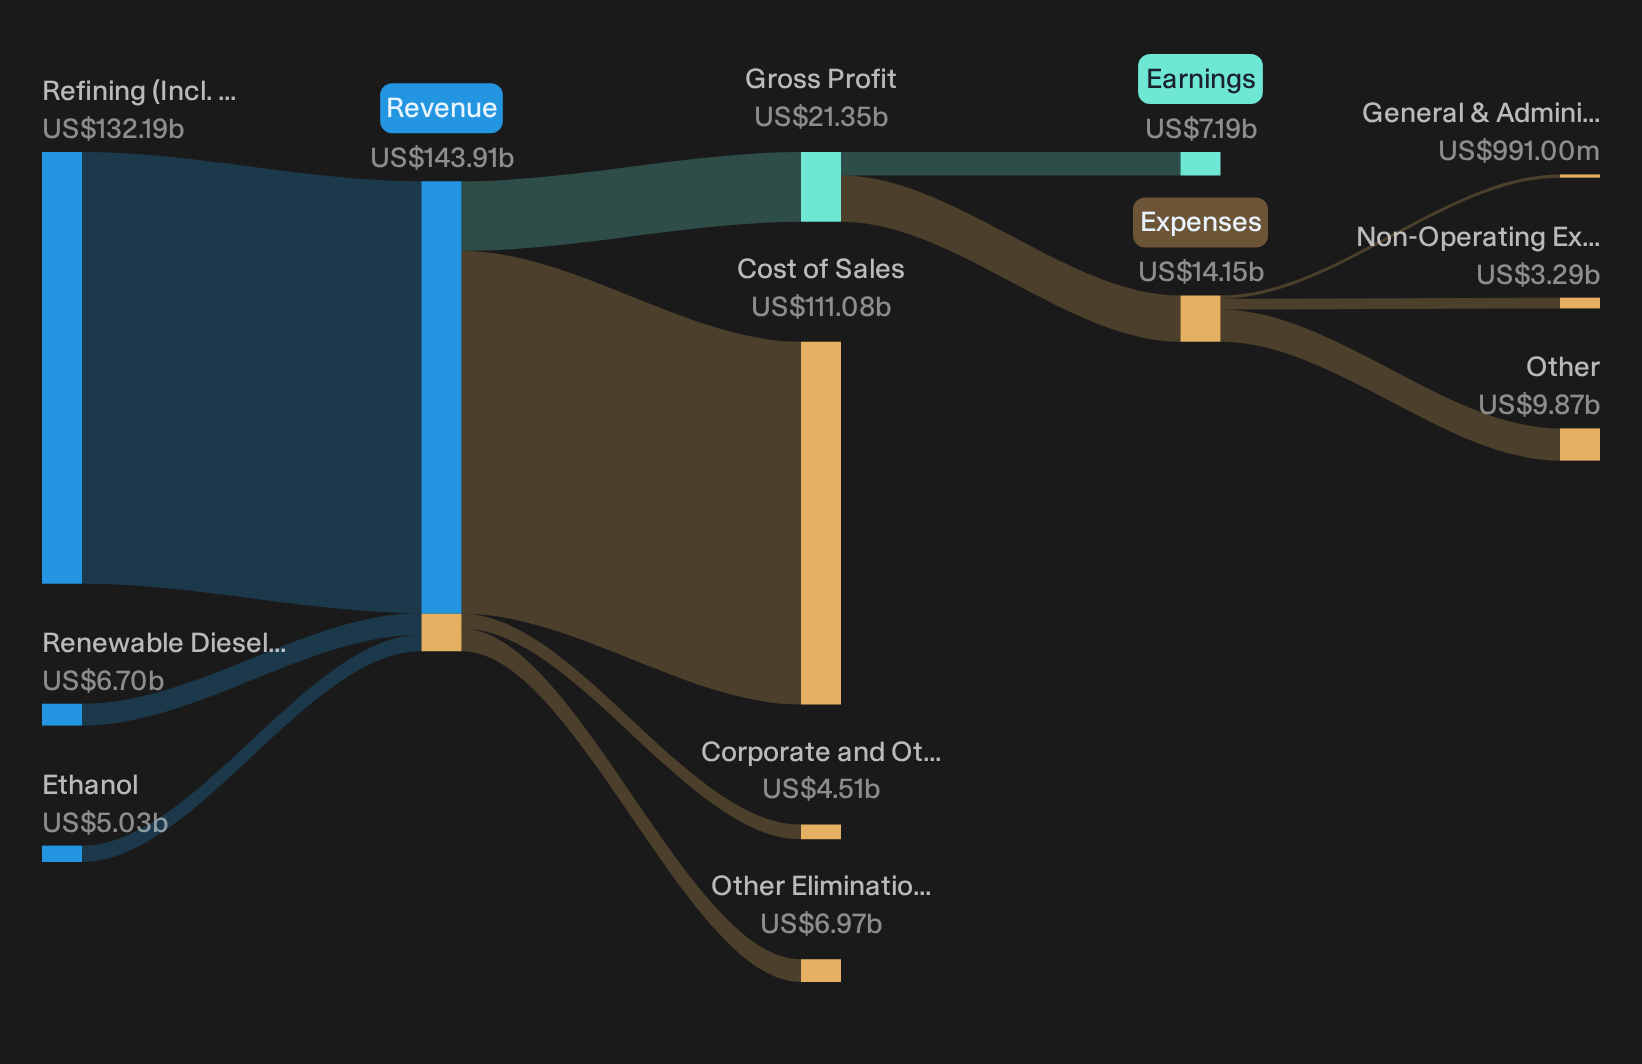
Valero Energy runs refineries and renewable fuel plants that convert crude oil and biofeedstocks into gasoline, diesel, jet fuel, petrochemicals, and ethanol across the Americas and Europe, with about US$132.2b of revenue from refining, US$6.7b from renewable diesel, and US$5.0b from ethanol, and a roughly US$111.5b market cap.
"The SEC unit optimization project at St. Charles, expected to start up in 2026, is projected to increase the yield of high-value products, potentially boosting future revenues and earnings."
What really matters is how one underappreciated shift in refined product balances and policy could reshape Valero Energy’s margin profile.
That margin story is only partly visible in the quote. Read the full narrative for Valero Energy to see how policy shifts, product mix, and capital plans could reshape Valero Energy’s earnings profile.
TotalEnergies (ENXTPA:TTE)
TotalEnergies is one of the clearest fits for the Global Integrated Oil & Gas Majors theme, blending large-scale oil and gas with a growing power arm. The quote below captures how that mix could matter for investors watching shifting energy demand.
"The company's ongoing expansion in gas and power, including LNG projects in the U.S., Canada, Qatar, and Malaysia as well as its strong position in signing flexible, long-term LNG contracts, positions TotalEnergies to benefit from the global shift toward cleaner energy and the sustained robust demand for natural gas, supporting future top-line revenue growth and margin stability."
What happens if one unseen pressure on that balance between traditional fuels and new energy tilts margins just a little further in its favor?
TotalEnergies SE is a multi energy giant in the Global Integrated Oil & Gas Majors universe, spanning exploration, LNG, power, refining and fuel marketing. Most of its roughly $279.9b in revenue comes from Refining & Chemicals at about $128.3b and Marketing & Services at about $68.3b, and it has a market value near €177.8b.
When that fuel and power mix starts to quietly tilt, the full narrative for TotalEnergies shows where TotalEnergies might be accelerating, decoupling risk and sharpening cash generation potential.

Saudi Arabian Oil (SASE:2222)
Saudi Arabian Oil ties directly into the Global Integrated Oil & Gas Majors theme as a large upstream and downstream supplier. Any move toward Middle East export normalization or changing risk premia can quickly feed through its wells, refineries, and cash flows.
"The biggest loophole in the figures lies in the fact that while net profits jumped by 25.56%, Operating Cash Flow (OCF) growth contracted by -3.08%, indicating that profits are booked but not fully collected in cash as Working Capital absorbs liquidity."
Investors may focus on what happens to Saudi Arabian Oil’s margins and resilience if a relatively quiet pressure on physical crude flows and inventory rebuilding changes direction.
Saudi Arabian Oil is a large integrated energy and chemicals producer under the Global Integrated Oil & Gas Majors theme, with roughly SAR1.09t from Upstream and SAR1.11t from Downstream operations, and a market value near SAR6,192.8b.
When those cash and flow pressures start to pull apart, the full narrative for Saudi Arabian Oil shows where Saudi Arabian Oil’s earnings engine may be accelerating and what risks might still be quietly masking it.

Seeking Alternatives Before Momentum Flies Past?
Fresh ideas move first. Momentum builds, prices shift, and the cleanest entries rarely stay under the radar for long. Scan these curated lists before the crowd arrives and position yourself earlier in the trend.
- Hunt for smaller players with balance sheet strength and earnings power through a curated 32 high quality undervalued stocks while they are still being priced like afterthoughts.
- Track structural demand in future-focused infrastructure using the curated 39 power grid technology and infrastructure stocks before capital flows reprice the strongest operators.
- Identify high-yield opportunities that still look resilient with the hand picked 6 dividend fortresses while payout strength and coverage remain overlooked.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com