


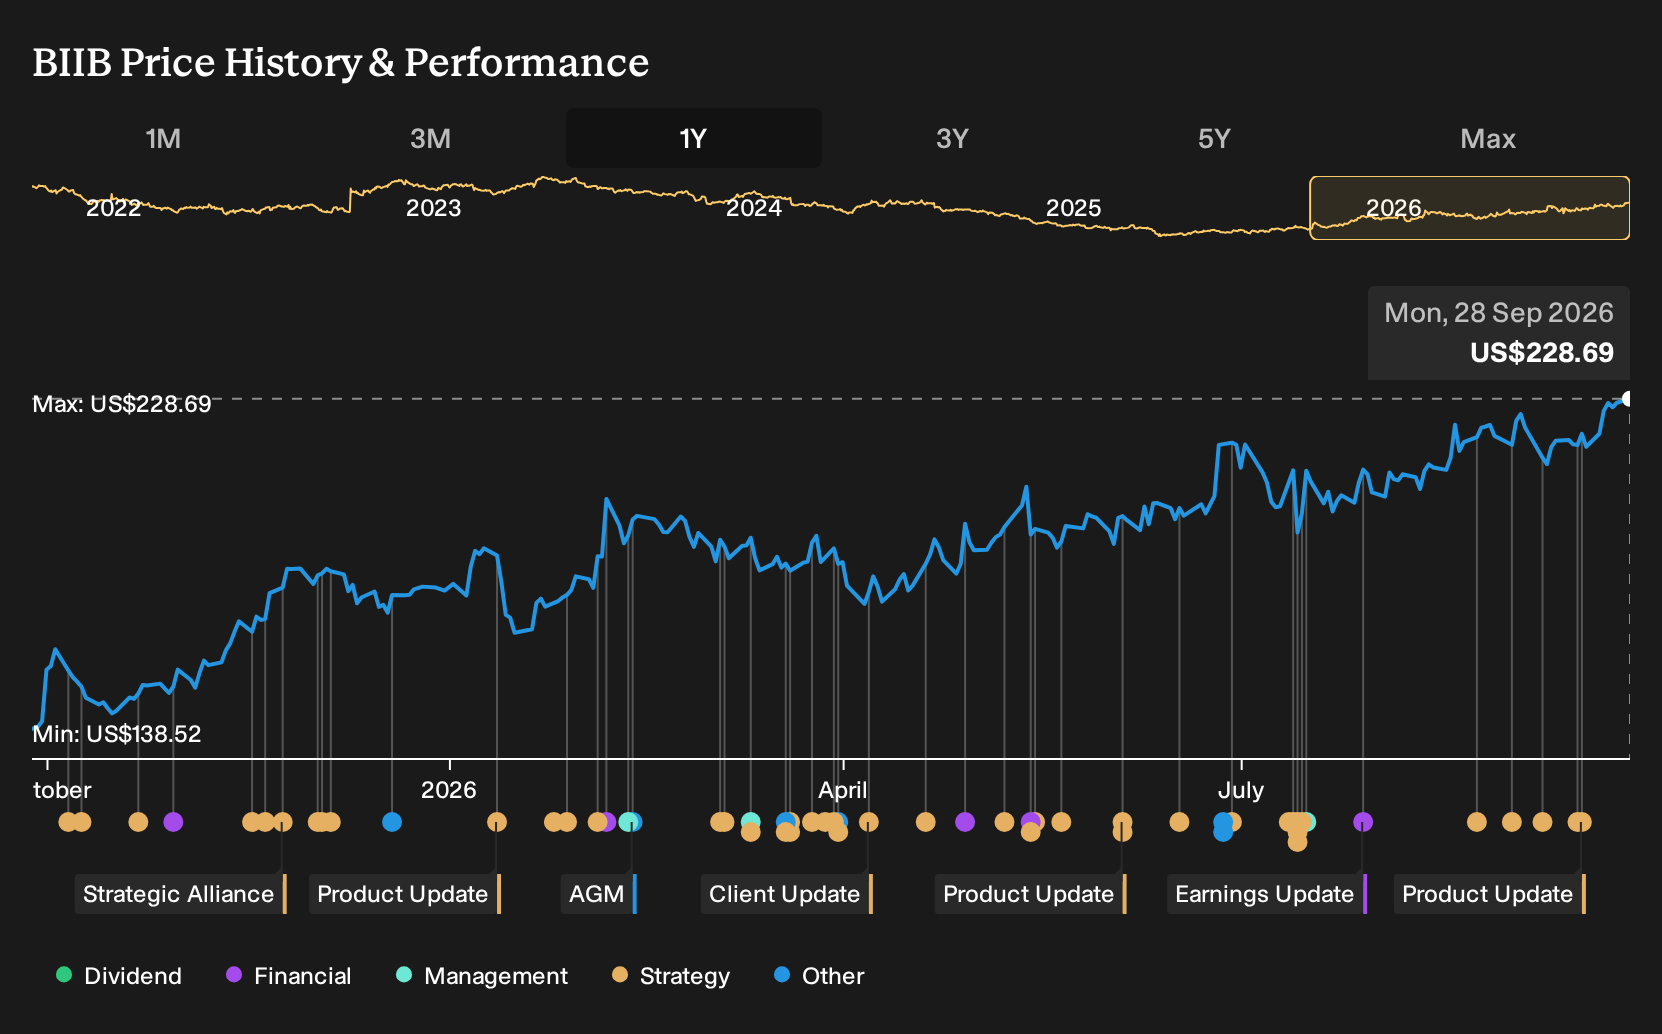
- Biogen reported two product updates: positive adolescent subgroup results from the Phase 3 VALIANT trial of EMPAVELI in rare kidney diseases and Japanese approval of LEQEMBI Pen, a subcutaneous at-home formulation for early Alzheimer’s treatment.
- The combination of expanded adolescent efficacy data for EMPAVELI and a more convenient, at-home LEQEMBI delivery option directly ties Biogen’s pipeline to real-world treatment access, safety management, and potential uptake across both rare renal and Alzheimer’s markets.
- We will now look at how Biogen’s investment narrative could be influenced by LEQEMBI Pen’s at home Alzheimer’s administration option.
Scan Biogen’s news alongside a curated set of other healthcare names targeting hard-to-treat conditions using the 37 healthcare AI stocks for potential next-wave treatment breakthroughs.
Biogen Investment Narrative Recap
To own Biogen, you need to believe the firm can shift its center of gravity from a pressured multiple sclerosis franchise to a broader neurology and rare disease portfolio, with LEQEMBI as a key pillar. The short term focus still sits on clean execution in Alzheimer’s and new launches, while older products face generic creep and pricing pressure.
The latest EMPAVELI and LEQEMBI Pen updates support that therapeutic breadth but do not change the near term swing factor, which remains Alzheimer’s uptake and access. The biggest risk is still that a small group of launches underdelivers against expectations, while cost controls and higher R&D spending compete for the same profit pool.
The LEQEMBI Pen approval in Japan is the clearest operational signal in this news cycle. It gives Biogen and Eisai a second route of administration that can shift some treatment to the home, potentially easing capacity constraints for clinics and aligning better with how patients and caregivers manage early Alzheimer’s in day to day life.
For the Alzheimer’s franchise, at home weekly dosing becomes part of the catalyst story that already leans on broader diagnosis, reimbursement wins, and MRI based ARIA monitoring. It also sits beside Biogen’s efforts in rare kidney disease with EMPAVELI, which diversify away from MS but still concentrate risk in a handful of specialty therapies that must execute commercially and safely under tight REMS style oversight.
Biogen's current analyst narrative points to revenues of US$11.1b and earnings of US$2.3b by 2029. That profile is built on 3.3% yearly top line growth and an earnings increase of about US$1.5b from US$834.6m today.
Uncover why Biogen's fair value indicates a 3% potential upside to its current price before that discount to the market closes.
Exploring Other Perspectives
Some of the most optimistic analysts on Biogen lean hard into the LEQEMBI catalyst. They were already modeling about US$11.8b of revenue and US$3.2b of earnings by 2029 before this at home pen existed. You can see how views can stretch well beyond consensus, so explore a few narratives before deciding your own.
Explore 4 other Biogen fair value estimates, including one that suggests there could be as much as 96% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Biogen research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Biogen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Biogen's overall financial health at a glance.
Looking for more Biogen sized investment ideas?
If you want to cross check Biogen against other potential opportunities, use the Simply Wall St Screener to scan for traits that match your own risk and return preferences.
- For investors who care most about quality at a discount, start with a 32 high quality undervalued stocks that blends solid fundamentals with prices that may not fully reflect them yet.
- If resilience matters more than excitement, focus on a 30 resilient stocks with low risk scores that filters for steadier businesses with lower overall risk scores.
- For those hunting for strong balance sheets and clean financial footing, consider a list of solid balance sheet and fundamentals (25 results) that keeps financial strength front and center.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com