


- YIT Oyj has agreed with XTX Markets to deliver the interior finishing, MEP works, and commissioning of the third data center in Kajaani. This extends its role beyond the already completed shell and core phase, with the contract value remaining undisclosed.
- The Kajaani program now involves YIT delivering three data centers for XTX Markets. This highlights recurring demand for its data center construction capabilities and reinforces the infrastructure side of the business alongside more cyclical housing activity.
- We will now look at how YIT Oyj's investment narrative could be influenced by the extension of its Kajaani data center work.
Compare YIT Oyj's data center exposure with other potential beneficiaries of digital infrastructure demand by scanning our curated list of 84 AI infrastructure stocks.
YIT Oyj Investment Narrative Recap
To own YIT Oyj, you need to believe the company can shift from a weak Finnish housing backdrop and uneven project completions into a steadier mix of residential and infrastructure work. The Kajaani data center extension supports that narrative, but the undisclosed value and long timetable mean it does not change the near term picture on its own.
The more immediate swing factor is still how quickly YIT can improve profitability and reduce financial risk while carrying high net debt and interest costs. Project delays, especially in Residential Finland and CEE, remain a key threat. The new data center phase slightly improves visibility, but does not remove the earnings volatility risk.
The most relevant recent development is the broader Kajaani data center program itself, where YIT is contracted to deliver three facilities for XTX Markets. The latest stage, covering interior works and commissioning of the third unit starting in late 2026, links directly to that wider build out and shows continuity in the relationship.
For shareholders, this matters because it anchors YIT Oyj more firmly in infrastructure and complex construction, which can help offset cyclical Finnish residential exposure. Execution quality, margin discipline and working capital management on this multi year engagement will be important, given uneven completions and already stretched interest coverage.
On current analyst assumptions, YIT Oyj's story points to revenues of €2.4 billion and earnings of €95.2 million by 2029. This implies 11.0% yearly top line growth and an earnings swing of about €170 million from a loss of €75.0 million today to the forecast profit level.
Uncover why YIT Oyj's fair value indicates a 20% potential downside to its current price, which leaves little room for error.
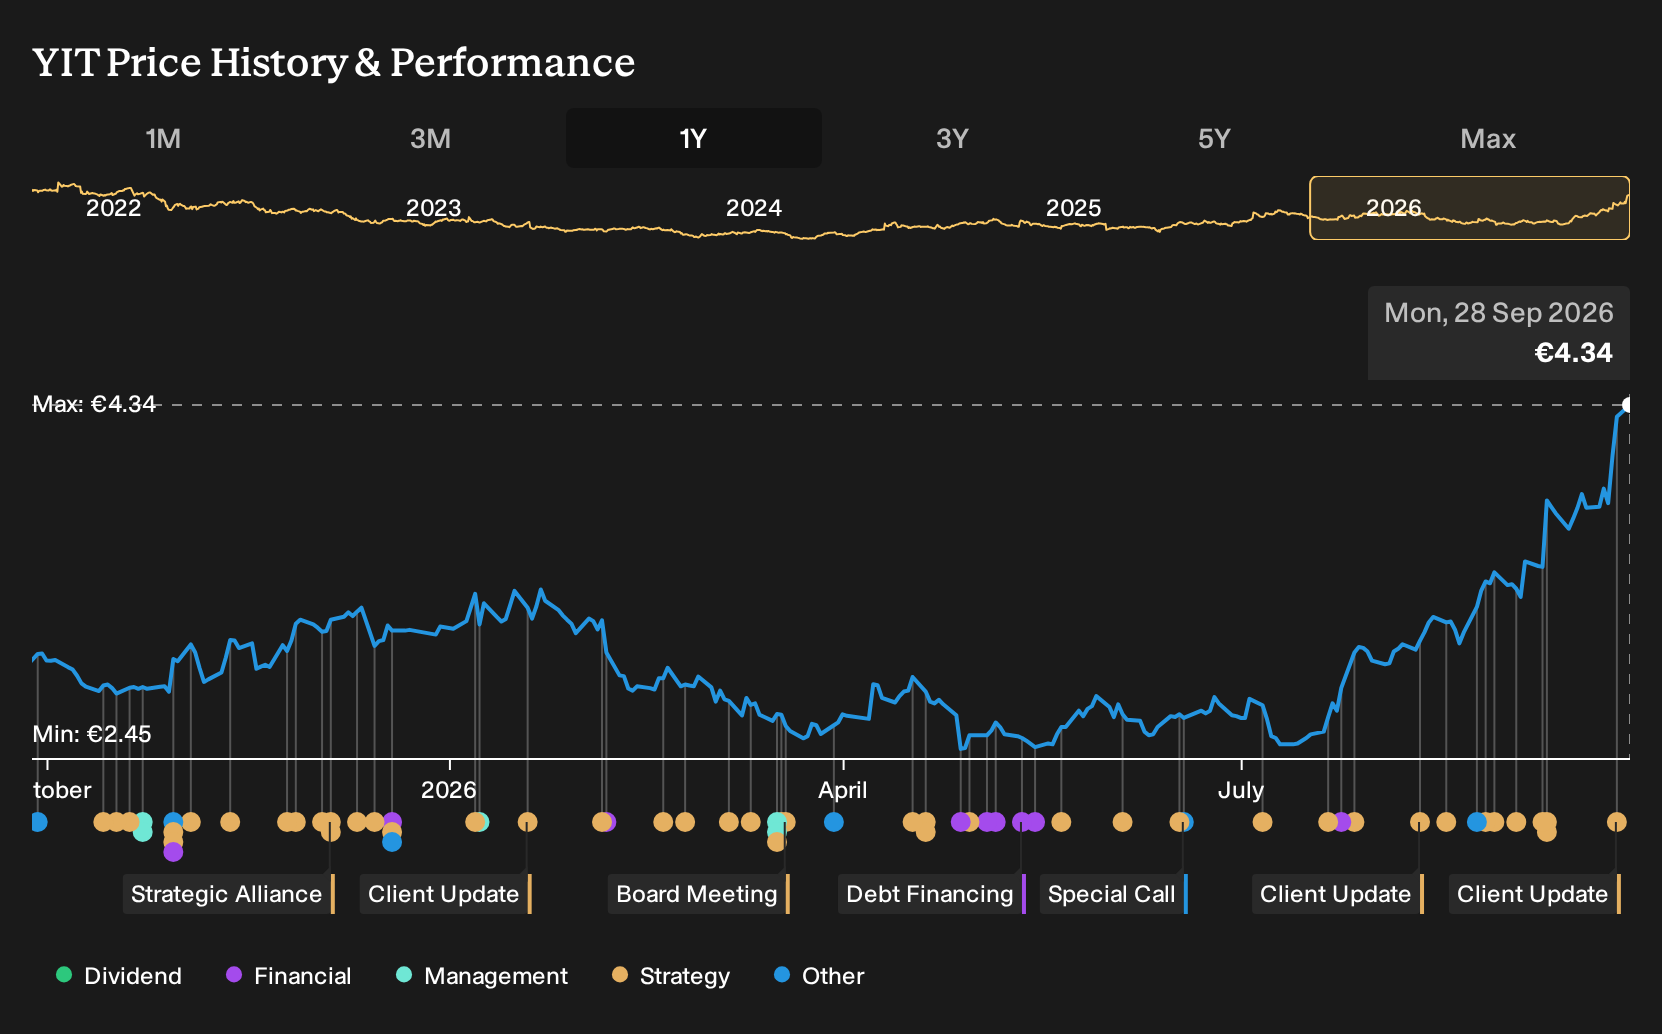
Exploring Other Perspectives
Some of the lowest YIT Oyj forecasts lean hard into data center concentration as the key risk. Those analysts were pencilling in about €2.2b of 2029 revenue and €92.4 million of earnings, which is below consensus. You can treat this new Kajaani phase as a chance to test whether that more cautious story still holds.
Explore another YIT Oyj fair value estimate, including one that suggests as much as 36% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your YIT Oyj research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for YIT Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate YIT Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond YIT Oyj?
If the YIT Oyj story has you thinking about portfolio balance and where to find other opportunities, use that curiosity to widen your search with targeted stock lists built from the same underlying data engine.
- For investors who want potential upside without ignoring quality, scan a curated mix of resilient businesses through 618 high quality undiscovered gems.
- If capital preservation matters just as much as return, focus on companies that score well on stability and risk with the 221 resilient stocks with low risk scores.
- When balance sheet strength is non negotiable, filter for enterprises with healthier funding profiles using the list of solid balance sheet and fundamentals (202 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com