


PORR’s new perpetual bond and why it matters for equity holders
PORR (WBAG:POS) has launched a €150 million fixed to floating rate perpetual bond that is callable, subordinated, convertible and issued under Regulation S. This funding move reshapes the group’s long term capital mix.
PORR’s move into perpetual convertible debt lands at a time when the share price has slipped, with the stock down 26.6% on a 90 day share price basis and 15.6% over 30 days, even though the 1 year total shareholder return is 17.3% and the 3 year total shareholder return is roughly triple.
Compare PORR’s perpetual move with other construction and infrastructure players by scanning our hand picked list of solid balance sheet and fundamentals (202 results), which may offer different risk and reward trade offs.
PORR’s perpetual convertible can be read two ways. Either management is leaning into a business that still supports fresh capital, or sentiment has weakened enough that equity alone no longer does the job. How does that affect valuation now?
Most Popular Narrative: 25.3% Undervalued
On the most followed view, PORR’s fair value of €43.49 sits well above the last close at €32.50. This frames the new perpetual bond against a share price already trading at a sizeable implied discount using an 8.83% discount rate.
Ongoing advancement into high-margin specialties, such as railway construction, tunneling, and data center projects, is expected to structurally improve PORR's EBITDA and net margins as these segments become a larger share of the portfolio and deliver better project economics.
See why 11 investors see PORR as 25% undervalued.
Result: Fair Value of €43.49 (UNDERVALUED)
Still, the PORR story can break if infrastructure projects stall or if persistently low EBIT margins fail to move meaningfully away from today's low base.
Find out about the key risks to this PORR narrative.
Another angle on PORR’s valuation
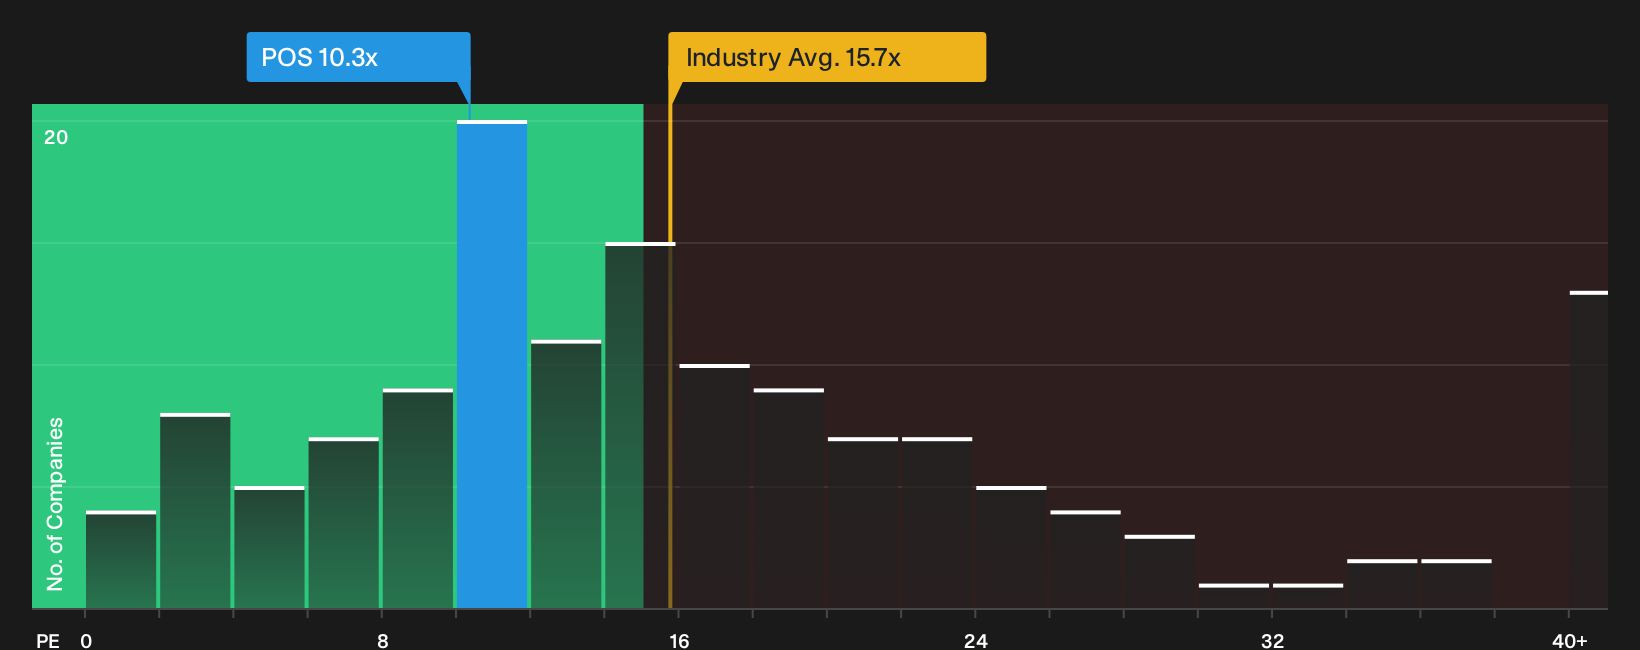
While the headline view paints PORR as undervalued, the current P/E of 10.3x complicates the picture. It looks cheaper than the European Construction group at 15.5x and below a fair ratio of 12.4x, yet slightly richer than close peers at 9.7x. Is that gap compensation for quality, or a margin of safety risk?
To pressure test that question against hard numbers and see how the P/E could evolve if sentiment or earnings shift, investors can review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The conclusion on PORR’s valuation story still feels unsettled. Act while the new perpetual bond and P/E debate are fresh in mind, and weigh both the potential upside and downside using the 4 key rewards and 3 important warning signs.
Looking for more PORR sized investment ideas?
If PORR has sharpened your focus on valuation and risk, do not stop here. Use focused screeners to spot other opportunities before they move.
- Target higher quality at a discount by scanning the 198 high quality undervalued stocks that combine solid fundamentals with pricing that still leaves room for upside.
- Prioritise resilience in tougher markets by reviewing a 221 resilient stocks with low risk scores that filters for stronger balance sheets and more predictable track records.
- Get ahead of the crowd by tracking a 618 high quality undiscovered gems that highlight financially strong businesses before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com