


- Vornado Realty Trust recently featured senior executives at the BofA NY Global Real Estate Conference and secured an 85,000 square foot, 15 year headquarters lease with On at Penn 1 in Manhattan.
- The long dated On lease at Penn 1 highlights fresh tenant demand for Vornado Realty Trust’s upgraded New York office assets and amenity rich locations.
- The focus now turns to how Vornado Realty Trust’s investment narrative could be reshaped by fresh Penn District leasing momentum.
Scan other office focused landlords that show similar leasing momentum to Vornado Realty Trust by reviewing our curated list of 32 high quality undervalued stocks.
Vornado Realty Trust Investment Narrative Recap
To back Vornado Realty Trust, you need to be comfortable with a New York centric office story that leans heavily on Class A demand and the Penn District build out. The big short term swing factor is still leasing progress at those redeveloped assets and how quickly that filters into occupancy and cash flow rather than one headline deal.
The main risk right now sits on the other side of that equation. Capital spending and interest costs remain heavy, earnings are forecast to fall over the next few years, and interest payments are not well covered by current profits. The recent On lease helps sentiment, but it does not change that funding and earnings quality picture on its own.
The 85,000 square foot, 15 year On headquarters lease at Penn 1 is the cleanest operational data point tied to this story. It supports the idea that high credit tenants are still willing to commit to long leases in Vornado Realty Trust’s upgraded Penn District buildings, which matters if you care about leasing traction more than short term share price moves.
You should still weigh that against the financial backdrop. Vornado Realty Trust reports thin net margins at 0.3%, recent earnings have been influenced by large one off items, and analysts expect earnings to decline on average over the next three years. For catalysts tied to Penn District to really matter, execution on leasing needs to repeat at scale while management keeps funding risk under control.
Vornado Realty Trust's current analyst script points to revenues of $2.1b and earnings of $63.9 million by 2029, based on 4.4% yearly revenue growth and an earnings increase of about $58.1 million from $5.8 million today to that 2029 consensus figure.
Uncover why Vornado Realty Trust's fair value indicates a 19% potential difference from its current price before that discount gap closes.
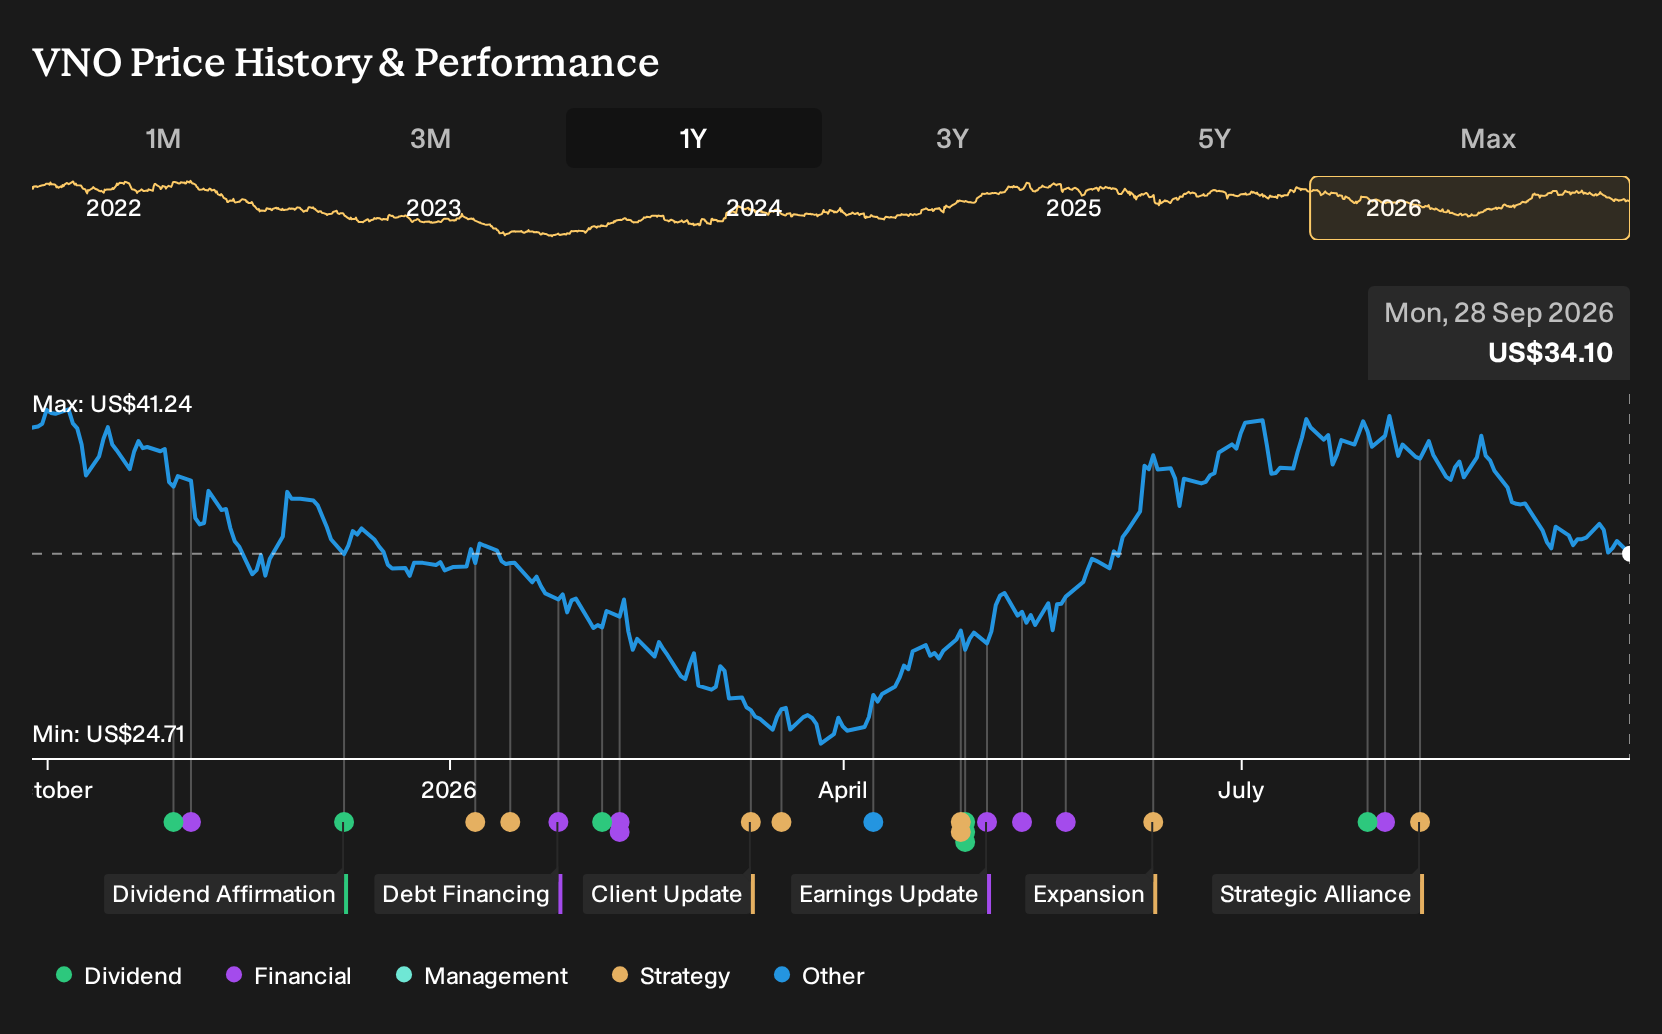
Exploring Other Perspectives
One alternate view leans hard into Penn District leasing as a catalyst. The most optimistic analysts were pencilling in about US$2.4b of revenue and US$21.4 million of earnings by 2029 for Vornado Realty Trust, compared with the baseline US$2.1b and US$63.9 million. That spread shows how widely opinions can differ. Use this lease news as a prompt to explore both narratives and decide which seems closer to your own expectations.
Explore 2 other Vornado Realty Trust fair value estimates, including one that suggests as much as 39% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vornado Realty Trust research is our analysis highlighting 1 key reward and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Vornado Realty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vornado Realty Trust's overall financial health at a glance.
Looking For More Ideas Beyond Vornado Realty Trust?
If the Vornado Realty Trust story has you thinking about where lease momentum, balance sheet strength, or income potential might show up next, it can help to scan a broader watchlist before making any decisions.
- For investors who want potential upside paired with disciplined fundamentals, use our screener focused on 16 high quality undiscovered gems that may not yet be crowded with attention.
- If capital preservation and resilience matter most to you, filter for companies with steadier risk profiles using the screener built around 30 resilient stocks with low risk scores that meet stricter quality checks.
- Income focused readers can zero in on robust payouts by scanning companies that pass yield and balance sheet filters through our list of 6 dividend fortresses that merit a closer look for dividend durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com