


Global markets recently reacted to new regulatory moves and shifting central bank signals, which pushed investors to reassess how much risk they really want to hold. When sentiment wobbles like this, solid Japanese businesses that generate healthy cash can sometimes be marked down too far. That is where a focus on discounted cash flow value comes in. This article highlights three Japan stocks that currently screen as attractively priced on that basis.
The three stocks covered next are only a sample of what screens as discounted on cash generation, with the full process surfacing 39 more companies that carry similarly interesting stories that this article does not touch. To go straight to the source, analyze and identify your own high conviction ideas using the Undervalued Stocks Based On Cash Flows screener.
Canon (TSE:7751)
Overview: Canon is a diversified Japanese manufacturer focused on printers, cameras, medical imaging, and industrial equipment that feed recurring service and consumables demand.
Market Cap: ¥3.90t
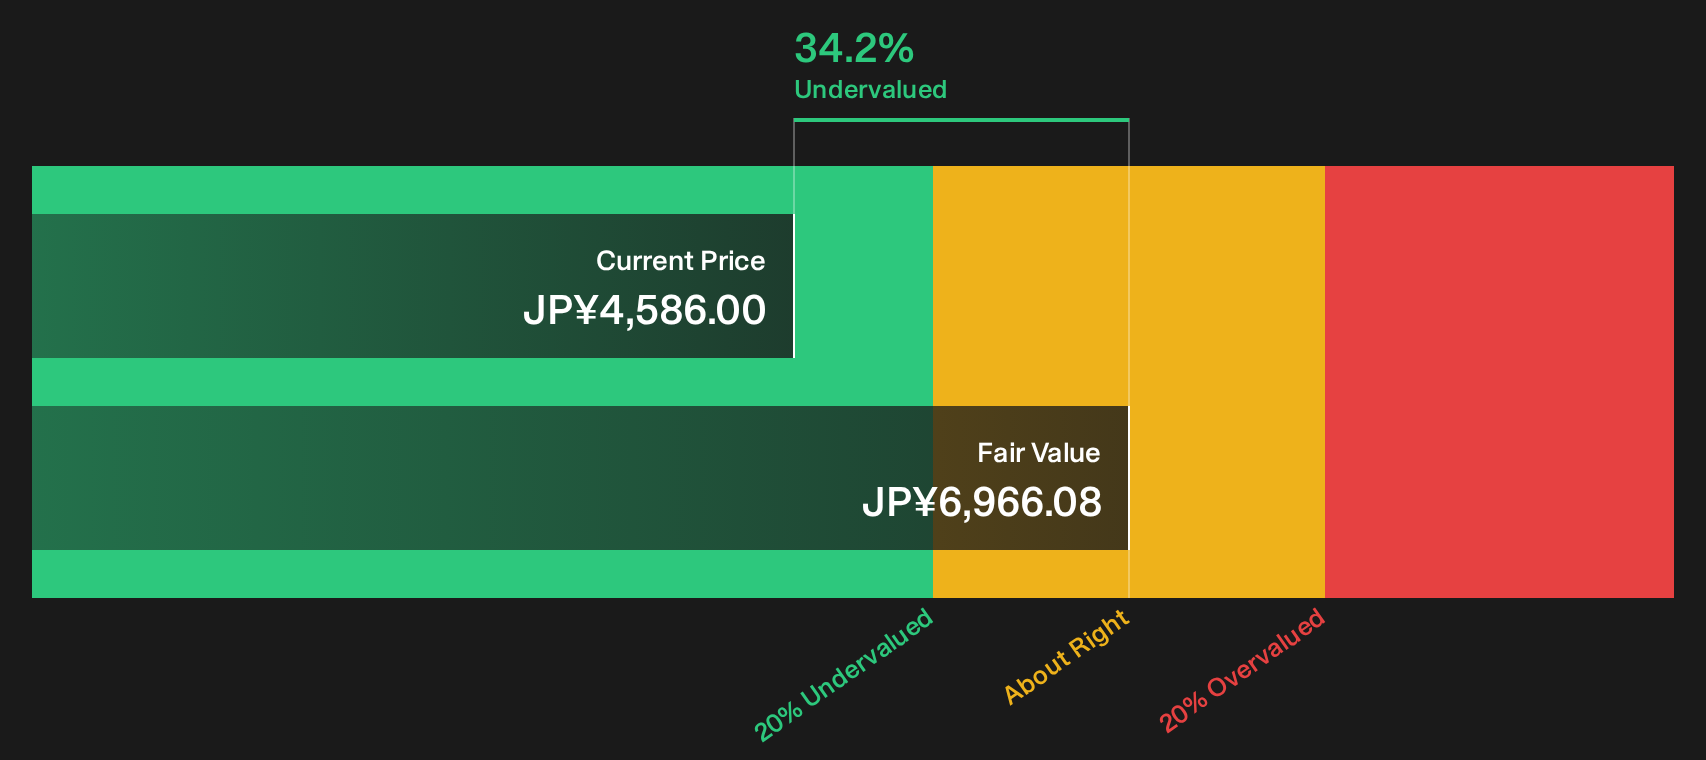
Canon appears interesting for this cash-flow focused screen because the office and production printing ecosystem creates recurring toner, ink, and service income, while the share price currently sits about 34.2% below an estimate of fair value despite very large recent earnings growth. For value-oriented investors, what happens when that dependable print cash stream meets one unseen shift in office and imaging demand will matter a lot.
If that print cash engine has your attention, review the 4 key rewards and 1 important warning sign to see what might be masking or accelerating the potential for Canon’s valuation to reset.
Astellas Pharma (TSE:4503)
Overview: Astellas Pharma develops and sells oncology and specialty medicines such as XTANDI, PADCEV, XOSPATA, and VYLOY that drive branded cash flows.
Operations: Astellas generates about ¥2.27t in pharmaceutical revenue, with sizeable contribution from the USA at roughly ¥1.01t and additional sales in Japan.
Market Cap: ¥4.22t
For investors combing this cash flow screen, Astellas Pharma matters because its oncology and specialty drugs already generate meaningful branded cash that underpins the discounted cash flow story.
"Patent expirations for key drugs such as XTANDI and mirabegron threaten to create substantial revenue and earnings losses as generic entrants erode Astellas' market share in critical therapeutic areas over the next several years."
What happens if one quiet shift in future pricing power and product mix tilts that cash engine away from the current DCF assumptions?
That quiet tilt in pricing power is exactly what the full narrative for Astellas Pharma unpacks, including where Astellas Pharma’s cash engine could accelerate again or remain stalled.
Terumo (TSE:4543)
Overview: Terumo is a global medical device group best known for its Cardiac and Vascular products that support minimally invasive cardiovascular procedures.
Operations: Terumo generates about ¥706.7b from Cardiac and Vascular, ¥240.2b from Blood and Cell Technologies, and ¥222.3b from Medical Care Solutions.
Market Cap: ¥3.38t
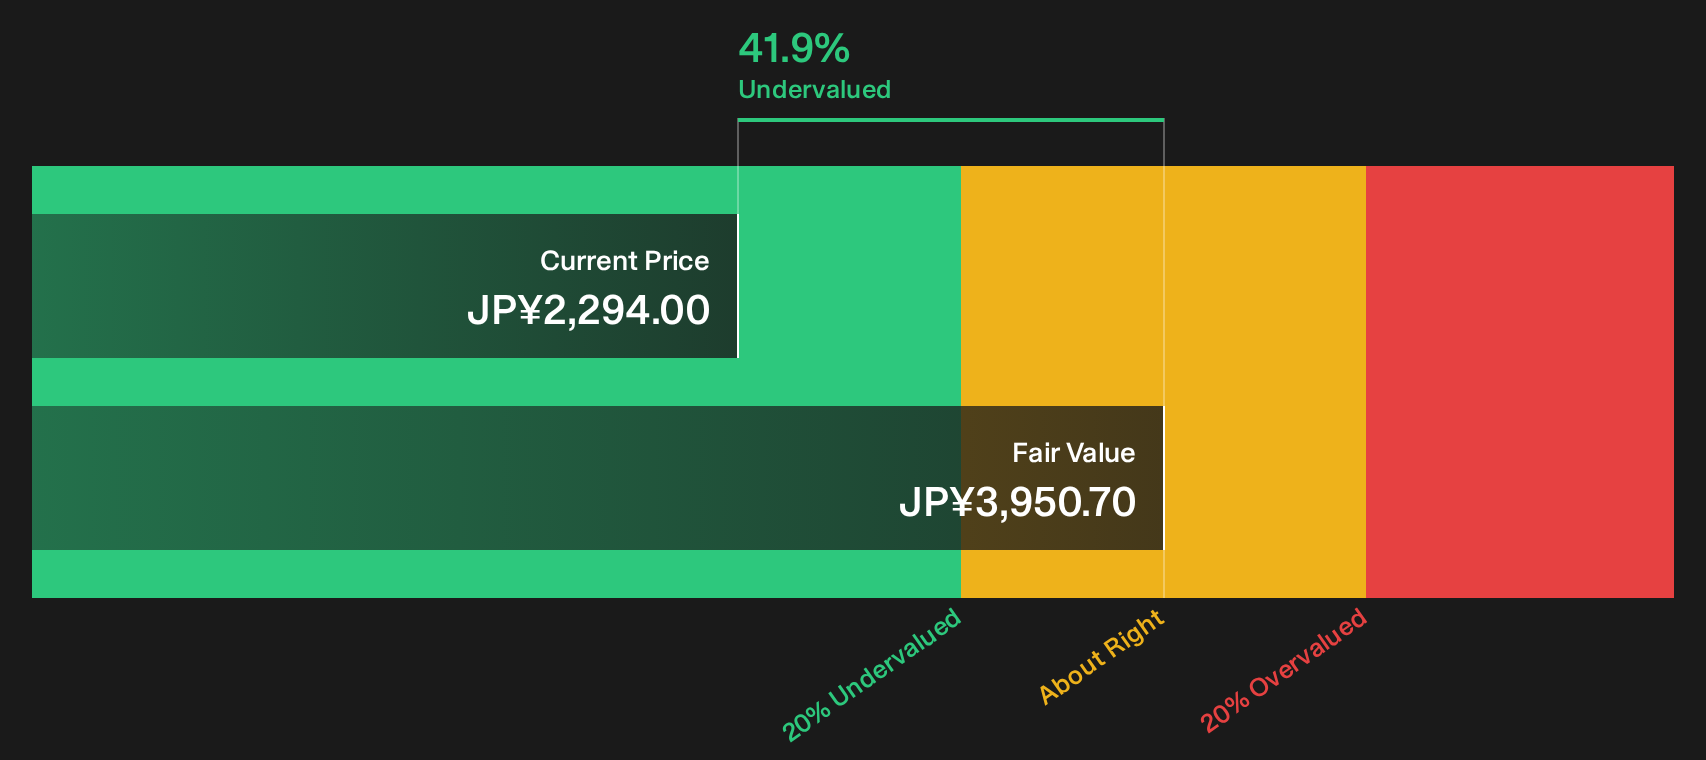
Terumo matters for this cash-flow screen because high-margin interventional tools in its Cardiac and Vascular arm feed repeat procedure demand and support the wider device portfolio.
"Expansion of sales channels and volume commitments in China, especially in Neurovascular products, has enabled Terumo to gain market share and increase prices, counteracting typical negative VBP (Volume-Based Procurement) effects and positioning the company for future revenue growth in this key emerging market."
What happens if one quiet shift in pricing pressure or product mix unsettles that balance between healthy margins and recurring procedure volumes?
To see how that tension could turn into accelerating upside or a stalled thesis, read the full narrative for Terumo for the complete risk and opportunity map.

Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum headlines hit, early entries are already flying. Use these under the radar lists while it matters and get in early.
- Target reliable portfolio anchors with income potential by scanning the curated 20 dividend fortresses that aim to keep cash flows coming in even when sentiment turns.
- Spot emerging themes in automation before they go mainstream by working through the hand picked 91 robotics and automation stocks packed with businesses shaping how factories and logistics operate.
- Track the infrastructure behind the AI surge by using the focused 84 AI infrastructure stocks to find suppliers that may benefit as data demand keeps building.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com