


The Zhitong Finance App learned that on September 29, the China Index Research Institute released a summary and trend outlook of China's real estate market for the third quarter of 2026. Since the third quarter, the real estate market has generally continued to bottom out, and the characteristics of differentiation are still quite obvious. New housing sales are still low, and first-tier cities are performing relatively well; second-hand housing transactions continue to grow, their share in housing transactions has further increased, and the market has entered an era of stock. In terms of prices, second-hand housing prices continue to adjust, and high-quality projects in core cities provide some support for the average price of new housing. The land market continues to shrink, and land acquisition by housing enterprises is further concentrated in core cities and high-certainty projects. In terms of policy, the reform of the commercial housing sales system was implemented on August 28, local rules began to be introduced at the end of September, and adjustments to the real estate development model were accelerated. Looking ahead to the fourth quarter, the market is expected to continue the established bottoming trend, and the impact of the New Deal will be further evident from 2027.
(1) Market supply and demand: According to preliminary statistics from the China Index, in the first three quarters of 2026, the sales area of newly built commercial residential homes in 100 cities fell about 10% year on year, and the third quarter fell about 5% year on year. The impact of the 8.28 New Deal on short-term sales is not obvious; improving demand is still the main support for the new housing market, and most of them indicate that the share of products over 120 square meters in the city's transactions continued to rise. Affected by the obvious contraction in supply, inventory of new homes continued to decline. The clearance cycle for 50 cities at the end of August was 22.8 months. Second-hand housing activity continued to operate at a high level. The number of second-hand housing units sold in 20 cities increased by about 6% year on year in the first three quarters. Since the second quarter, transactions have continued to grow year on year, and the increase narrowed in the third quarter. Stock listings in key cities have continued to decline since April, until August, when there was another slight increase from month to month.
(2) Housing prices: According to the China Index 100 Cities Price Index, since this year, second-hand housing prices have continued to fluctuate slightly. In January-August, second-hand housing prices in Baicheng fell by a cumulative total of 3.76%, and the decline increased in the third quarter. Driven by the entry of high-quality real estate properties into the market in some key cities, new housing prices in Baicheng continued to rise slightly. In January-August, new housing prices in Baicheng increased by 1.00%.
(3) Land market: The land market continues to be characterized by “shrinking volume and improving quality”. According to the China Index data, in the first three quarters (as of September 27), residential land transaction area and concession fees in 300 cities decreased by 23% and 22%, respectively; land concessions were further concentrated in core cities, accounting for 60% of the country's share of residential land concessions in the TOP20 cities, an increase of 8 percentage points over the full year of 2025. After the August 28 New Deal, the overall investment layout of housing enterprises became cautious. In September (as of the 27th), land concession funds in 300 cities fell 29% year on year. Enterprises paid more attention to the controllability of total prices and certainty of removal, and central state-owned enterprises remained the main force in land acquisition.
(4) Policy outlook: The top-level document on real estate system reform was implemented on August 28, and the Beijing and Shanghai rules were first introduced at the end of September. It is expected that more local supporting implementation rules will be implemented in the fourth quarter, including land concession installment payment rules, pre-sale fund disbursement conditions and procedures, and various index requirements for completion and acceptance. Clarification of local policies and rules will also enhance market predictability. At the same time, real estate supply and demand policies will still work collaboratively to stabilize the market. The demand side may focus on optimizing the provident fund policy, supporting housing “trade-in”, and issuing housing purchase subsidies; the supply side will focus on strictly controlling land growth, increasing efforts to revitalize stock, and increasing the construction of “good houses.” In addition, supporting policies for urban renewal will continue to be improved.
(5) Market trends: Looking ahead to the fourth quarter, the real estate market is expected to continue the established bottoming trend. Effective demand-side policies in core cities and the entry of high-quality projects into the market will still provide some support for new housing sales; second-hand housing transactions may maintain a high level of activity, but the listing scale is still relatively high, and prices may continue to adjust in the short term. The transmission of the August 28 New Deal is an important main line in the subsequent market: the implementation of local rules in the fourth quarter and the performance of land auctions during the peak land supply period at the end of the year are worth paying attention to. Policies such as minimum delivery units, installment payment of land payments, and transition period arrangements will directly affect the ability and willingness of enterprises to invest. In the medium term, with the gradual transmission of the impact of the New Deal on land acquisition strategies and capital utilization by housing enterprises, its impact on new supply will gradually become apparent from 2027. The second quarter of 2027 is a key observation period. The specific pace of transmission and the extent of influence still depend on local rules and transition arrangements for ongoing projects.
Part 1: Summary of China's real estate market situation in the third quarter of 2026
(1) Market supply and demand: The transaction area of new homes in 100 cities fell by about 10% year on year in the first three quarters and decreased by about 5% year on year in the third quarter; second-hand housing turnover in 20 cities increased by about 6% year on year in the first three quarters, increased 15% in the second quarter, and narrowed in the third quarter. Demand remained the main transaction force, and the overall listing volume stabilized
Since 2026, the total volume of new and second-hand housing transactions has been stable. Structurally, new home sales have continued to decline, second-hand housing transactions have continued to grow, and the characteristics of market differentiation have continued. Looking at the total volume of housing transactions, according to data from the National Bureau of Statistics and the Ministry of Housing and Construction, in January-August, the sales area of newly built commercial housing nationwide was 498.8 million square meters, a year-on-year decrease of 12.1%. The area of online second-hand housing transactions was 549.23 million square meters, an increase of 10.6% over the previous year. In the first half of this year, the share of second-hand housing transactions nationwide surpassed that of new housing for the first time. In January-August, the share further increased to 52.4%, and the market entered the stock era. In terms of key cities, according to data from the China Index, from January to August 2026, the number of second-hand housing transactions in the key 30 cities accounted for 68% of the total sales volume of new and second-hand housing. The share of second-hand housing transactions in core cities was significantly higher than the national level, and the stock characteristics were even more remarkable.
1. New housing: The sales area of new homes in the 100 key cities fell by about 10% year-on-year in the first three quarters. The market has remained stable since the second quarter, and first-tier cities have continued to grow; continued contraction in supply led to a decline in inventory scale
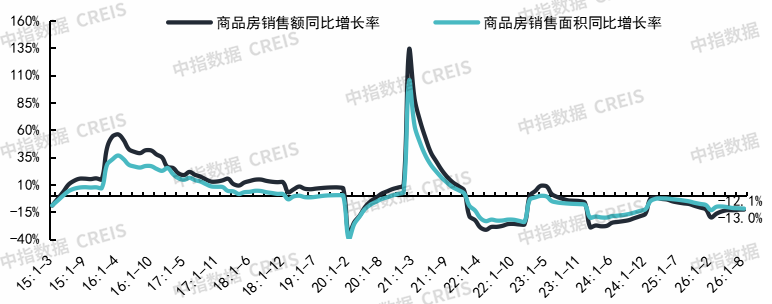
Figure: The cumulative sales area of commercial housing in the country and the year-on-year growth rate of sales
Data source: National Bureau of Statistics, China Index Data CREIS
National new home sales: According to data from the National Bureau of Statistics, from January to August 2026, the sales area of newly built commercial housing in the country was 50 million square meters, down 12.1% year on year, and the decline was 0.3 percentage points higher than in January-July. Among them, commercial residential sales area fell 13.0% year on year, and the decline increased 0.3 percentage points from January to July. Sales of newly built commercial housing in January-August were 4.7 trillion yuan, down 13.0% year on year, and the decline was 0.1 percentage points narrower than in January-July. Among them, sales of newly built commercial housing fell 13.1% year on year, and the decline was 0.1 percentage points narrower than in January-July.
Figure: Trends in monthly transaction area of newly built commercial housing in 100 representative cities*
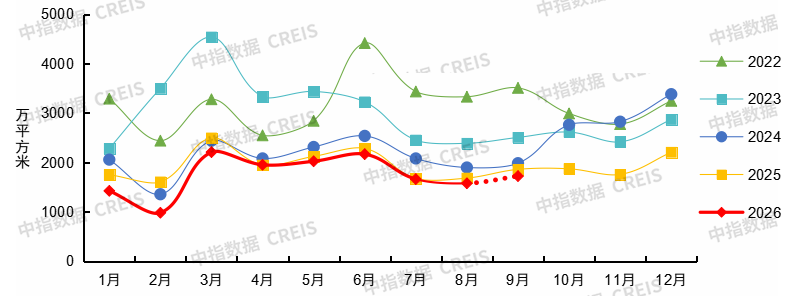
* There are 100 representative cities, including Beijing, Shanghai, Guangzhou, and Shenzhen; the first tier includes Tianjin, Shijiazhuang, Hohhot, Shenyang, Dalian, Changchun, Harbin, Nanjing, Suzhou, Wuxi, Hangzhou, Ningbo, Wenzhou, Hefei, Fuzhou, Xiamen, Jinan, Qingdao, Zhengzhou, Wuhan, Nanchang, Changsha, Nanning, Beihai, Haikou, Sanya, Chongqing, Chengdu, Guiyang, Kunming, Xi'an, Lanzhou, Xichuanning, 34 Cities; the third and fourth tier includes Tangshan, Handan, Baoding, Yantai, Tai'an, Weihai, Weifang, Zibo, Dongying, Heze, Lishui, Nantong, Yangzhou, Zhenjiang, Kunshan, Jiangyin, Zhangjiagang, Changshu, Taicang, Wuhu, Huaibei, Chizhou, Shaoxing, Jinhua, Huizhou, Zhoushan, Xuzhou, Quzhou, Changzhou, Taizhou, Yancheng, Huai'an, Lianyungang, Anqing, Maanshan, Suzhou, Foshan, Zhuhai, Huizhou, Zhongshan, Dongguan, Jiangmen, Meizhou, Shaoguan, Quanzhou, Yueyang, Ganzhou, Jiujiang, Jingdezhen, Huangshi, Yueyang, Ganzhou, Jiujiang, Jingdezhen, There are 62 in Luzhou, Meishan, Liuzhou, Luoyang, Shangqiu, Weinan, and Zunyi.
Note: September is estimated based on 1-27 data
Data source: Middle Index Data CREIS
New housing sales in key cities: According to preliminary statistics from the China Index, in the first three quarters of 2026, the transaction area of newly built commercial housing in the 100 key cities decreased by about 10% year-on-year. Specifically, sales fell 21% year on year in the first quarter, and the decline was quite obvious; as the base declined in the second quarter, compounded by continuous optimization of demand-side policies in core cities, overall transactions remained stable, and the year-on-year decline narrowed to 3%. Entering the third quarter, the sales area of new homes in key traditional off-season cities in July-August declined month-on-month, with year-on-year declines of 1% and 6%, respectively. In September, the year-on-year decline continued. According to preliminary statistics from the Central Index, the sales area of newly built homes in key cities fell by about 7% year on year in September, and overall fell by about 5% year on year in the third quarter.
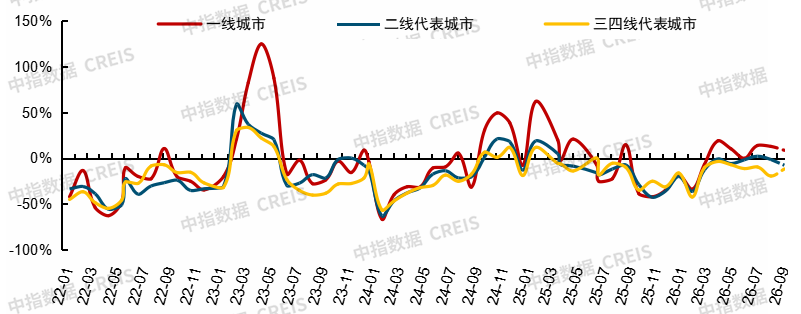
Figure: Since 2022, each tier represents the year-on-year trend in the monthly transaction area of newly built commercial housing in cities
Data source: Middle Index Data CREIS
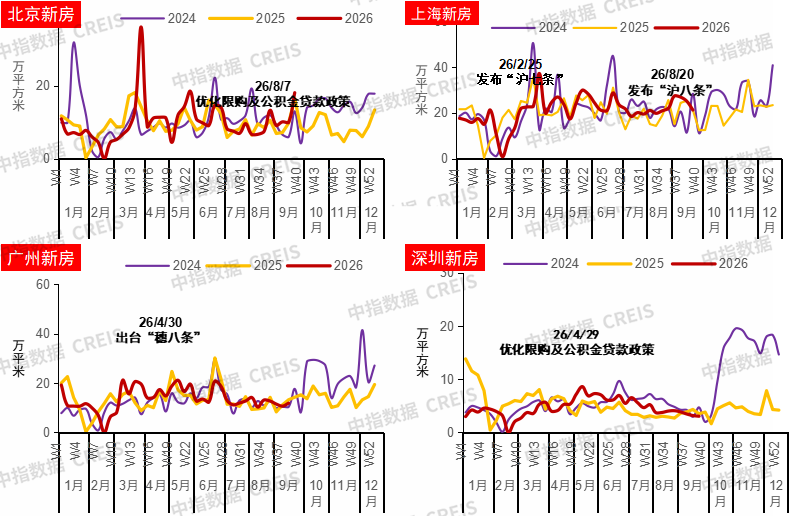
Figure: Weekly transaction area trends for new homes in Beijing, Shanghai, Guangzhou and Shenzhen
Data source: Middle Index Data CREIS
Looking at the branch line, the overall sales of new homes in first-tier cities have remained stable. According to preliminary statistics from the China Index, the sales area of new homes in first-tier cities increased by about 1% year-on-year in the first three quarters, with a year-on-year increase of 9% in the second quarter. The growth trend continued in the third quarter. July and August increased 14% and 13%, respectively, and 9% year-on-year on September 1-27. Driven by demand side policy optimization in August, Beijing and Shanghai increased 18% and 16%, respectively. New home sales in second-tier and third-tier and fourth-tier cities are still declining. In the first three quarters, the sales area of new homes in second-tier and third-tier cities fell by about 9% and 14%, respectively. Among them, second-tier cities fell 3% year on year in the third quarter and 13% year on year in third- and fourth-tier cities.
Figure: Percentage of newly built commercial residential units sold in each area segment in 30 representative cities
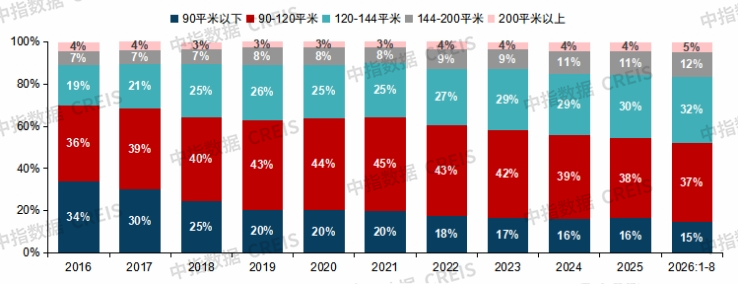
New housing demand characteristics: According to data from the Central Index, from January to August 2026, 30 cities accounted for 48% of new housing transactions of 120 square meters or more, the same as in the first half of the year, an increase of 2.3 percentage points over the whole of last year. The share of new housing transactions of 90-120 square meters and below has continued to decline in the past 5 years. Looking at specific cities, from January to August 2026, 10 key cities including Changsha, Jinan, and Suzhou accounted for more than 60% of new housing transactions; cities such as Hangzhou and Suzhou accounted for more than 30% of new housing transactions of 144 square meters or more; compared with the same period in the same period of 2025, 21 cities accounted for an increase in the share of 120-144 square meter new housing transactions. Among them, cities such as Chongqing, Nanchang, and Tangshan increased significantly; 19 cities accounted for a significant increase in the number of new housing transactions of 144 square meters or more; among them, 19 cities accounted for an increase in the number of new housing transactions of 144 square meters or more. Upgrading cities such as Zhou, Jinan, and Ningbo The margin was over 4 percentage points; Beijing, Shanghai, Guangzhou, and Shenzhen all accounted for an increase in the number of new housing units over 200 square meters.
Figure: Weekly market area trends approved for commercial housing in 50 representative cities*
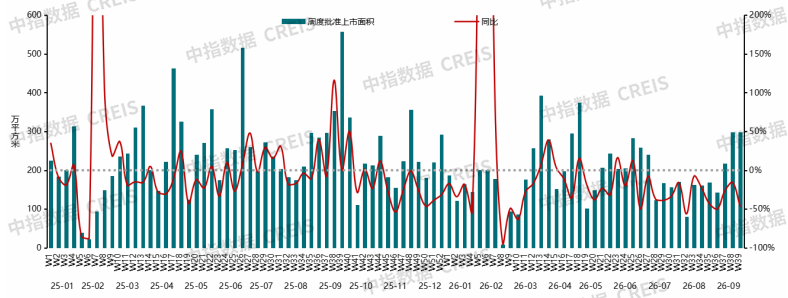
* 50 representative cities include Beijing, Shanghai, Guangzhou, Shenzhen, Tianjin, Shenyang, Dalian, Changchun, Nanjing, Suzhou, Wuxi, Hangzhou, Ningbo, Wenzhou, Hefei, Fuzhou, Xiamen, Jinan, Qingdao, Zhengzhou, Wuhan, Changsha, Nanning, Chongqing, Chengdu, Xi'an, Lanzhou, Yantai, Tai'an, Weihai, Lishui, Nantong, Yangzhou, Zhenjiang, Kunshan, Jiangyin, Zhangjiagang, Changshu, Taicang, Wuhu, Huaibei Guangzhou, Foshan, Zhuhai, Huizhou, Zhongshan, Quanzhou, Putian, Huangshi, Weinan, the same as below.
Data source: Middle Index Data CREIS
New housing supply in key cities: According to preliminary statistics from the China Index, in the first three quarters of 2026, the approved listing area of commercial housing in the 50 key cities fell by about 20% year-on-year, and the supply scale of new housing was still low. Among them, the decline in the first quarter and the second quarter decreased 16% and 19%, respectively; in the third quarter, the supply of new homes in the 50 traditional off-season cities fell 29% year on year. In the first four weeks of September, the approved listing area for newly built commercial housing in the 50 key cities fell by more than 30% year on year, continuing the trend of supply contraction since this year, but this change is mainly the cumulative result of the continuous decline in previous land transactions and new construction starts. The direct impact on the current scale of new housing listings was relatively small.
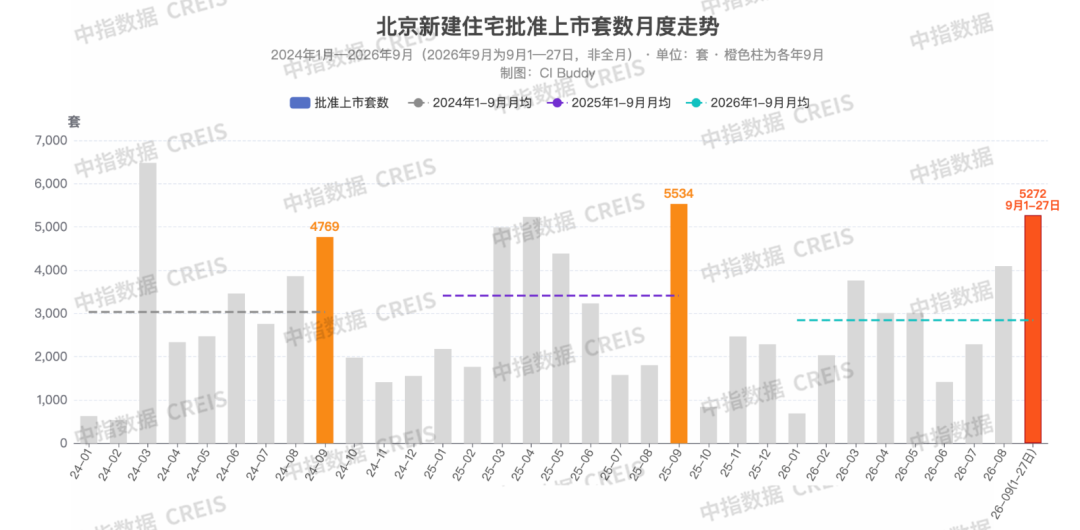
It is worth noting that the pace of evidence collection in some core cities has accelerated since September. Take Beijing as an example. From September 1 to 27, the number of new housing units listed in Beijing reached 5,272, which has already exceeded the total monthly scale for each month of this year. Some housing enterprises are also speeding up the pace of construction and evidence collection. For projects that have met or are close to pre-sale conditions before the New Deal, some companies tend to speed up evidence collection and enter the sales stage in order to shorten the capital occupation cycle. This also means that the short-term supply side will still be dominated by stock projects, and the New Deal has yet to form an obvious supply gap.
Figure: Year-on-year growth rate of commercial housing and commercial residential area for sale across the country
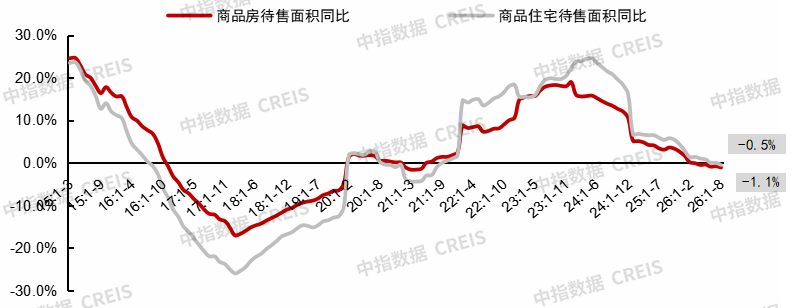
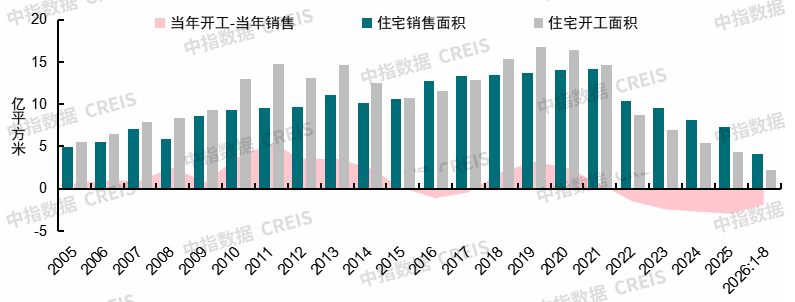
Figure: Construction of newly built commercial housing across the country started in the same year - sales area in that year
Data source: National Bureau of Statistics
National inventory of new homes: Judging from the completed inventory, according to data from the National Bureau of Statistics, at the end of August 2026, the area of commercial housing for sale was 753 million square meters, down 1.1% year on year, and has been declining year on year for 6 consecutive months. Among them, the area to be sold for less than 3 years was 548 million square meters, a year-on-year decrease of 4.2%. Looking at the comparison between commencement and sales, in January-August of this year, 218 million square meters of new residential construction nationwide were down 25.4% year on year; the sales area of newly built homes was 415 million square meters, down 13.0% year on year. Since 2022, the new residential construction area has continued to be smaller than the sales area, driving the inventory scale down gradually, but the inventory scale is still high. By the end of August, the inventory of newly built homes that had been built and not sold (cumulative construction since 1998 - cumulative sales) was 2.51 billion square meters, down 32% from the end of 2021.
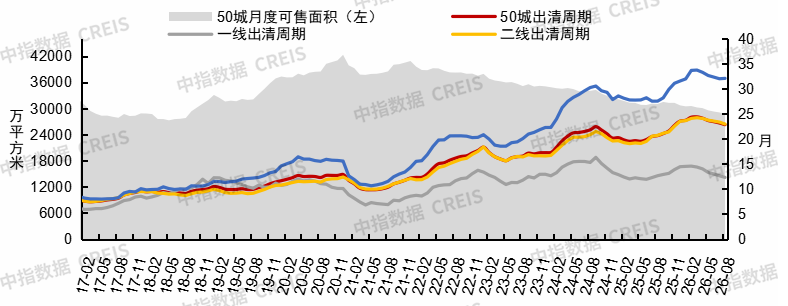
Figure: Trends in the inventory and clearance cycle of newly built commercial housing in 50 representative cities
Data source: Middle Index Data CREIS
Saleable inventory of new homes in key cities: According to the China Index data, as of the end of August 2026, the sales area of newly built commercial homes in the 50 representative cities was 287 million square meters. Continued contraction in supply drove the inventory scale to continue to decline. In August, the saleable area fell 1.3% month-on-month and 7.5% year-on-year. Although the inventory scale continues to decline, due to the slow restoration of new home sales, the clearance cycle remains high. Based on the average monthly sales area for the past 12 months, the inventory clearance cycle for the 50 cities at the end of August was 22.8 months, down 0.3 months from month to month, and an increase of 2.2 months over the previous year. Looking at various tier cities, as of the end of August, the inventory clearance cycle for new homes in first-tier cities was 12.3 months, 23.0 months for second-tier representative cities, and 32.1 months for third-tier and fourth-tier cities.
2. Second-hand housing: The number of second-hand housing units sold in 20 cities increased by about 6% year-on-year in the first three quarters. Since the second quarter, transactions have maintained a high level of activity. The year-on-year increase narrowed in the third quarter, and demand was still dominated by low total prices and immediate demand; overall listing volume stabilized
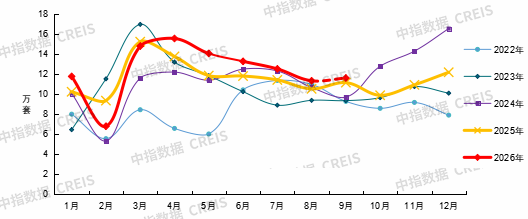
Figure: Trends in monthly sales of second-hand housing units in 20 representative cities
Note: September is estimated based on 1-27 data
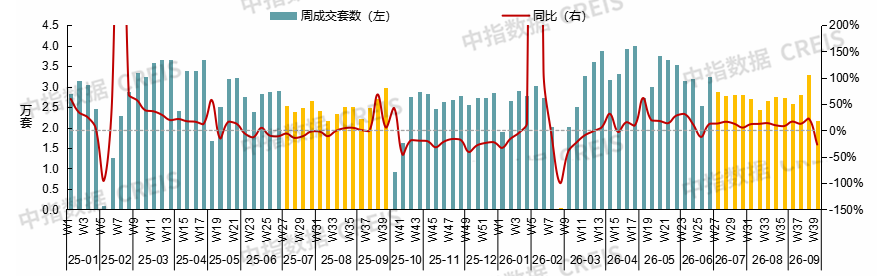
Figure: Weekly number of second-hand housing units sold in 20 representative cities and the year-on-year trend
Data source: Middle Index Data CREIS
Second-hand housing activity in key cities continues to operate at a high level, and turnover has maintained year-on-year growth since the second quarter. According to data from the China Index, in the first three quarters of this year (as of 9.27), 20 key cities sold 1.1 million second-hand residential units, with a year-on-year increase of 6%, with a year-on-year decline of 4% in the first quarter and a year-on-year increase of 15% in the second quarter. The overall growth trend continued in the third quarter, but the quarterly increase narrowed to 7%. In July-August, 10% and 8% year-on-year respectively. As of September 27, second-hand residential units were sold in 20 cities, up 3.6% month-on-month and 4.2% year-on-year.
Table: Second-hand housing transactions in key cities in the first three quarters of 2026 (as of 9.27) (unit: unit)
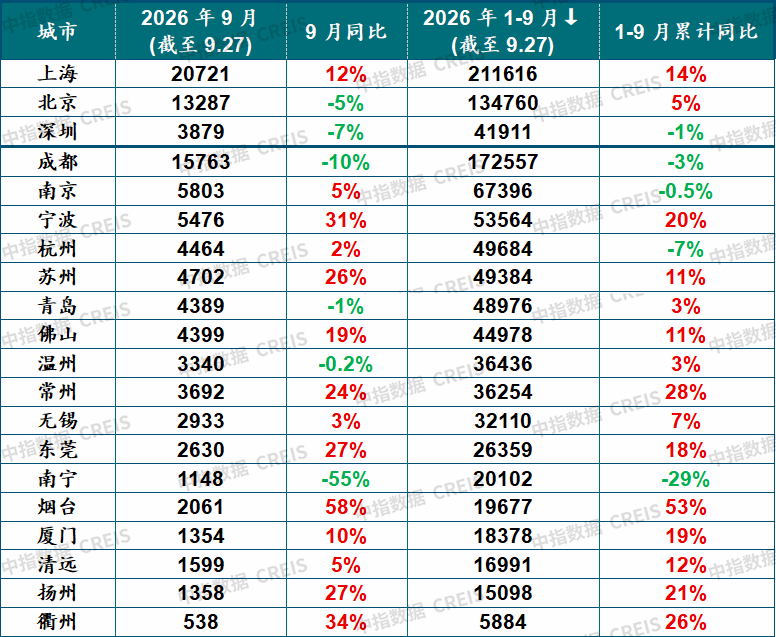
Note: Shanghai, Wuxi, Nanning, and Wenzhou are second-hand commercial housing; other cities are second-hand commercial housing
Data source: Middle Index Data CREIS
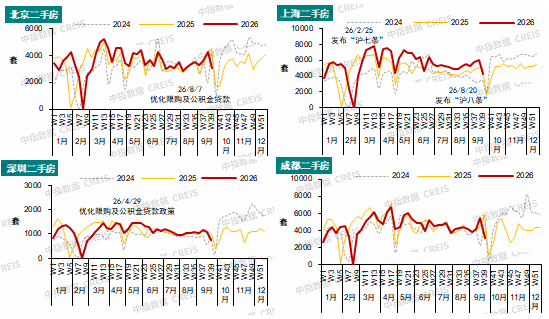
Figure: Weekly second-hand housing transaction trends in Beijing, Shanghai, Shenzhen and Chengdu
Data source: Middle Index Data CREIS
Looking at key cities, second-hand housing market transactions in core cities such as Beijing and Shanghai continue to increase. The Beijing-Shanghai market was driven by the continuing effects of demand-side policies in August, and the market remained active. As of September 27, the number of second-hand housing units sold increased 11.2% and 6.8%, respectively, and Shanghai increased 12.3% year on year, for seven consecutive months. Beijing fell slightly by 4.7% year on year, and Shenzhen fell 7.0% year on year. On a cumulative basis, the volume of second-hand housing transactions in Beijing and Shanghai increased by 5% and 14%, respectively, in the first three quarters of this year, while Shenzhen remained basically the same.
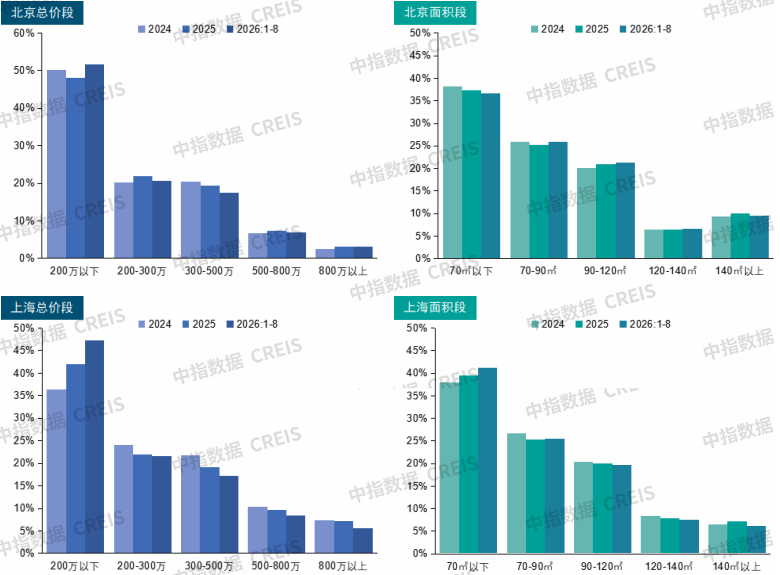
Figure: Percentage of second-hand housing units sold in each area segment and total price segment in Beijing and Shanghai (according to online price)
Data source: Middle Index Data CREIS
Small apartments and low total price properties are still the basic market for second-hand housing transactions, and the market is characterized by “immediate dominance and structural restoration”. Unlike the continuous trend of new housing transactions towards improving apartment types, second-hand housing transactions in core cities are still dominated by the immediate demand for small apartments. As second-hand housing prices continue to be adjusted, the cost performance ratio of some low total price and small-sized housing has gradually become apparent, becoming the core choice for those who just need to buy a home. Looking at the total transaction price segment, from January to August 2026, the share of second-hand housing transactions under 3 million in Beijing and Shanghai reached 72.3% and 68.8% respectively, up 2.2 and 4.9 percentage points from the full year of 2025, but down 1.4 and 0.3 percentage points from the first half of the year, and the share of properties above 3 million increased slightly in the third quarter. In terms of transaction area, from January to August 2026, second-hand housing transactions under 70 square meters in Beijing and Shanghai accounted for 36.6% and 41.2%, respectively, and 62.6% and 66.7% of transactions for properties under 90 square meters.
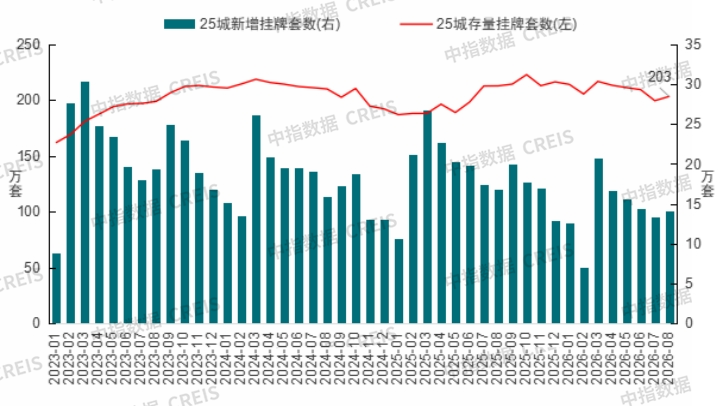
Figure: Number of new second-hand housing units added and listed in stock in 25 key cities (leading intermediary scale)
Data source: Middle Index Data CREIS
Second-hand housing listings in key cities: Since April this year, overall stock listings have gradually declined, with a slight increase over the previous month in August. According to China Index monitoring, the number of listings has declined for 4 consecutive months since the second quarter of 2026, but there was a slight recovery in August. At the end of August, the number of second-hand housing listings in 25 key cities was 2.03 million units, up 1.9% from the previous month, down 4.5% year on year, down 6% from the beginning of the year. The absolute scale is still at a high level; among them, Beijing and Shanghai fell 12% and 16% respectively from the beginning of the year. Since this year, the decline in core city listings reflects the restoration of owners' expectations, but the sustainability of the improvement in the relationship between supply and demand still needs to be observed.
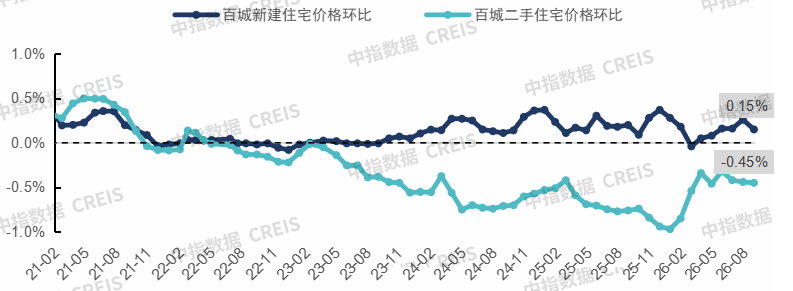
(2) Price level: Second-hand housing prices in Baicheng fell by 3.76% in January-August, and the month-on-month decline increased slightly in the third quarter; the entry of quality improvement projects led to a cumulative increase of 1.00% in new housing prices in Baicheng
Figure: Month-on-month changes in the prices of newly built homes and second-hand homes in Baicheng
Data source: Middle Index Data CREIS
In terms of second-hand housing, according to the Baicheng Price Index of the China Real Estate Index System, from January to August 2026, second-hand housing prices in Baicheng fell by a cumulative total of 3.76%, a decline of 1.33 percentage points narrower than the same period in 2025. Among them, the cumulative decline in the first quarter was 1.72%, and the single-quarter decline narrowed to 1.20% in the second quarter. Since the third quarter, the month-on-month decline in second-hand housing prices in Baicheng increased slightly. In August, the average price of second-hand housing in Baicheng was 1,2527 yuan/square meter, down 0.45% month-on-month, an increase of 0.01 percentage points over the previous month. Looking at each echelon, in January-August, second-hand housing prices in first-tier cities fell by a total of 2.76%, less than other echelons; second-hand housing prices in second-tier cities fell by 4.08%; and second-hand housing prices in third- and fourth-tier cities fell by a cumulative total of 3.83%.
In terms of newly built housing, according to the Baicheng Price Index of the China Real Estate Index system, the price of newly built homes in Baicheng increased by 1.00% from January to August 2026, driven by the structural nature of new projects entering the market in core cities. Specifically, the price of newly built homes in Baicheng rose 0.18% in the first quarter, increased to 0.40% in the second quarter, and increased by 0.41% in July-August. In August, the average price of newly built homes in Baicheng was 17,255 yuan/square meter, up 0.15% month-on-month and 2.04% year-on-year. Looking at the hierarchy, in January-August, the cumulative price of newly built homes in first-tier and second-tier cities rose by 2.65% and 0.89%, respectively, while the cumulative decline in third-tier and fourth-tier representative cities was 1.34%.
Figure: Prices of newly built homes and second-hand homes in 100 cities fell month-on-month, and changes in the number of cities
Data source: Middle Index Data CREIS
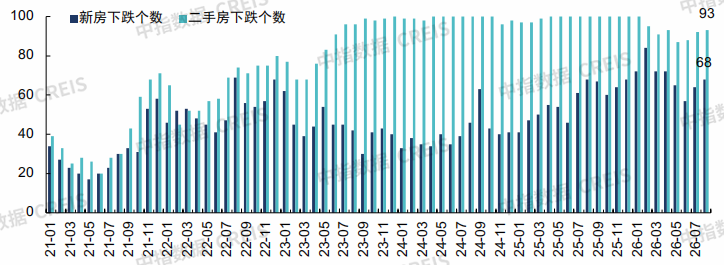
Looking at the number of cities that have risen and fallen, in terms of new housing, in January-August, the number of cities where the price of newly built homes in Baicheng fell month-on-month was between 55-85. Among them, the number of cities where the price of newly built homes in Baicheng fell month-on-month in January-June, showed a downward trend, and increased again in July-August. In terms of second-hand housing, the number of cities where second-hand housing prices fell month-on-month in January-August showed a trend of narrowing first and then expanding. Among them, the number of cities where second-hand housing prices fell month-on-month in January-May showed a declining trend. Since June, the number of cities that have declined has increased, and the number of cities that fell month-on-month in July-August once again exceeded 90.
(3) Land market: In the first three quarters, residential land transaction area and concession fees in 300 cities decreased by 23% and 22%, respectively; with the implementation of the 8.28 New Deal, housing enterprises tend to be cautious in acquiring land. As of September 27, concessions fell 29% year on year
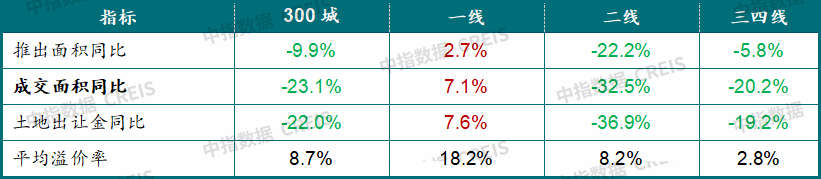
300 cities: The land market continued to be characterized by “shrinking volume and improving quality” in the third quarter, and the scale of transactions continued to shrink. In August, high-priced land plots in core cities led to a marked increase in concession funds, and declined again year on year in September. According to data from the China Index, in the first three quarters of 2026 (as of September 27), 300 cities launched plans to build 320 million square meters of residential land, a year-on-year decrease of 9.9%; sales of 220 million square meters, a year-on-year decrease of 23.1%; and land concessions of 1.0 trillion yuan, a year-on-year decrease of 22.0%. In the third quarter (ending September 27), driven by high-quality land transactions in hot cities such as Beijing, Shanghai, Hangzhou, and Shenzhen in August, residential land concessions in 300 cities fell 4.6% year on year. The decline was significantly narrower than in the second quarter, and the transaction area still fell 24.3% year on year.
Looking at September alone, land market transactions declined due to the combined effects of a slowdown in the pace of land supply and the trend towards prudent pricing by housing enterprises after the August 28 New Deal. From September 1 to 27, 300 cities planned to build a residential land area of 29.82 million square meters, with land concessions of 115.5 billion yuan, a year-on-year decrease of 37.4% and 29.0%, respectively.
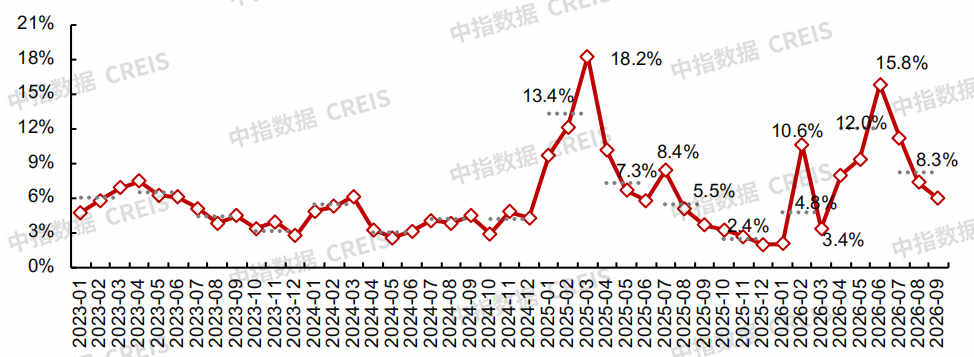
In terms of the popularity of land auctions, the average premium rate for residential land in 300 cities declined overall in the third quarter. From September 1 to 27, it was 6.0%, down 1.4 percentage points from August. Most cities mainly traded at reserve prices and low premium prices. Judging from the city's performance, land auctions in core cities such as Beijing, Shanghai, Guangzhou, Shenzhen, and Hangzhou remain popular, and many high-quality plots are sold at higher premiums; some plots with good locations and manageable total prices in cities such as Wuhan, Zhengzhou, and Tianjin have also received corporate attention. Looking at land acquisition companies, central state-owned enterprises such as CNOOC and Poly are still the main participants in hot land plots, and some regional private enterprises that are deeply involved in the local market have also made gains in the local market.
Figure: Residential land planning and construction launch and transaction trends in 300 cities (as of September 27, same below)
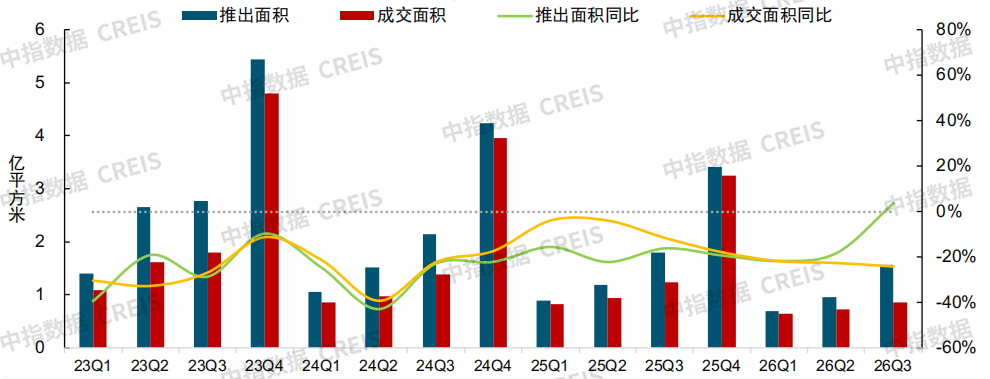
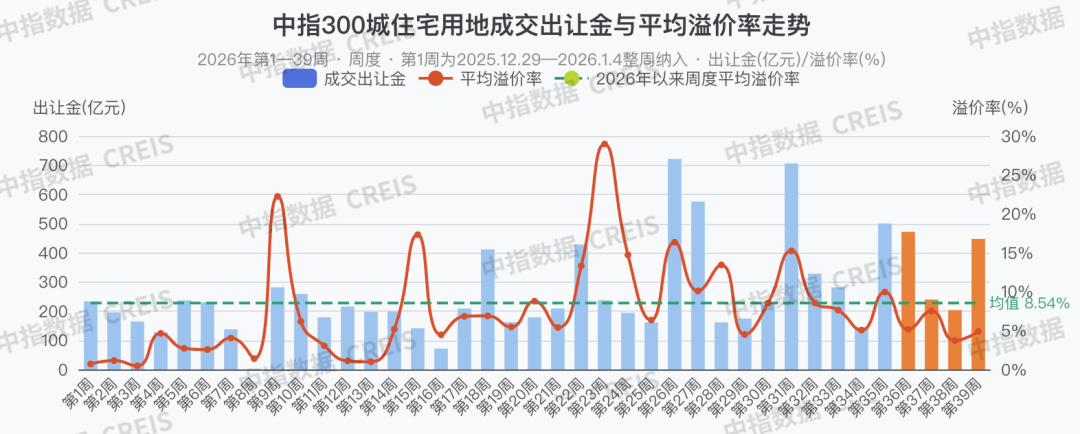
Table: Year-on-year changes in indicators related to residential land launches and transactions in 300 cities in the first three quarters of 2026 (as of September 27)
Note: The launch area is calculated according to the announcement time, as below.
Data source: Middle Index Data CREIS
In September, the fragmentation of residential land transactions in various tier cities further intensified. The transaction scale and concession funds in first-tier cities increased year-on-year, second-tier cities continued to shrink, and third- and fourth-tier cities were still operating at a low level.
The residential land market in first-tier cities is very popular. As of September 27, under a low base, transaction plans and land concession funds all increased by about 90% year-on-year, with an average premium rate of 15.1%. After the 8.28 New Deal, high-quality residential land in first-tier cities was still the focus of housing enterprise layout, and all cities had plots sold at higher premiums. Cumulatively, in the first three quarters (as of September 27), residential land launch and transaction area in first-tier cities increased by 2.7% and 7.1%, respectively. Land concessions increased 7.6% year over year, and the average premium rate was 18.2%. The supply of high-quality land plots in core cities is unabated. Combined, sales of new homes are relatively steady, and land acquisition by housing enterprises continues to be concentrated in high-certainty sectors in first-tier cities.
The characteristics of land market differentiation in second-tier cities continue. As of September 27, construction plans and concession fees all declined year-on-year, with an average premium rate of only 3.7%; although Hangzhou, Chengdu, Xi'an, and Zhengzhou all sold premium plots, the overall premium level was limited, and it is still rational for housing enterprises to acquire land. Cumulatively, in the first three quarters (as of September 27), residential land launches and transaction areas in second-tier cities decreased by 22.2% and 32.5%, respectively, and land concessions fell 36.9% year on year. Land auctions shrank significantly. Under the influence of the “market-based investment” strategy, investment by housing enterprises has further shrunk from ordinary second-tier cities, and the scale of local land supply has been reduced accordingly; high-quality land plots in strong second-tier cities such as Hangzhou and Chengdu remain popular. Local housing enterprises in cities such as Zhengzhou are relatively active in participating in plots with good locations and controlled total prices. Most urban land auctions are mainly based on low premium or reserve price transactions. The average premium rate for the first three quarters was 8.2%.
Land market performance in third- and fourth-tier cities is sluggish. As of September 27, the year-on-year decline in transaction planning and concession fees was still significant, with an average premium rate of only 2.7%. Cumulatively, in the first three quarters (as of September 27), residential land transaction area and land concession fees in third- and fourth-tier cities decreased by 20.2% and 19.2%, respectively, over the same period last year, with an average premium rate of 2.8%. Affected by factors such as continuous adjustments in the new housing market and weak demand support, housing enterprises are generally cautious about their layout in third- and fourth-tier cities, and land transactions are mainly based on reserve prices.
Figure: Trends in the average premium rate of residential land in 300 cities (as of September 27)
Data source: Middle Index Data CREIS
In terms of premium rates, in the third quarter, the average premium rate for residential land in 300 cities declined month by month from a high point during the year. In June, driven by concentrated transactions of high-quality land plots in core cities, the average premium rate for residential land in 300 cities rose to 15.8%, the highest level in the year; it fell back to 11.2% and 7.4% in July and August, respectively, and fell further to 6.0% as of September 27th. The premium rate declined. First, the core cities concentrated on land promotion at the end of the second quarter, and the base figure was relatively high; second, after the August 28 New Deal, the project capital occupation cycle lengthened, housing companies' offers became more restrained, and the phenomenon of land chasing at high prices decreased markedly. However, it is also important to note that the average premium rate of first-tier cities reached 18.2% in the first three quarters, and auctions for high-quality land in core cities are still popular. The decline in the premium rate is more reflected in ordinary cities and non-core plots, and the pattern of differentiation under “spotty heat” continues.
Figure: Residential land concessions in different cities have accounted for the share of the country since 2020 (the entire city, as of September 27)
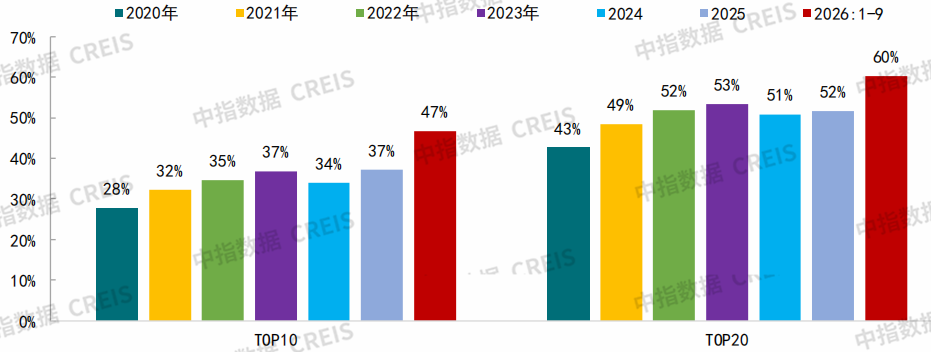
Table: Status of residential land concessions in key cities in the first three quarters and three quarters of 2026 (city-wide, as of September 27)
Data source: Middle Index Data CREIS
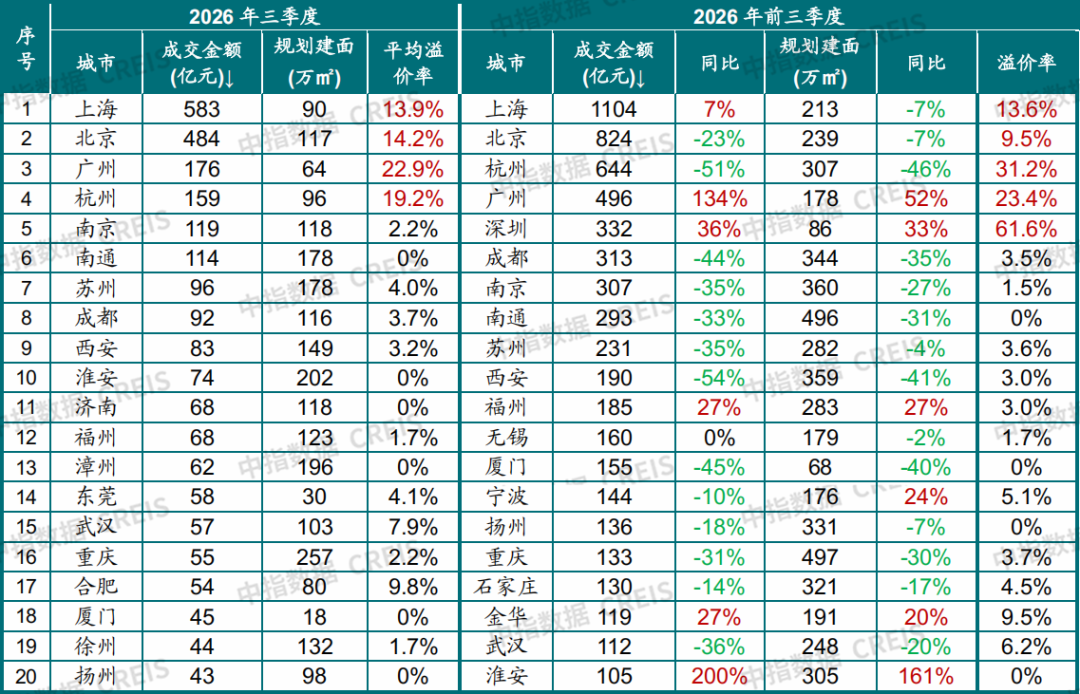
In the third quarter, land concessions in key cities were further concentrated at the top. According to data from the China Index, in the third quarter (as of September 27, same below), Shanghai and Beijing residential land concessions were 58.3 billion yuan and 48.4 billion yuan respectively, ranking in the top two, with Guangzhou and Hangzhou both exceeding 15 billion yuan. In terms of premium rates, the average premium rates for the third quarter of Guangzhou and Hangzhou reached 22.9% and 19.2% respectively, while Beijing and Shanghai were 14.2% and 13.9% respectively. Many high-demand plots appeared. On July 28, the Badaitou Group plot in Yangpu District of Shanghai was sold for 16.12 billion yuan through 219 rounds of bidding, with a premium rate of 35.8%; on August 12, the Sijiqing plot in Haidian District of Beijing sold 9.76 billion yuan through 135 rounds of bidding, setting a new high total residential land price during the year; on August 28, the Pazhou plot in Haizhu District of Guangzhou was sold at a 33% premium during the year.
Looking at the cumulative distribution of the first three quarters, there was a clear division between cities. Shanghai's concessions were 110.4 billion yuan, up 7% year on year; Guangzhou and Shenzhen increased 134% and 36% year on year, respectively; the rest of the cities mostly declined year on year. Looking at urban concentration, according to data from the China Index, in the first three quarters of 2026 (as of September 27), residential land concessions in the top 20 cities in the country accounted for 60% of the country's share, an increase of 8 percentage points over the full year of 2025.
On August 28, the Ministry of Housing, Urban-Rural Development, the Ministry of Natural Resources, and the State Administration of Financial Supervision and Administration jointly issued the “Notice on Improving the Commercial Housing Sales System” to reform and improve the real estate development, financing and sales system, making it clear that new land concession projects will prioritize existing housing sales, and raise the pre-sale threshold to the top of the main structure. The increase in pre-sale conditions and the backward repayment node means that the capital occupation cycle for projects from land acquisition to repayment has been significantly lengthened, and the financial threshold for land acquisition and development for housing enterprises has been raised accordingly, and the competitive logic of the land market is being reshaped.
Judging from the progress of implementation, the New Deal is still in the policy transition stage, and local rules are being introduced one after another. On September 24 and 28, Beijing and Shanghai successively issued implementation opinions on implementing the 8.28 New Deal, becoming the first cities to implement the rules. The rules of the two places are highly aligned on core arrangements such as raising the pre-sale threshold to the top of the main structure, full supervision of pre-sale funds, and core arrangements such as issuing mortgage loans, installment payment of land concession prices without interest, etc. All projects in transit implement a “division between old and new” and classification. Projects that have acquired land before August 28 but have not yet obtained a construction project planning license can be applied for pre-sale according to the original pre-sale conditions before the end of 2027. At the same time, Beijing and Shanghai have made it clear that pre-sale permits can be obtained before the end of 2027. Personal housing mortgage loans (including provident fund loans) must be issued after completion and filing . Furthermore, the two places have retained certain differentiated arrangements in line with the actual situation of the city, such as the current sales deposit ratio (Beijing 1%, Shanghai 3%), housing fund supervisory authorities, and land payment terms (Beijing balance is paid within two years; Shanghai adopts the “1+1" model, which can be extended for another year after decision). The Beijing and Shanghai rules have been implemented one after another, and the overall framework of the old and new dividing and classification policies has gradually become clear, providing reference for other cities to introduce implementation rules.
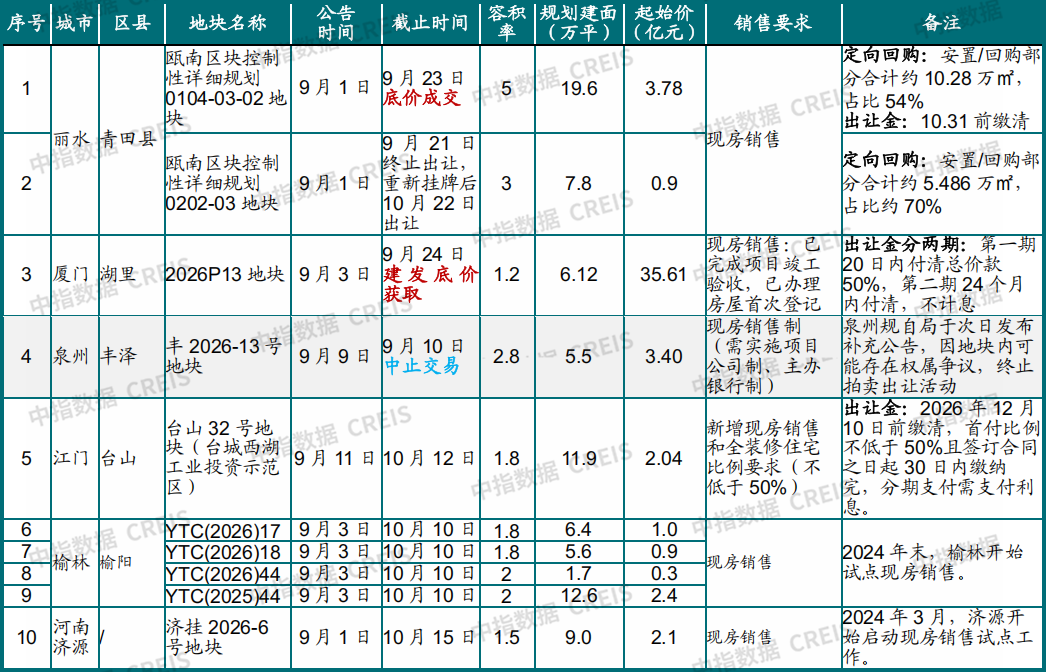
As of September 28, only Beijing and Shanghai have introduced relevant implementation rules, and only a few cities in the newly announced plots in September have clarified requirements for the sale of existing homes. According to monitoring by the China Index, from August 31 to September 27, only places such as Xiamen, Lishui, and Jiangmen clearly implemented existing housing sales, and some plots were also provided with arrangements such as installment payment of land payments. For example, existing land sales plots in Xiamen clearly can be paid in two installments, and the second phase can be paid within 24 months without interest. Jiangmen requires payment within 2 months. Against the backdrop of an extended capital occupation cycle, the Beijing and Xiamen practices hedge to a certain extent the pressure on housing companies' cash flow and are expected to be the choice of most cities.
Table: Status of land plots requiring the sale of existing homes since the August 28 New Deal
Data source: Middle Index Data CREIS
Judging from local auction performance, four weeks after the New Deal (August 31 to September 27), residential land concessions in 300 cities were 47.2 billion yuan, 23.9 billion yuan, 20.3 billion yuan, and 44.7 billion yuan respectively; the average premium rates were 5.2%, 7.5%, 3.7%, and 4.9%, respectively. High-premium land plots in key cities continue to decline, and floor price and low premium transactions have become mainstream for non-core land plots. Housing enterprises tend to be cautious in their overall pricing. They generally include capital costs and potential risks associated with existing housing sales in land acquisition estimates, and reserve pricing and profit margins for projects.
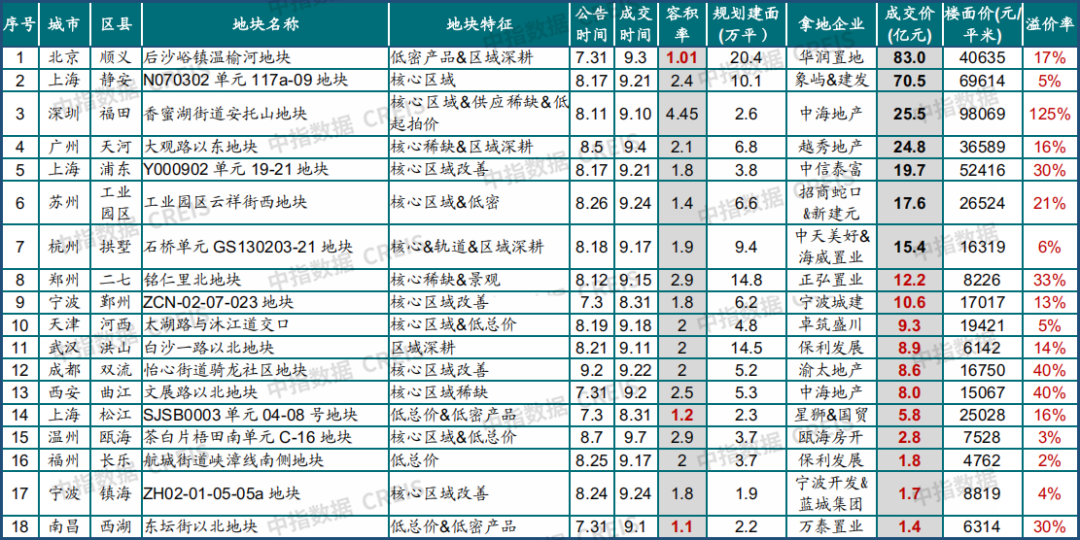
Judging from the logic of land acquisition, the investment scale of housing enterprises is rapidly converging towards “certainty.” First, the improved land plot in the core area received a high level of attention. On September 3, the Wenyu River plot in Shunyi, Beijing (floor area ratio 1.01) and the Shanghai Songjiang Sijing plot (floor ratio 1.2) were sold at a premium of 17.4% and 16.4% respectively. The pace of low-density project development was relatively controllable, which was conducive to reaching pre-sale or current sales conditions faster, partially hedging capital occupation pressure; on September 10, the Shenzhen Futian Xiangmihu plot was pure commercial residential land supplied again after a lapse of nearly ten years. The initial floor price was relatively low, attracting land from China Sea, China Resources. Seven real estate companies including Shangshekou participated in the auction after 257 rounds of bidding Sold at a 125% premium. Second, the Wenyu River plot won by China Resources Land is prominent. The Wenyu River plot contested by China Resources Land is close to the Beijing Runyuan project, where nearly 90% has been removed. The Wuhan Baishazhou plot obtained by Poly Development on September 11 also relies on the removal performance of about 70% of surrounding projects. Sales verification of existing projects has become an important basis for pricing new plots; third, projects with relatively manageable total price and volume are more in line with the current investment pace. The total transaction price is mostly within 1.5 billion yuan.
Table: Residential land premiums in core Tier 1 and 2 cities after the August 28 New Deal (8.31-9.27)
Data source: Middle Index Data CREIS
In terms of land acquisition enterprises, in the third quarter, the dominant position of leading central state-owned enterprises in the land market was further strengthened. After the August 28 New Deal raised the capital threshold, only leading enterprises with strong financial strength were basically able to participate in high total prices and high-threshold plots; at the same time, regional private enterprises remained active in the core domestic sector, and consortium land acquisition increased.
Among the leading central state-owned enterprises, in the third quarter, CNOOC successively acquired a number of core plots in Beijing, Shanghai, Shenzhen, and Xi'an: in July, it obtained the Jiuxianqiao plot in Chaoyang District, with a transaction price of 4.68 billion yuan; in August, it obtained the Nanmo land plot in Chaoyang District, with a transaction price of 8.4 billion yuan, and the “True Heart” composite plot in Shanghai's Putuo District at a base price of 15.02 billion yuan; in September, it also obtained the Laoximen plot in Shanghai's Huangpu District and the Xiangmihu plot in Shenzhen's Futian District, and a 40.0% premium in Xi'an Qujiang New Area Most of the land plots obtained in the warehouse are scarce resources for the core sector of the core city. China Resources Land, Poly Development, China Merchants Shekou, and Yuexiu Real Estate also maintained the pace of investment. China Resources won 8.30 billion yuan for the Wenyu River plot in Shunyi, Beijing, and Yuexiu used 2.48 billion yuan to fill the core sector in Tianhe District of Guangzhou. Meanwhile, Beijing cancelled three residential land sales in September, and cities such as Xi'an, Chengdu, and Fuzhou also terminated individual land concessions, and the land market's adaptation to the new sales system is gradually unfolding.
Furthermore, consortium land acquisition has become an important way for enterprises to share risk. The Daning plot in Jing'an District of Shanghai was contested by Xiangyu and the C&D Consortium for 7.05 billion yuan; the Sijing plot in Songjiang District was jointly acquired by Star Lion Investment and Guomao Real Estate; the Shiqiao plot in Gongshu District of Hangzhou was jointly contested by Zhongtian Mei and Haiwei Real Estate. The Wenyu River plot in Shunyi, Beijing also attracted a consortium of Jinyu and Maoyuan to participate in the auction. In the context of increasing pre-sale thresholds and lengthening capital occupation cycles, joint land acquisition will help share land payments and development investment, and integrate the capital and product advantages of all parties. It is expected that the future will continue to be an important model for enterprises to participate in land auctions in core cities.
The scale of land transactions continued to shrink in the third quarter of 2026, and land acquisition by housing enterprises was further concentrated on high-quality land plots in core cities. After the implementation of the New Deal on August 28, housing companies' overall pricing became more cautious. Land acquisition paid more attention to location, total price, development cycle, and certainty of removal. Only high-quality land in core cities remained competitive. Looking ahead to the fourth quarter, high-quality land in core cities will provide some support to the market; after Beijing and Shanghai first introduced implementation rules at the end of September, more city rules are expected to be followed. In a context where financial pressure on housing enterprises is still high, the prudent investment trend will continue. For housing enterprises, they should adhere to “fixed investment based on sales”, include capital costs corresponding to existing housing sales in investment estimates, give priority to plots with a controllable total price and a short development cycle, share financial pressure through joint land acquisition, etc., and pay more attention to product construction to meet market requirements after the sales system has been adjusted.
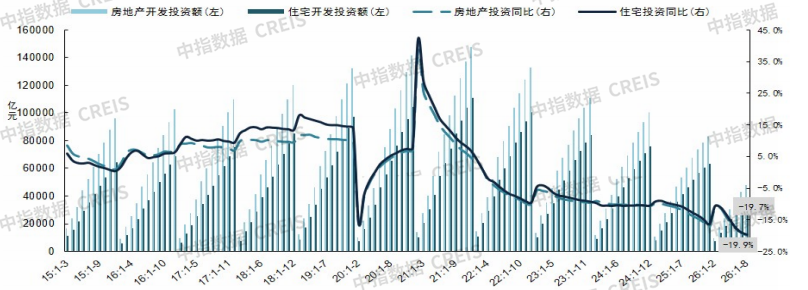
(4) Development investment: Real estate development investment decreased 19.9% year-on-year in January-August, and the decline increased
Figure: The cumulative investment in real estate and residential development and its year-on-year growth rate
Data source: National Bureau of Statistics, China Index Data CREIS
The year-on-year decline in real estate development investment increased. From January to August 2026, the country's real estate development investment was 4.8 trillion yuan, down 19.9% year on year. The decline was 0.7 percentage points higher than in January-July. Of these, investment in residential development was 3.7 trillion yuan, down 19.7% year on year. Short-term investment is still under great pressure.
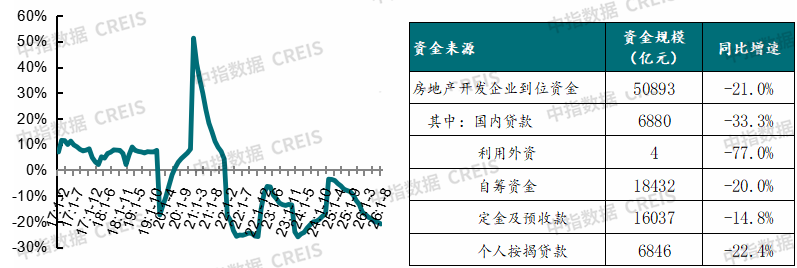
Figure: Comparison of the year-on-year growth rate of capital available to housing enterprises and the year-on-year growth rate of various funding sources from January to August 2026
Data source: National Bureau of Statistics, China Index Data CREIS
The year-on-year decline in funding available to housing enterprises increased. From January to August 2026, real estate development companies received 5.1 trillion yuan in capital, a year-on-year decrease of 21.0%. The decline was 0.7 percentage points higher than in January-July, and the corporate capital side is still under some pressure. Among them, domestic loans in January-August were 688 billion yuan, down 33.3% year on year; use of foreign capital was 400 million yuan, down 77.0% year on year; self-financing was 1.8 trillion yuan, down 20.0% year on year; deposit and advance payments were 1.6 trillion yuan, down 14.8% year on year; and personal mortgage loans were 684.6 billion yuan, down 22.4% year on year.
Part II: Forecast of China's Real Estate Market Trends for the Fourth Quarter of 2026
(1) Economic and policy environment: Domestic demand recovery still needs to be consolidated. Implementation rules for the reform of commercial housing sales systems in various regions will be implemented at an accelerated pace in the fourth quarter
On the macroeconomic side, in the first three quarters of 2026, the overall operation of China's economy remained stable, and industrial upgrading and new momentum development continued to show a good trend. However, the contradiction between strong domestic supply and demand is still prominent, and the foundation for economic stability and improvement still needs to be consolidated.
The gross domestic product grew 4.7% year on year in the first half of the year. The equipment manufacturing industry and the high-tech manufacturing industry maintained relatively rapid growth, and foreign trade performance was outstanding. On the demand side, in January-August, total exports of goods trade were 20.17 trillion yuan, up 14.6%; total retail sales of social consumer goods increased 1.1% year on year, retail sales of services increased 4.9%, and the consumer market remained stable; fixed asset investment fell 7.2% year on year, of which investment in real estate development fell 19.9%, and the investment side is still in the adjustment stage. In terms of prices, on average in January-August, CPI rose 0.9% year on year, PPI rose 2.0% year on year, and the price level rebounded moderately. However, the adverse effects of the external environment have deepened, the contradiction between strong domestic supply and demand is still prominent, and the foundation for economic stability and improvement still needs to be consolidated.
Currently, the recovery of domestic demand is still under some pressure. Insufficient effective demand is still an important constraint on further economic recovery. Improving domestic demand and adjusting the real estate market will still take time. Looking ahead to the fourth quarter, macroeconomic policy is expected to continue to maintain a positive orientation. Fiscal policy is expected to speed up the implementation of stock measures and the use of capital, and give full play to the effectiveness of “double” and “two new” policies. Monetary policy is expected to remain moderately relaxed to provide a relatively stable financing environment for the real economy.
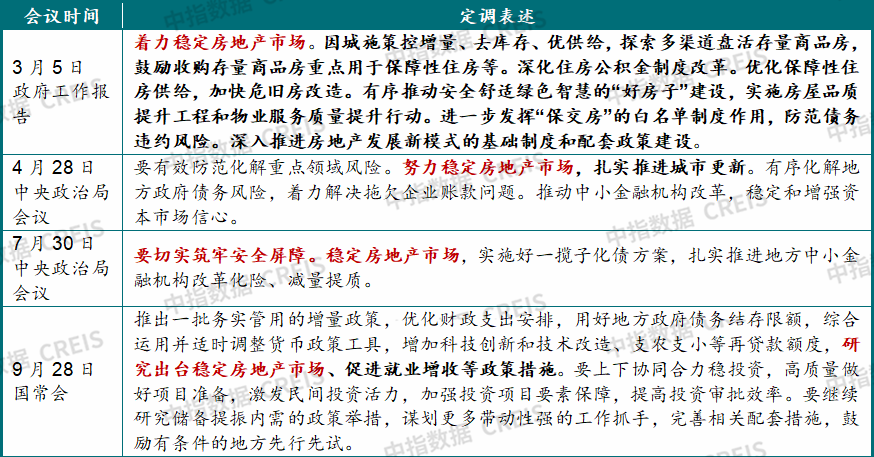
Table: Sorting out the contents of important meetings at the central level since 2026 on setting the tone of real estate
Source: Comprehensive compilation by the China Index Research Institute
In terms of real estate policy, in the third quarter of 2026, the central government continued to set the tone for “stabilizing the real estate market” and incorporated it into a higher-level framework. On July 30, the Politburo meeting of the Central Committee once again emphasized “stabilizing the real estate market”. This time, real estate was included in the “effectively building a safety barrier” section, which also highlighted the importance of stabilizing the real estate market in the current overall policy framework. At the National Standing Committee meeting on September 28, it was once again emphasized the introduction of policies and measures to stabilize the real estate market and promote employment income growth, indicating that stabilizing the real estate market is an important part of stabilizing the macroeconomy, and short-term policies will continue to be strengthened.
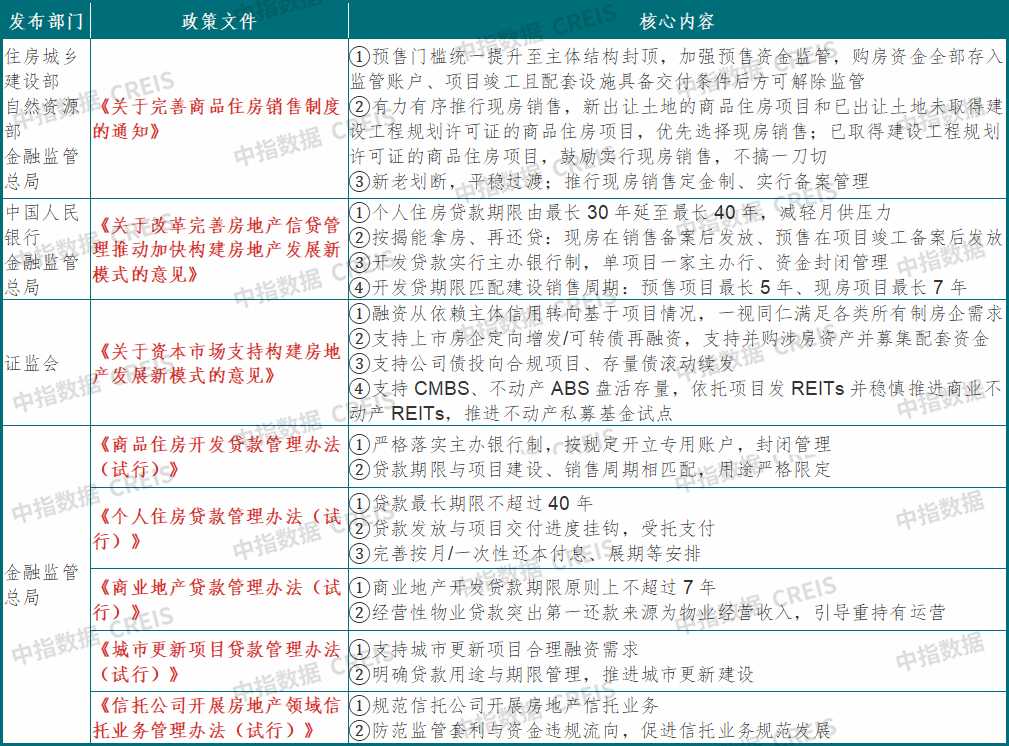
The reform of the real estate system is in place, and every effort is being made to push forward the implementation of the three basic systems. On August 28, various departments such as the Ministry of Housing and Construction, the Ministry of Natural Resources, and the General Administration of Financial Supervision issued a “1+2+5” policy document to comprehensively restructure basic systems such as real estate development, financing, and sales, and accelerate the construction of a new model for real estate development. Among them, the project company system addresses “who is the independent implementing entity of the project”, and the existing housing sales system solves the “problem of paying with one hand and delivering housing with one hand”. The three are being promoted in an integrated manner. Judging from the core changes in policy, the first is the reform of the sales system to raise the pre-sale threshold, strengthen financial supervision, and promote the sale of existing homes through classification. The second is credit management reform, and comprehensive optimization of personal housing loans and development loans. The third is capital market financing reform to restructure the financing model. On September 18, the Ministry of Housing and Construction made it clear at a press conference that real estate has undergone “two transformations”. One is that the relationship between supply and demand in the real estate market has changed significantly, and the other is that real estate has entered an era of stock. From the perspective of the new model of real estate development, the Ministry of Housing and Construction clarified the meaning of “1234” for the first time. “1” firmly grasps the foundation for people to settle down; “2” is to improve the two systems of security and market; “3” is the three systems of project company system, host bank system, and existing housing sales system; and “4” promotes the linkage of the four elements of “human real estate money.” At the same time, the Ministry of Housing and Construction emphasized that it will “make every effort to promote the implementation of the three basic real estate systems.” The current policy leaves some room for local city-specific policies, and the exact implementation rules are yet to be clarified.
Table: Main contents of the August 28 policy document
Source: Comprehensive compilation of the China Index Research Institute, CI Buddy
In terms of activating demand, first, continue the city-specific policy to meet the demand for home purchases. The “Fifteenth Five-Year Plan” for Expanding Consumption clearly cleans up and optimizes unreasonable restrictive measures in Chapter 7, “Strengthening and Improving the System Mechanism to Promote Consumption,” and states that “all regions are supported to adjust and optimize real estate policies according to urban policies to better meet the rigid and improved housing needs of residents.” Second, deepen the reform of the Provident Fund system and more strongly support housing consumption throughout the cycle. On August 18, the State Council officially issued the “Decision of the State Council on Amending the 'Regulations on the Administration of Housing Provident Funds'”. After the revision, the housing provident fund withdrawal situation was greatly expanded. On the basis of the original situation of buying, building, renting, etc., content such as renovating self-occupied housing and paying property fees was added. At the same time, the coverage of the system was expanded, making it clear that people with flexible employment can voluntarily deposit housing provident funds. The functional positioning of the Provident Fund was extended from mainly supporting housing purchases to supporting housing consumption, and extended to the entire housing life cycle.
In terms of optimizing supply, the first is to promote the construction of “good houses.” On September 18, the Ministry of Housing and Construction proposed at the press conference of the Information Office of the State Council that one of the five goals for high-quality development of the housing and construction industry during the “15th Five-Year Plan” period is to achieve “improving people's living standards”; the key is to build “good houses.” Second, increase the vitality of the existing land inventory. On September 22, the Ministry of Natural Resources made it clear at the press conference that resource utilization during the “15th Five-Year Plan” period will achieve three transformations, namely, from excessive reliance on incremental land in the past to revitalizing stock land, from resource concessions to resource operation, from pursuing current income from land concessions to combining current income with expected operating income; and clarifying implementation paths in the three aspects of planning coordination, land policy, and resource allocation, including adhering to regional coordination and enhancing land use compatibility, optimizing the pace of land price payment, land use transition period and temporary use policies to reduce early land acquisition costs, and improve the physical land market Promote the hierarchical establishment of rights and combined supply, and improve the land reserve system to achieve fixed storage and supply requirements.
In response to urban renewal, the central government repeatedly emphasized promoting urban renewal with high quality in the third quarter. On July 15, during his visit to Shanghai, General Secretary Xi Jinping emphasized that promoting urban renewal with high quality is an important gripper for urban modernization; on September 8, the State Council held a special study. Premier Li Qiang emphasized that “urban renewal has become an important gripper for urban work at this stage” and “insist on putting people first and promoting urban renewal with high quality.”
At the end of August, the General Administration of Financial Supervision and the Ministry of Housing and Construction jointly issued the “Urban Renewal Project Loan Management Measures (Trial)”, which first established exclusive loan types and special credit systems for urban renewal, making systematic regulations from project entry, loan use, and repayment sources to fund closure management to help all regions promote urban renewal with high quality; in early September, the Ministry of Housing and Construction solicited public comments on the “Urban Renewal Plan Preparation Standards (Draft for Comments)” and proposed the establishment of a three-level preparation and implementation system for “Special Planning-Area Planning-Project Implementation Plan” to provide a unified technical basis for all regions; on September 18, the Ministry of Housing and Construction At the press conference, it was clear that the “Fifteenth Five-Year Plan for Urban Renewal” has determined specific tasks and that the key is implementation; on September 22, the Ministry of Natural Resources emphasized that revitalizing existing land will be used to promote urban renewal more effectively and effectively. It is expected that subsequent supporting policies such as urban renewal plans, land, taxation, and finance will be further coordinated and improved to promote the actual implementation and effectiveness of the policies.
Figure: Frequency of city-specific policies in various regions since 2024
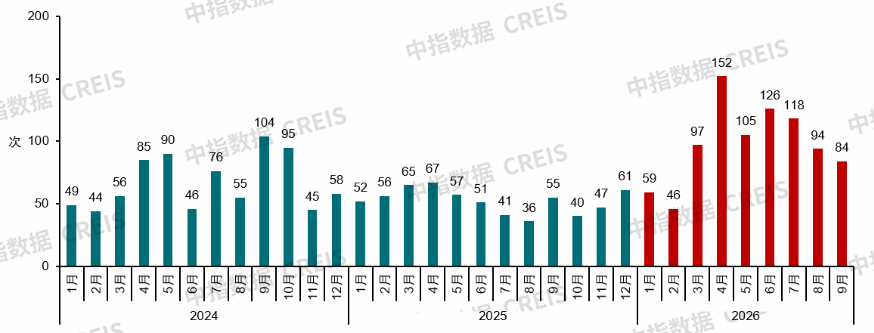
Table: Comparison of the frequency of introduction of major policy types since 2026 (as of 9.28)
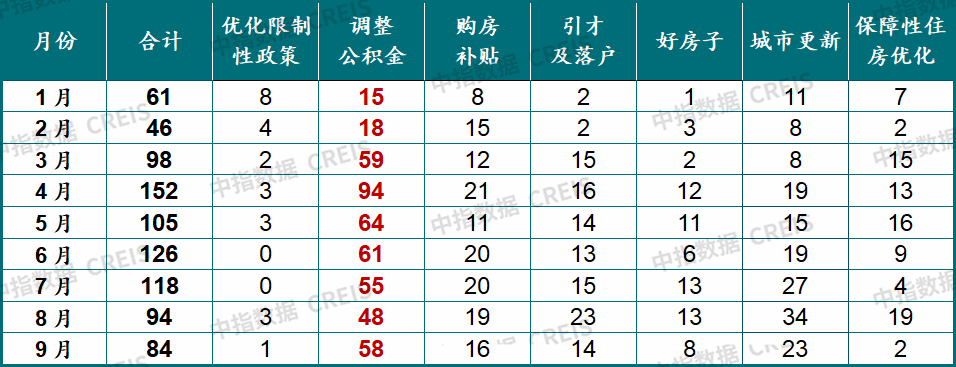
Note: A single policy in the Total column may cover multiple dimensions.
Source: Comprehensive compilation by the China Index Research Institute
At the local level, according to monitoring by the China Index, as of September 28, the country had introduced more than 880 real estate-related policies, of which the country introduced more than 290 real estate-related policies in the third quarter, continuing the trend of high-frequency implementation of policies in the first half of the year. Specifically, local policies mainly focus on exploring existing housing sales, optimizing restrictive policies, adjusting provident fund policies, issuing housing purchase subsidies, revitalizing stock of houses, building “good houses”, and landing supporting policies for urban renewal.
Many provinces and cities are exploring existing housing sales and raising the pre-sale threshold, and supporting rules have yet to be implemented. On September 24, Beijing took the lead in implementing rules, clarifying that projects that acquired land before 8.28 but did not obtain a work permit are implemented in principle according to the new pre-sale policy. At the same time, certain flexible space has been set for each district, and certain transition period arrangements have been set. It is proposed that if each district government ensures that it can be completed and delivered on time, it can be pre-sold according to the original pre-sale conditions before the end of 2027, but the mortgage loan conditions will be implemented in accordance with the new policy, making it clear that for projects announced after 8.28, land payments can be made in less than 30 days 50% of the total price, paid within 2 years, not counting interest. Shanghai quickly followed up and introduced implementation rules on September 28. The general framework is basically the same as Beijing. The pre-sale management of land that has been announced for sale has been made more detailed and clear. The deposit collection ratio is no more than 3% of the total purchase price. It is clear that work regulations can be applied for based on land concession contracts, which helps speed up the construction progress of the project. Guangzhou released a draft for comments on the “15th Five-Year Plan” housing development plan in July, which states that during the “15th Five-Year Plan” period, land plots from various regions will be selected to carry out pilot existing housing sales projects; previously, Guangzhou's Nansha District introduced a new property market policy, which clearly adopted the existing housing sales model. The land concession payment period can be extended up to 2 years, and the first existing housing sales plot will be obtained at the reserve price of construction in Nansha at the end of August. At the beginning of September, Henan introduced “Certain Measures on Coordinating the Promotion of Controlling Incremental Inventory and Improving Supply and Stabilizing the Real Estate Market”, which clearly controls the pace of subsequent pre-sale license approval for real estate projects that are pre-sold in batches but have a low removal rate, further raise the pre-sale threshold by comprehensively considering market supply and demand, and encourage the implementation of existing housing sales. Changchun solicited public comments on the “Notice on Certain Measures to Stabilize the Real Estate Market (Draft for Comments)”, clarifying that new residential land can be sold in one go or in installments, and that planning permits can be applied for and developed according to the proportion already paid; Dongguan issued the “Notice on Matters Relating to Implementing Segmented Acceptance of Housing Construction Projects (Draft for Comments)”, which intends to support batch inspection and delivery. Furthermore, since the 8.28 policy, existing housing sales have been clearly implemented in newly listed land plots such as Xiamen and Lishui, but the current reform of the pre-sale system and the specific implementation rules for existing housing sales still need to be further implemented and improved. It is expected that after key cities take the lead in implementing the relevant rules, more cities will follow up at an accelerated pace.
In terms of activating demand, in the third quarter, various regions mainly implemented policies in four areas: fine-tuning restrictive policies, optimizing provident fund policies, issuing housing purchase subsidies, and promoting housing “trade-in”. Specifically:
First, core cities have refined and adjusted restrictive policies. In the third quarter, Beijing, Shanghai, and Haikou successively relaxed restrictive policies. On August 7, Beijing made it clear that households that are not registered in the city can purchase commercial housing within the 5th Ring Road, and that the social security/personal tax period requirement was reduced from 2 years to 1 year; on August 20, the minimum down payment ratio for a second home loan outside the Shanghai Outer Ring Road was lowered from “no less than 20%” to “no less than 15%”; on September 5, after settling in Haikou clearly, they can enjoy the same housing purchase eligibility for residents of the province without social security/personal tax payment requirements. The calculation range for the number of units purchased was narrowed from the province to the whole city of Haikou. Buy 1 set in bulk.
Second, the Provident Fund policy continues to gain strength. Since this year, various regions have introduced more than 470 provident fund optimization policies, of which more than 160 were introduced in the third quarter, which is the most frequent demand-side policy tool in various regions. The optimization of local provident fund policies mainly focuses on increasing loan amounts, expanding the scope of withdrawal and use, optimizing deposits for people with flexible employment, and deposits for offsite workers. After the revision of the Provident Fund management regulations, many places followed up and supported the withdrawal of provident funds for use in decoration, property fees, etc. In terms of increasing loan amounts, in the third quarter, Beijing followed up raising the maximum amount of provident fund loans. The maximum deposit amount for both husband and wife was raised to 2.4 million yuan. After adding the floating policy, the maximum loan amount can be loaned to 3.4 million yuan. At the same time, the mechanism linked to the loan amount and deposit period was optimized. Now, when depositing for 5 years and 1 month, they can apply for the maximum amount, effectively reducing the cost of housing purchases for residents. In terms of expanding the scope of extraction and use, the main expansion directions in the current implementation policies in various regions include housing decoration, property fees, housing purchase taxes, parking spaces, renewal of old housing, etc. Beijing supports renovation extraction, up to 250,000 yuan per unit; Shanghai supports collection of deeds, parking spaces, and storage rooms; and Guangzhou plans to support renovation, property fees, and renewal of old housing. In terms of optimizing the savings of flexible workers and offsite workers, Xiamen provides account opening allowances and deposit subsidies for flexible workers; Nanjing optimizes offsite loans, so that all provident fund depositors from all over the country can apply for provident fund loans when buying a home in Nanjing; Guangzhou plans to liberalize national home purchase withdrawal restrictions, and can withdraw Guangzhou Provident Fund account balances when buying homes in cities across the country.
Third, housing purchase subsidies will continue to be provided to increase the inclination for specific families. Housing purchase subsidies are distributed in many places in conjunction with marriage and childbearing policies. For example, Wangcheng District of Changsha grants housing purchase subsidies to families with multiple children, 30,000 yuan/unit for families with two children, and 50,000 yuan/unit for families with three children or more. Many places have increased subsidies in combination with talent promotion. For example, Guangzhou's Huangpu District issues housing tickets for talents, which are distributed in installments of 100,000 yuan for undergraduate students, 150,000 yuan for master's degrees, 250,000 yuan for doctorates, and 300,000 yuan for post-doctoral students. Increasing housing “trade-in” subsidies is also an important direction for strengthening housing in many places now. In August, the Shanghai New Deal introduced a “trade-in” home purchase loan subsidy. Buyers who sell second-hand housing in the city and buy a new home outside the outer ring will be subsidized at 1% of the total new home loan amount, up to 50,000 yuan per unit for a single unit, while optimizing the original “trade-in” subsidy policy to sell second-hand housing in the outer ring and buy a new home outside the outer ring. The two can be combined, that is, “sell an old house in the outer ring and buy a new house outside the outer ring.” Families can receive up to 80,000 yuan in allowances. In addition, some cities pay subsidies in the form of interest discounts. For example, Dalian grants interest allowances to families using the Provident Fund to buy two housing units. The subsidy ratio is 15% of the actual interest expenses, and the subsidy period is 3 years, calculated monthly and paid quarterly; Chengdu grants 20% interest subsidy for the purchase of newly built commercial housing with provident fund loans, and the amount of the subsidy does not exceed 25,000 yuan.
Fourth, many cities continue to buy second-hand housing to promote “trade-in” housing. Since this year, Shanghai and Guangzhou have continued to push state-owned platforms to buy second-hand properties. In February, Shanghai launched a pilot project to acquire second-hand housing for affordable housing in Xuhui, Jing'an, and Pudong, giving priority to the acquisition of second-hand properties within the inner ring, before 2000, with a single construction area of less than 70 square meters and a total price of no more than 4 million yuan, and expanded the pilot to 8 central urban areas. By the end of July, a total of 551 second-hand housing units had been acquired; on August 20, the Shanghai New Deal once again emphasized speeding up the acquisition of second-hand housing in central urban areas. As of September 20, Xuhui District had acquired a total of 486 units, and the first one landed in early September. In May, Guangzhou launched a pilot project to acquire second-hand housing within the Huancheng Expressway, with a total price of 3 million yuan, a construction area of less than 70 square meters. State-owned enterprises at the urban level accelerated the acquisition process. By the end of July, more than 2,100 groups had been registered to sell second-hand housing units, and 111 units had been sold.
In terms of optimizing supply, in the third quarter, all regions mainly advanced in terms of collecting stored commercial housing, collecting stored land, promoting the construction of “good houses”, and revitalizing the existing industrial and commercial land use. Specifically:
First, many places are promoting the acquisition of existing commercial housing and speeding up inventory removal. In the third quarter, many places such as Henan, Tianjin, and Shandong clearly purchased existing commercial housing for affordable housing in their policies. Among them, Henan clearly “made good use of affordable housing reloans and local government special bonds to buy stock commercial housing.” More colleges and universities are following up on the acquisition of existing commercial housing for use as student housing. Jiangsu issued the “Provincial Financial Assistance Program for the Three-Year Campaign to Improve the Quality and Expansion of Student Dormitories in Provincial Colleges and Universities” to support the promotion of purchases in regions with low housing prices such as Xuzhou, Huai'an, and Lianyungang. The provincial financial subsidy is 30% to promote student dormitories to be used as student housing; Shenzhen University plans to spend 530 million yuan to purchase commercial housing for use as student housing. In terms of commercial housing, according to incomplete statistics from the China Index Research Institute, as of September 28, various regions had successively issued a total of over 13.5 billion yuan of special bonds to purchase stock commercial housing, with over 23,000 units and a construction area of more than 1.9 million square meters. Since 2026, the issuance of related special bonds has accelerated slightly, with a total issuance of 7.6 billion yuan, of which Hunan and Guangdong all issued more than 2 billion yuan this year.
Second, continue to promote the acquisition of existing land, and maintain a strong level of land collection with special debt. According to incomplete statistics from the China Index Research Institute, as of September 28, all parts of the country had announced plans to use special bonds to collect and recycle more than 6,000 cases of idle land, with a total land area of over 310 million square meters, with a total amount exceeding 810 billion yuan. The special bonds had already been issued, accounting for about 58%. Among them, since 2026, Chongqing, Guangdong, Fujian and other provinces and cities have distributed more than 175 billion yuan, and in August, local distribution accelerated, and issued more than 47 billion yuan in a single month. Collecting and storing land may still be an important measure to remove inventory and improve the relationship between supply and demand in the market in the fourth quarter.
Third, promote the construction of “good houses.” In the third quarter, various regions continued to promote the construction of “good houses”. Shandong issued the “Notice on Implementing Housing Quality Improvement Projects to Accelerate the Construction of “Good Houses”, clarifying “good house” construction standards and supporting affordable housing to prioritize the construction of “good houses”; Hefei issued the “Hefei City Action Plan to Promote the Construction of “Good Houses” to systematically carry out three major actions to guide the quality of newly built commercial housing, improve the quality of affordable housing, and renew and renovate existing housing, and indicated that the first batch of “renewal” pilot projects for existing housing will be launched in 2026 to strive for the renovation of 3,000 dilapidated and dilapidated houses There are 63 old neighborhoods.
Fourth, revitalizing the existing industrial and commercial land and housing use is one of the keys to revitalizing the stock, and supporting policies continue to be put in place. Supporting policies were introduced at an accelerated pace in various regions in the third quarter. Shanghai issued the “Guiding Opinions on Renewal of Land Use Rights for Industrial and Commercial Projects in Shanghai (Trial)”, establishing the principle of “renewal as the norm, no renewal as an exception, and continuing according to enterprise needs”, clarifying the renewal process and price calculation for industrial and commercial land, and clearly formulating corresponding renewal rules for projects to be issued with REITs. Nanjing issued the “Implementation Opinions on Implementing Market-based Land Factor Allocation Reform to Promote Intensive and Efficient Use of Land”, which clarifies that planning indicators such as floor area ratio, height limit, and green area ratio of existing industrial land can be directly processed, and that original rights holders of inefficient land use can invest in land prices and cooperate with new investors to revitalize the existing land factors. Yunnan, Tianjin and other places have clearly strengthened the revitalization and utilization of existing commercial housing and inefficient buildings. For example, Tianjin encourages the use of various types of affordable housing and talent apartments.
Furthermore, many provinces and cities have been intensively implementing the “15th Five-Year Plan” and supporting policies have continued to be improved. In the third quarter, local authorities introduced more than 80 policies related to urban renewal. Fujian, Hubei, Sichuan, Jilin, Yunnan, Qinghai, Anhui and other places introduced or prepared “15th Five-Year Plan” urban renewal plans. Sichuan made it clear that in the next five years, 8,000 old urban neighborhoods will be renovated, 420 urban villages will be renovated (100,000 households), 15,000 elevators will be installed, and 50 provincial key areas will be built. Beijing solicited public comments on the “Beijing Urban Sub-Center (Tongzhou District) Urban Renewal Plan for the “15th Five-Year Plan”. It is planned that by the end of the “15th Five-Year Plan”, annual investment in urban renewal will reach 30% of the total fixed investment amount; Shaanxi issued the “Shaanxi Provincial “Urban Renewal Loan” financial interest rate discount implementation plan to provide financial interest rate support for six major eligible urban renewal areas, including the renovation and upgrading of infrastructure and public service facilities in old neighborhoods, factories, and residential supporting facilities. Furthermore, promoting the demolition and reconstruction of old housing is also one of the local key grippers for promoting urban renewal. In the third quarter, Hunan, Xiamen and other places issued supporting independent renewal of old neighborhoods and old housing. As supporting policies continue to be improved, urban renewal work is also expected to accelerate in various regions, providing greater support for stabilizing the real estate market and stabilizing investment.
Overall, real estate continued the policy tone of “stabilizing the market” in the third quarter, and a series of documents on real estate system reform were implemented, speeding up the construction of a new model for real estate development. At the same time, the reform of the housing provident fund system was deepened to better support housing consumption throughout the cycle. Local policies on both sides of supply and demand remain introduced at a high frequency, and various tools are used comprehensively to promote the release of housing demand. Looking ahead to the fourth quarter, the core focus of the policy will shift to the refinement and implementation of supporting policies related to real estate system reform. Early top-level system arrangements will gradually be transformed into operational implementation rules, including installment payment of land concessions, conditions and procedures for disbursement of pre-sale funds, and various index requirements for completion and acceptance. Clarifying policies and rules in various regions will also enhance market predictability and stabilize market expectations.
Currently, real estate has entered an era of stock. In the future, while regulations continue to be put in place, it is expected that both supply and demand policies will continue to work together to stabilize the market. On the demand side, interest rates on provident fund loans are expected to be lowered. All regions are expected to accelerate the adjustment and optimization of provident fund policies, such as further broadening the use of withdrawals, expanding deposit coverage, and increasing loan amounts; restrictive policies in core cities such as Beijing, Shanghai, and Shenzhen still have room for adjustment, and more cities are expected to stimulate reasonable housing demand by combining housing “trade-in” housing and increasing housing purchase subsidies.
On the supply side, it is expected that more policies will focus on revitalizing stocks, work related to collecting stored commercial housing and land stocks will continue, and more cities will follow up on policies to revitalize existing industrial and commercial land use housing, such as introducing industrial and commercial land renewal policies and supporting inefficient building renovation.
Furthermore, loan policies for urban renewal projects and stock land support policies have been implemented at an accelerated pace, and supporting policies related to urban renewal are expected to continue to be improved in the future.
(2) Market trends: The bottoming trend continued in the fourth quarter, and investment and commencement of construction were under pressure in the short term
Since the third quarter, the overall real estate market has continued to bottom out, and structural characteristics are still obvious. In January-August, the sales area and sales of newly built commercial housing across the country decreased by 12.1% and 13.0%, respectively; the area of online signing for second-hand housing transactions increased 10.6% year on year, and the share of stock housing in transactions increased further. On the supply side, investment in real estate development and new construction area decreased by 19.9% and 24.8%, respectively; at the end of August, the area for sale of commercial housing fell 1.1% year on year, and the inventory scale continued to decline from a high level.
Looking ahead to the fourth quarter, the market bottoming trend is expected to continue. The direct impact of the 8.28 New Deal on the short-term transaction side is limited. The sales side is still dominated by existing factors, and “good cities+good houses” still have market opportunities; the commencement of construction and the investment side still depend on the decline in land acquisition in the early stages and the decline in the scale under construction, and it is expected that the trend of low adjustment will continue. Looking at the medium term, the impact of the August 28 New Deal by lengthening the capital occupation cycle and changing the land acquisition and investment behavior of housing enterprises will gradually become apparent starting in 2027. The peak land supply performance at the end of the year and the implementation of local rules are an important observation window. In the long run, the accelerated improvement of the basic system of the industry is conducive to optimizing the market supply structure and promoting the smooth transformation of the industry.
1. Sales volume and price: The impact of the 8.28 New Deal on short-term sales is limited, and volume and price are expected to continue to bottom out in the fourth quarter
Left: Trends in residents' willingness to buy homes
Right: Main influencing factors limiting homebuyers' entry into the market (multiple choices)
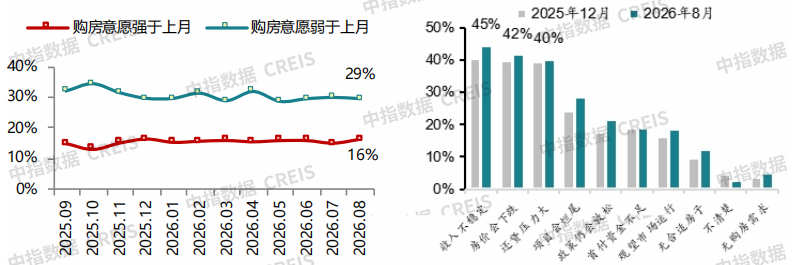
Data source: Middle Index Survey, Middle Index Data CREIS
Looking at demand expectations, the China Index survey data shows that the percentage of residents who were more willing to buy homes in August was 16% than last month. The overall level remained stable during the year, but the absolute level was still low; unstable income, concerns about falling housing prices, and high pressure to repay loans were still the main factors limiting residents' entry into the market. The 8.28 New Deal enhances the certainty of new home delivery by raising the pre-sale threshold and promoting sales of existing homes, and helps gradually restore the trust of buyers. This is a slow variable, and it is difficult to directly translate into transactions in the short term. The release of demand still depends on further improvements in employment, income, and housing price expectations.
Judging from market performance, core city transactions have maintained a certain level of activity since September. Market popularity has rebounded from the traditional off-season in July and August, but restoration mainly focuses on high-quality sectors and projects in core cities, and it will still take time for the transaction scale to fully recover. Looking at the transaction structure, second-hand housing sales continued to grow year on year, and the characteristics of the shift in residents' demand for home purchases to the stock market are becoming more and more obvious. On the price side, the relative stability of new housing prices is due more to the structural drive of high-quality real estate and “good house” projects entering the market in core cities; recently, some urban projects have taken steps such as taking back discounts and adjusting building price differences, but there are still few projects that directly raise sales prices, and there is still no general price increase trend. Some stock projects are still exchanging price for volume, and the game between buyers and sellers in the second-hand housing market continues.
Looking ahead to the fourth quarter, the direct impact of the 8.28 New Deal on short-term transaction volume and price is relatively limited. The market is still dominated by established factors. The traditional peak season combined with the lower base of the same period last year and the entry of quality improvement projects in core cities will provide some support for new housing sales. The sales area of newly built commercial housing across the country is expected to drop by about 10% throughout the year. In terms of price, high-quality projects support the overall stability of new housing prices; the scale of second-hand housing listings is still relatively high, and prices may continue to adjust in the short term.
In the medium term, the impact of the New Deal on the sales side will be transmitted more through the pace of supply. Starting in 2027, its impact on new supply will gradually deepen. The slowdown in the pace of new supply will help improve the relationship between supply and demand in the short term and provide some space for the elimination of stock projects, but if supply contraction continues, it may also limit the subsequent recovery in the sales scale of new homes.
2. Construction trend: The reduction in land acquisition in the early stages continues to be transmitted, and new construction starts in the fourth quarter are expected to maintain a low level of operation
Figure: Year-on-year changes in the cumulative land (residential+commercial) transaction area, and commercial housing sales area across the country
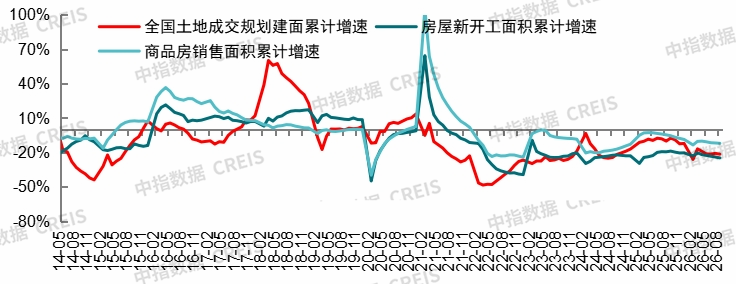
Data source: National Bureau of Statistics, China Index Data CREIS
From January to August 2026, the country's new housing construction area was 299 million square meters, a year-on-year decrease of 24.8%. The decline continued to expand compared to the first half of the year, and overall, it is still in the adjustment channel. Looking at the influencing factors, first, the land market continued to shrink, with the land (residential+commercial) transaction area falling 21.6% year on year in January-August, and the decline in land transactions in the early stages continued to be transmitted to the construction side; second, the financial situation of housing enterprises still needed to be improved. The capital received in January-August fell 21.0% year on year, and there was pressure on both sales repayment and financing side; third, although commercial housing inventories continued to decline from a high level, it still took time for companies to absorb the total amount of inventory.
Looking ahead to the fourth quarter, the start of new construction will still mainly depend on the scale of land acquisition in the early stages and the corporate capital situation. Under the influence of land shrinkage, the overall operation is expected to remain low. The August 28 New Deal transition period arrangement may provide some support for short-term construction. For example, the Beijing-Shanghai implementation rules specify that projects that have acquired land before August 28 but have not obtained construction permits can still apply for pre-sale according to the original pre-sale conditions until the end of 2027 after meeting the conditions and filing with the municipal department. It is expected that various regions will also generally set up similar arrangements. In order to lock in the original pre-sale conditions, the pace of commencement of construction on some of the land in hand may accelerate. In the medium term, the New Deal raised the pre-sale threshold until the main structure was capped, mortgage loans were delayed until completion and filing, and the project capital occupation cycle was significantly lengthened. Land acquisition by housing enterprises is expected to shrink after the New Deal, and the impact on new construction starts in 2027 may be quite obvious.
3. Investment trends: Investment continued to adjust in the fourth quarter, and the impact of the New Deal on land prices and land purchase costs will gradually become apparent
Figure: Year-on-year trend of land (residential+commercial) concession funds, construction area, and real estate investment across the country
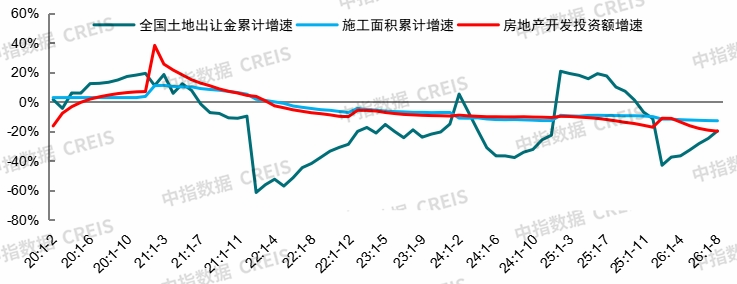
Data source: National Bureau of Statistics, China Index Data CREIS
From January to August 2026, the country's real estate development investment fell 19.9% year on year, and the decline continued to expand slightly since the third quarter. In terms of composition, on the one hand, housing construction area fell 12.8% year on year in January-August, and the new construction area fell 24.8%. The shrinkage in stock was compounded by slow continuation of new projects, and construction project investment declined accordingly; on the other hand, in January-August, the national land concession fund (residential+commercial) fell 19.7% year on year, which is expected to continue to drag down subsequent land purchase cost performance.
Looking ahead to the fourth quarter, development investment is still mainly dependent on changes in the scale of construction and the delayed transmission of land transactions in the early stages. The pace is expected to continue the adjustment trend since the third quarter. In the medium term, after the August 28 New Deal, land acquisition by housing enterprises became more cautious, and land market price expectations tend to be rational; at the same time, the Beijing and Shanghai rules all make it clear that land prices can be paid in installments without interest, which helps ease the pressure on housing enterprises to make centralized payments, but it also causes land purchase costs to be spread over a longer period of time, and the support of land transactions for current investment weakens accordingly. These effects may gradually become apparent starting in 2027. It is worth noting that the end of this year is an important observation window for changes in the ability and intention of housing enterprises to acquire land. November-December was the peak of traditional land supply. In the past three years, residential land concessions in 300 cities accounted for more than one-third of the year. New local regulations will also be introduced within the year. Policies such as minimum delivery units, installment payment of land payments, and transition period arrangements will directly affect the investment capacity and will of enterprises, which in turn will affect the scale of investment in 2027 and beyond.