


Five Below (FIVE) has added longtime Ulta Beauty finance chief Scott Settersten to its board and audit committee, an appointment that puts a seasoned retail and accounting voice closer to the discount retailer’s oversight.
The Five Below share price has pulled back over the past month, with a 30 day share price return of down 5.7% and a 7 day move that is also weaker, although the 90 day share price return of 26.8% points to momentum that built earlier in the summer. At a recent price of US$228.0, investors now see a 1 year total shareholder return of 46.8% and a 3 year total shareholder return of 44.7%. This frames the board appointment as another development arriving after a period of strong long term performance rather than a sudden reset in sentiment.
Scan how Five Below fits into the wider retail opportunity set by comparing it with our curated list of resilient value retailers in the 32 high quality undervalued stocks.
After a sharp run over the past quarter and a softer patch this month, Five Below now trades well below the average analyst target yet above one intrinsic estimate. Where does a fair baseline really land?
Most Popular Narrative: 27% Undervalued
Against the last close at $228.0, the most followed fair value estimate of $310.95 implies a sizable valuation gap that leans in favor of Five Below, with the discount rate in that framework set at 8.53%.
Five Below's commitment to providing extreme value and trend-right products at low price points is associated with broad-based transaction growth, especially as consumers across demographics become increasingly value-focused due to persistent economic pressures. This is expanding the store traffic and addressable market, which may support higher revenue and potential sustained comp sales growth.
See why 15 investors see Five Below as 27% undervalued.
Result: Fair Value of $310.95 (UNDERVALUED)
Still, the bullish Five Below story can be knocked off course if tariffs bite harder into gross margins, or if rapid store openings dilute sales productivity.
Find out about the key risks to this Five Below narrative.
Another View: Five Below Through The Earnings Multiple
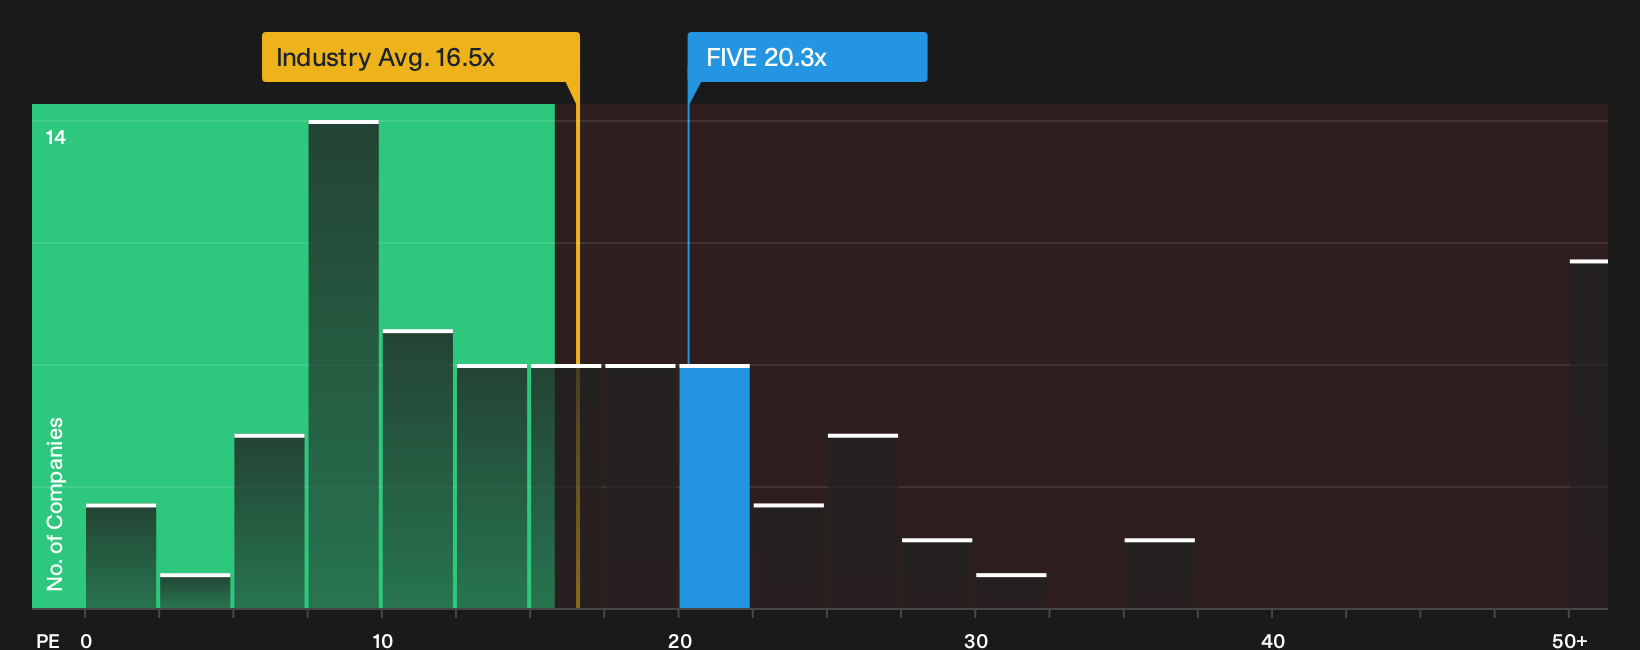
The narrative fair value of $310.95 paints Five Below as 27% undervalued, but the current P/E of 20.3x tells a tougher story. That ratio screens richer than the US Specialty Retail industry on 16.1x, the peer average on 19.4x, and even the fair ratio of 14.4x that our model suggests the market could lean toward over time.
For anyone weighing upside against valuation risk, those gaps hint at a stock that already bakes in a lot of good news. The question is simple. Does your conviction in Five Below's long term earnings power justify paying a premium today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Five Below so far? If you want to move faster than the crowd and base your call on hard evidence, start with both sides of the story and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Five Below?
Do not stop your research at Five Below when there are other angles you can test in minutes with the Simply Wall St stock screener.
- Zero in on potential value plays by reviewing our 32 high quality undervalued stocks that pair solid balance sheets with appealing valuations.
- Strengthen your focus on resilience and capital preservation by scanning a 30 resilient stocks with low risk scores that score well on our risk checks.
- Get ahead of the crowd by tracking 16 high quality undiscovered gems before broader attention and liquidity catch up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com