


- Marsh & McLennan Companies recently introduced Archer by Marsh, a service that helps asset managers and life and annuity insurers set up and run reinsurance operations using shared infrastructure while keeping full ownership and control of their vehicles.
- The launch relies on Marsh & McLennan Companies' combined actuarial, capital, risk and regulatory capabilities to build tailored reinsurance entities, which could affect how clients structure capital intensive insurance and investment products.
- We will now look at how Marsh & McLennan Companies' Archer by Marsh offering could influence the broader investment narrative for the business.
Scan how Marsh & McLennan Companies is reshaping insurance infrastructure, then compare it with other financials on the move using the list of solid balance sheet and fundamentals (25 results)
Marsh & McLennan Companies Investment Narrative Recap
To own Marsh & McLennan Companies, you effectively need to believe that complex risk, regulation and benefits needs keep pulling clients toward its broking and consulting platforms, even while insurance and reinsurance pricing pressure bites. Archer by Marsh fits that belief, since it aims to keep the franchise relevant to asset managers and life carriers that are rethinking capital intensive products.
The near term swing factor still looks like execution on efficiency programs and AI tools to offset softer reinsurance markets and margin pressure after recent litigation costs. Pricing weakness in property and reinsurance remains the biggest operational risk if volume, new solutions like Archer and cost savings do not compensate.
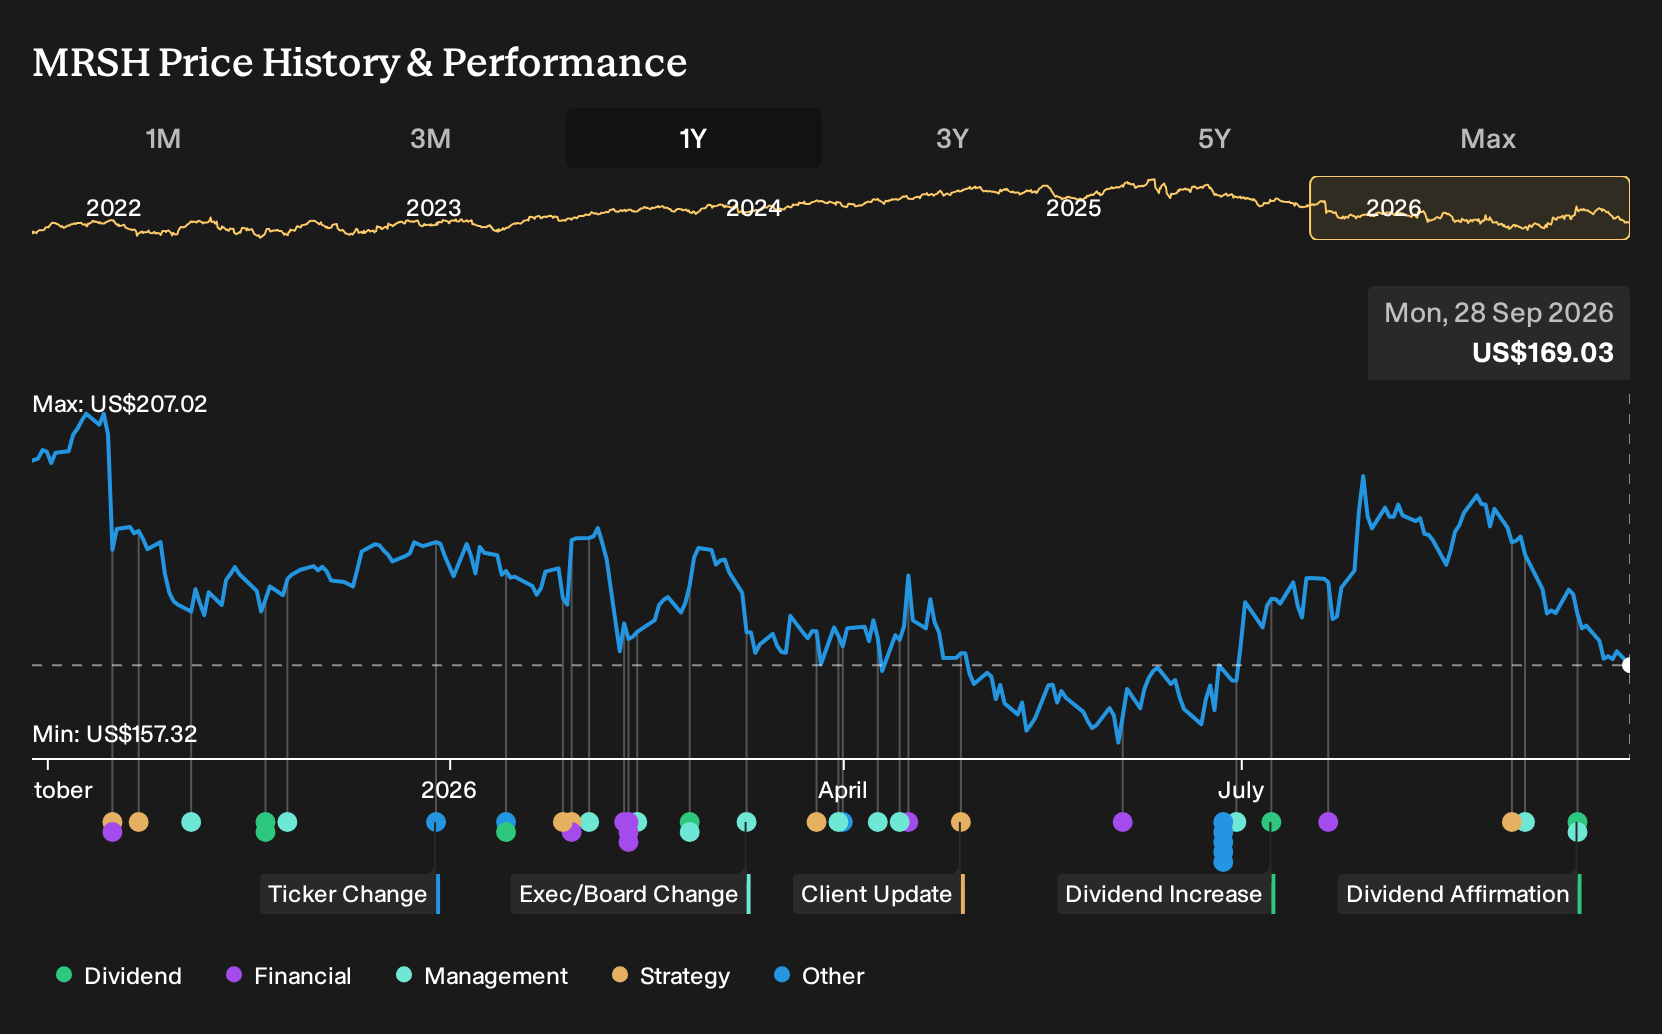
The dividend affirmation on 16 September 2026 ties directly into that story. Marsh & McLennan Companies declared a quarterly payout of US$0.99 per share. This sits alongside commentary that the stock offers a 2.34% yield and is considered by some models to be trading below estimated cash flow value.
For you as a shareholder, that cash return matters only if the business can keep funding it while investing in areas such as AI, Archer by Marsh and mid market agency expansion. Any prolonged hit to broking commissions from softer pricing, or further large legal charges, could test how much flexibility management has around both dividends and capital deployment plans.
What Current Forecasts Assume For Marsh & McLennan Companies
Analysts are effectively sketching out a version of Marsh & McLennan Companies where steady top line expansion, higher margins and a lower share count work together. Revenue is assumed to rise by 4.1% a year over the next three years, while profit margins are expected to move from 14.2% today to 17.4% by around 2029. This would push more of each dollar of fees and commissions down to the bottom line.
Based on that view, earnings increase from US$4.0b today to US$5.5b by 2029, with some forecasters estimating as much as US$7.3b if everything goes right. The analyst framework also incorporates share repurchases that reduce the share count by 2.59% annually over the coming three years, so earnings per share growth relies not only on higher profits but also on fewer shares outstanding.
The valuation bridge is simple to describe, even if it is harder to fully agree with. To support current analyst targets, Marsh & McLennan Companies would need to be earning US$5.5b on revenues of US$31.5b in 2029, trade on a P/E of 20.6x at that point, and be discounted back at roughly 7.2% to 7.24%.
Marsh & McLennan Companies' narrative projects US$31.5b revenue and US$5.5b earnings by 2029. This assumes 4.1% yearly revenue growth and an earnings increase of US$1.5b from US$4.0b today.
Uncover why Marsh & McLennan Companies' fair value indicates a 23% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community cluster between about US$207 and US$285, which leaves plenty of room for disagreement on where Marsh & McLennan Companies should trade. When you set those opinions against risks from softer reinsurance pricing and prior litigation, you are reminded to weigh multiple angles before forming a stance.
Explore 3 other Marsh & McLennan Companies fair value estimates, including one that suggests it could be worth just $207.10!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Marsh & McLennan Companies research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Marsh & McLennan Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marsh & McLennan Companies' overall financial health at a glance.
Looking for more investment ideas beyond Marsh & McLennan Companies?
If the Archer by Marsh story has you thinking about portfolio balance, it can help to compare Marsh & McLennan Companies with other businesses that share some of the qualities you care about most.
- For investors who want resilient balance sheets and room for reinvestment, scan a curated list of solid balance sheet and fundamentals (25 results) to see which businesses meet that test.
- If value is your focus, weigh Marsh & McLennan Companies against 32 high quality undervalued stocks that combine strong fundamentals with prices some models view as appealing.
- Income oriented portfolios can benefit from a broader watchlist, so cross check Marsh & McLennan Companies with 6 dividend fortresses offering higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com