


Northern Star Resources (ASX:NST) has been thrown into the spotlight after Gold Fields walked away from a proposed A$38.5b takeover, following the Australian miner’s unanimous board rejection of the unsolicited offer.
For investors, the bigger picture matters. Northern Star Resources has seen its share price climb 23.88% over the past 90 days, despite a softer 30-day share price return of 6.01% and a year-to-date share price decline of 4.67%. Meanwhile, long-term total shareholder returns of 150.76% over three years and 186.78% over five years show how powerful compounding can be when sentiment eventually turns in a miner’s favour.
Spot similar gold producers that could be setting up for their own rerating by scanning our curated list of 36 elite gold producer stocks.The rejected A$38.5b bid and sharp share price swing have reset expectations around Northern Star Resources. Has most of the easy rerating already played out, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 5% Undervalued
On the widely followed narrative, Northern Star Resources screens as modestly undervalued, with a fair value estimate of A$24.57 against a last close of A$23.29. This leaves only a narrow pricing gap for investors to debate.
The recent acquisition and progression of the Hemi project, combined with a robust 10-year reserve-backed production profile, offers significant long-term production optionality and ensures continued exposure to increasing wealth and gold consumption in emerging economies, bolstering longer-term revenue prospects.
See why 87 investors see Northern Star Resources as 5% undervalued.
Result: Fair Value of A$24.57 (UNDERVALUED)
Still, the Northern Star Resources story can change quickly if cost pressures bite harder than expected or if large projects like Hemi and KCGM fall behind schedule.
Find out about the key risks to this Northern Star Resources narrative.
Another View: Northern Star Resources Through A Cash Flow Lens
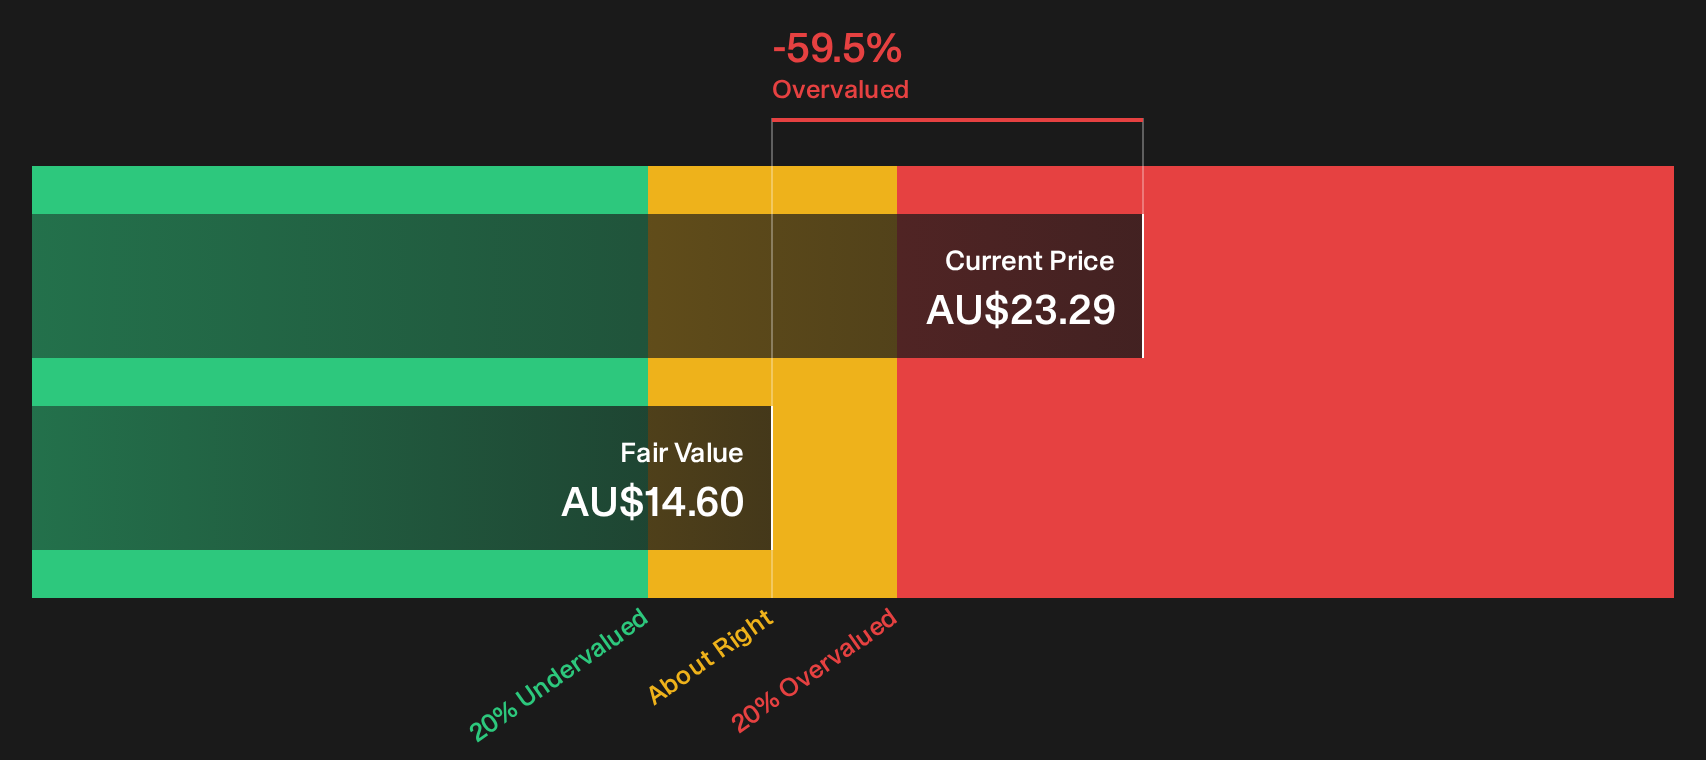
The SWS DCF model presents a very different view for Northern Star Resources. On this framework, the stock trades at A$23.29 compared with an estimated future cash flow value of A$14.60. This comparison suggests the shares appear expensive rather than modestly undervalued.
The gap between these figures implies that cash flows would need to be stronger, or risk would need to be lower than assumed, for today’s price to be fully supported. It raises a simple question for investors considering the Gold Fields approach and the analyst narrative: which set of assumptions seems more realistic over the long term?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Northern Star Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment clearly split on Northern Star Resources, it makes sense to move fast, test the assumptions yourself and decide where you stand. To see what optimism in the data looks like and what has impressed investors so far, start by reviewing the 2 key rewards.
Looking for more Northern Star Resources style ideas?
If you like how Northern Star Resources brings together quality assets and a clear story, broaden your watchlist with other targeted ideas using the Simply Wall St Screener.
- Target robust balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (11 results) that can help anchor the risk side of your portfolio.
- Hunt for pricing gaps where quality and valuation line up by reviewing a focused group of 5 high quality undervalued stocks that may deserve a closer look.
- Spot potential early-stage opportunities with room to mature by checking a refined pool of 15 high quality undiscovered gems before the wider market pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com