


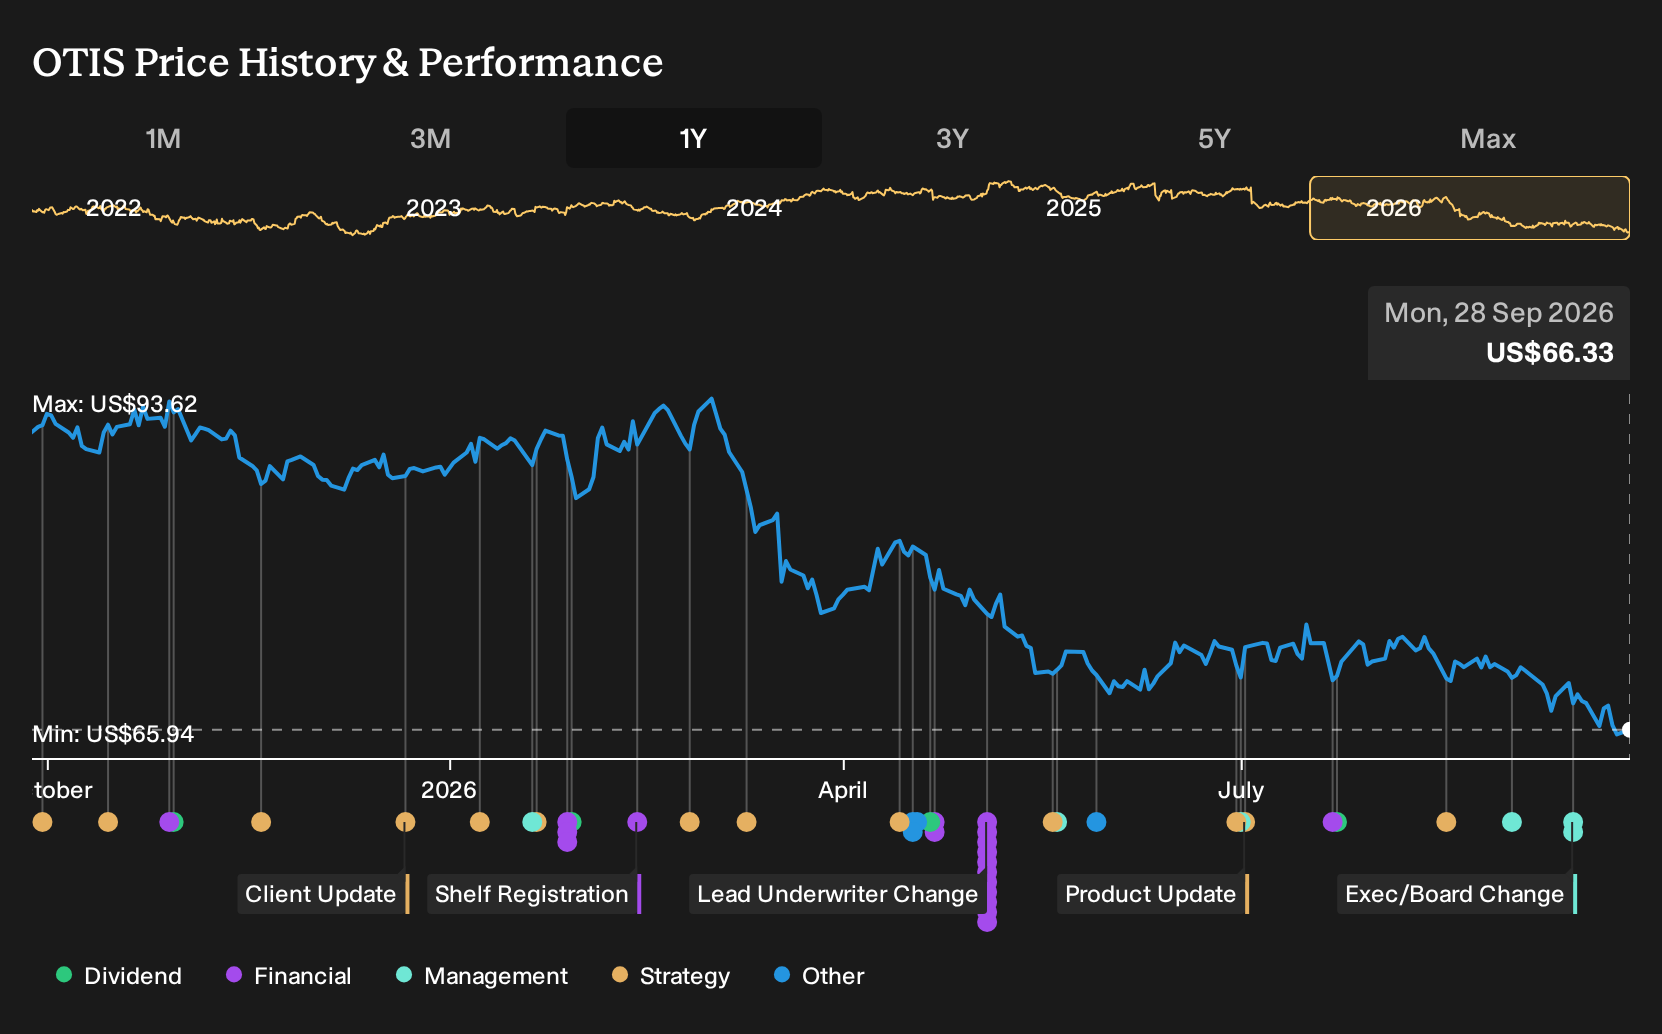
- Otis Worldwide reported that Judy Marks will retire as CEO, Chair, and President once a successor is appointed, with a transition and advisory period running through July 31, 2027, as the board conducts an internal and external search.
- The announcement comes after nearly nine years in which Marks led Otis Worldwide through its separation from United Technologies, a pivot toward a higher margin service mix, sizable returns of capital totaling US$8.4b, and expansion of its service portfolio to about 2.5 million units.
- We will now look at how Otis Worldwide's investment narrative could shift as investors assess leadership succession following Judy Marks' retirement.
Scan how investors are reacting to the Otis Worldwide leadership shift, and then compare it with 30 resilient stocks with low risk scores that might handle management transitions with less volatility.
Otis Worldwide Investment Narrative Recap
To stay invested in Otis Worldwide, you need to be comfortable with a story built on a large, recurring service base and the modernization backlog converting over time. The immediate operational swing factor is whether management can lift service margins back from recent compression while holding retention near current levels, which have softened slightly.
Judy Marks’ planned retirement does not change those near term levers much, given the long transition window and advisory role through July 2027. The bigger risk right now sits in execution on AI driven pricing, cost programs and service excellence efforts, especially after lower 2026 EPS guidance and recent margin pressure.
The most relevant recent development is Otis Worldwide’s push into AI driven micro pricing and connected service through the Otis ONE platform, now tied to about 1.1 million units. This sits right on top of the margin story, because the company is trying to use data and pricing tools to get more profit out of each contract.
There is a trade off. Management has already slowed the rollout of AI pricing to protect customer retention, while also dealing with US$50 million of unexpected productivity and cost headwinds. For you, the key question is how quickly this digital toolkit and the global service operating model can offset those pressures without further denting retention.
Otis Worldwide's narrative projects US$17.4b revenue and US$1.9b earnings by 2029. This assumes 5.2% yearly revenue growth and an earnings increase of about US$0.4b from US$1.5b today.
Uncover why Otis Worldwide's fair value indicates a 33% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses less on Otis Worldwide’s modernization backlog and more on slower earnings progress. The most cautious analysts were penciling in about US$16.9b of revenue and US$1.9b of earnings by 2029 before this CEO news, which is a softer path than consensus. Investors can use that gap to explore how leadership turnover might shift expectations in either direction.
Explore 5 other Otis Worldwide fair value estimates, including one that suggests it could be worth just $65.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Otis Worldwide research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Otis Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Otis Worldwide's overall financial health at a glance.
Looking For More Investment Ideas Beyond Otis Worldwide?
If this Otis Worldwide leadership story has you rethinking concentration risk, it can help to line it up against a wider watchlist. The Simply Wall St Screener lets you scan for other businesses that better match your risk, income, or valuation preferences, so you are not relying on a single stock to carry your thesis.
- For investors who care most about steady balance sheets and resilient fundamentals, start by checking a list of solid balance sheet and fundamentals (25 results) that can anchor a more durable portfolio.
- If value is your priority and you want companies where quality and price work in your favor, compare Otis Worldwide with a curated 32 high quality undervalued stocks that meet those criteria.
- Income focused investors who prefer to be paid while they wait can screen for a 6 dividend fortresses that align better with long term cash return goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com