


- Nike faces a critical earnings update after a stretch of weak demand in key regions, including the U.S., EMEA, and China, and rising concern about the pace of its turnaround.
- Operational questions around product execution, wholesale relationships, and competition from newer performance brands now matter more than analyst commentary in shaping how Nike’s recovery story is viewed.
- We will now look at how Nike’s slower than hoped recovery in core markets could reshape the investment narrative around the business.
Compare Nike’s reset story with other consumer and athletic brands under pressure by scanning our hand picked 32 high quality undervalued stocks, which may offer cleaner balance sheets or more straightforward recovery paths.
NIKE Investment Narrative Recap
Nike still hinges on a simple belief. You think the brand can convert its product reset toward sport performance, cleaner inventories, and a tighter marketplace into healthier revenue and margins over time. The key short term catalyst is execution around upcoming launches, wholesale sell through, and digital traffic as the fiscal 2027 reset takes shape.
The biggest immediate risk is that demand in North America, EMEA, and China stays weak while Nike is still working down older Sportswear and Jordan franchises. That would keep promotional activity elevated, pressure gross margin, and make the current earnings reset more painful without yet showing clear benefits from the new product cycle.
The fresh appointment of Alexandre Arnault to Nike’s board is the most notable development tied to this reset story. His background at LVMH, Tiffany, RIMOWA, Birkenstock, Carrefour, and Moncler gives the board another voice with experience in global brands, product storytelling, and premium positioning across different consumer categories.
The operational link is what matters for you. The board already has a long average tenure, and Arnault joins as Nike is trying to clean up inventory, lean into sport, and rebuild its wholesale and digital mix. If management execution around product, pricing, and channel discipline misfires, even a strong board will not offset the near term earnings and demand risks.
NIKE Consensus Expectations In Context
NIKE's narrative projects US$49.0b revenue and US$3.7b earnings by 2029. This implies 1.8% yearly revenue growth and a US$0.6b earnings increase from US$3.1b today.
Uncover why NIKE's fair value indicates a 40% potential upside to its current price, which could narrow quickly.
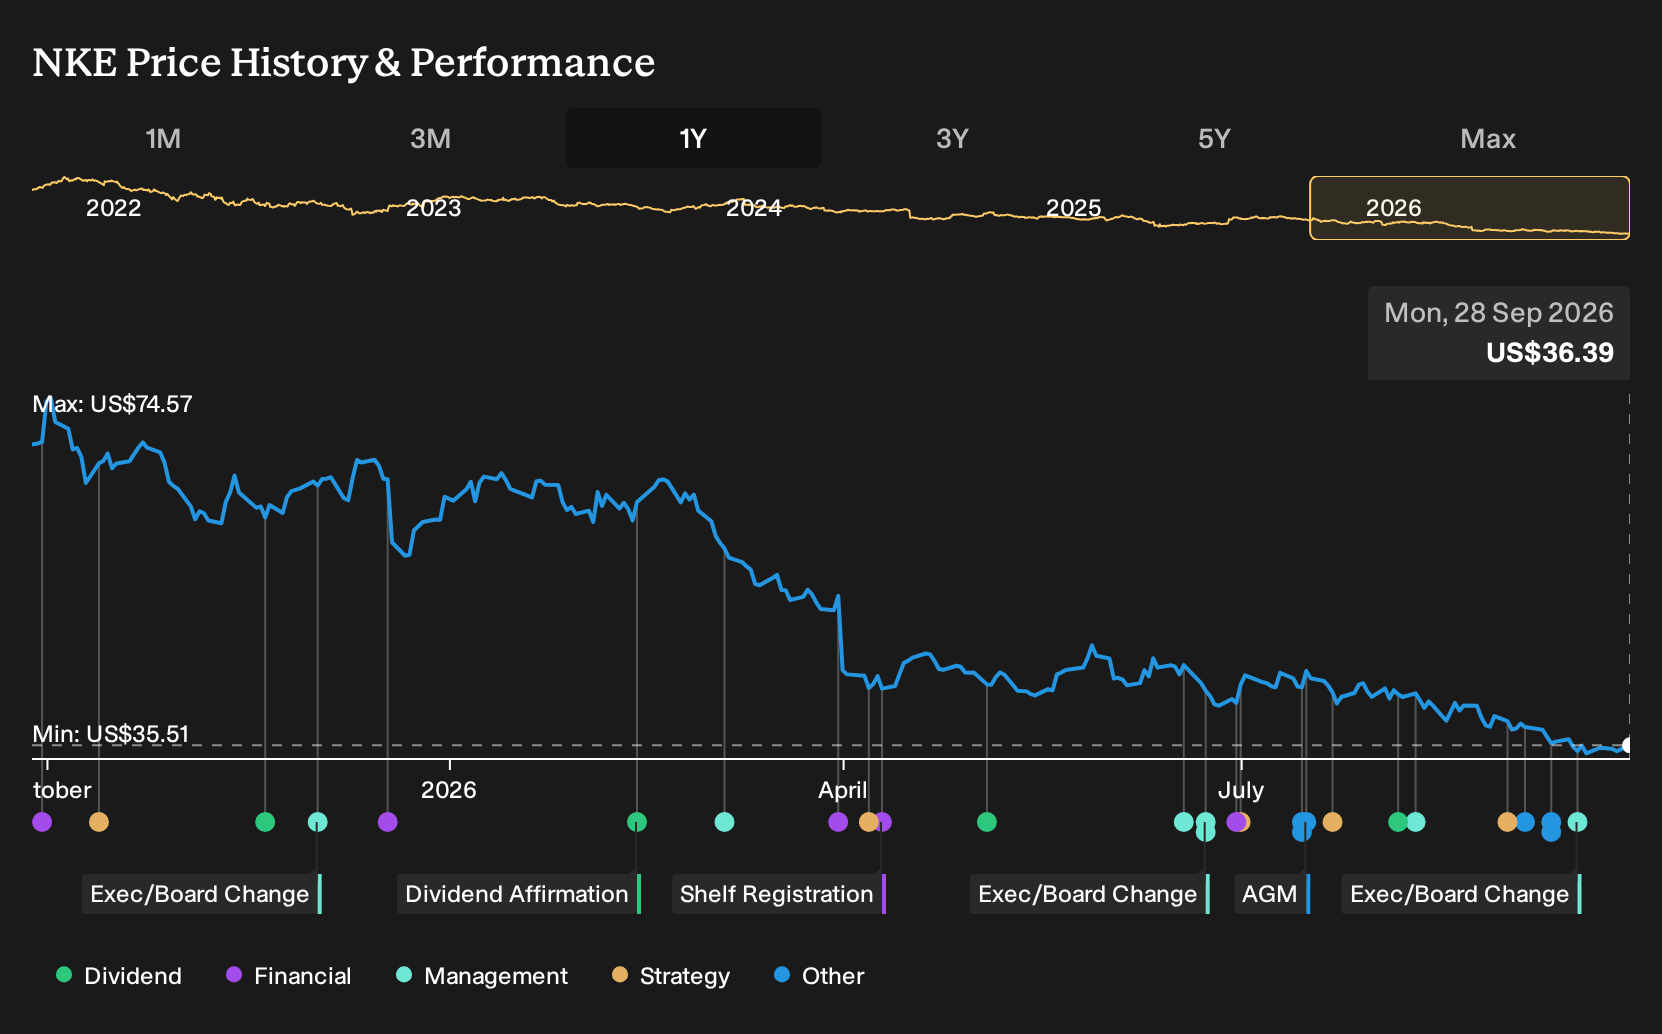
Exploring Other Perspectives
One alternate view emphasizes Alexandre Arnault as a catalyst. In that more optimistic story, board-level brand expertise could justify the bullish camp’s earlier forecasts of about US$51.4b in revenue and US$5.7b in earnings by 2029. That is far above the consensus US$49.0b and US$3.7b, and the new board news may push both narratives to adjust.
Explore 11 other NIKE fair value estimates, including one that suggests as much as 41% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your NIKE research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NIKE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NIKE's overall financial health at a glance.
Looking for more NIKE sized investment ideas?
If the NIKE story has you rethinking where risk and reward feel acceptable, it can help to widen the lens and compare it with other listed businesses that share some of the traits you care about most.
- For investors who care most about balance sheet strength and resilient financials, start with a list of solid balance sheet and fundamentals (25 results) that may handle tougher conditions with fewer funding pressures.
- If lower volatility and fewer financial red flags appeal to you, focus on a 30 resilient stocks with low risk scores that could suit a steadier approach than a single turnaround story.
- Those hunting for lesser known opportunities with robust fundamentals can scan a 16 high quality undiscovered gems that might sit off the usual radar yet still clear quality hurdles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com