


AEON Credit Service (Asia) closed at HK$9.10 after the market had a full day to process its latest earnings, with the stock barely moving over the past week. The calm price action hides a more interesting story. Revenue for Q2 2027 came in at HK$565.1 million while net income printed HK$122.8 million, keeping profitability solid for a consumer finance business that depends heavily on credit quality.
The bigger story sits beyond one quarter. Trailing twelve month earnings of HK$493.4 million and a P/E of 7.7x against higher industry averages keep the valuation debate very much alive.
Like the earnings power at AEON Credit Service (Asia) but want a wider set of value ideas with solid balance sheets to compare it against? Check out the list of solid balance sheet and fundamentals stocks (203 results)
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): HK$565.1 million vs. HK$336.1 million (up about 68.1%)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): HK$122.8 million vs. HK$124.3 million (down about 1.2%)
- Basic EPS (Q2 2027 vs. Q2 2026): HK$0.293 vs. HK$0.297 (down about 1.1%)
- Trailing 12 Month Net Income (to Q2 2027 vs. to Q2 2026): HK$493.4 million vs. HK$463.7 million (up about 6.4%)
Prefer clean charts instead of another wall of earnings figures and credit metrics for AEON Credit Service (Asia)? See the full visual breakdown of its valuation, including how the current P/E compares with its recent profit track record, in the company report for AEON Credit Service (Asia).
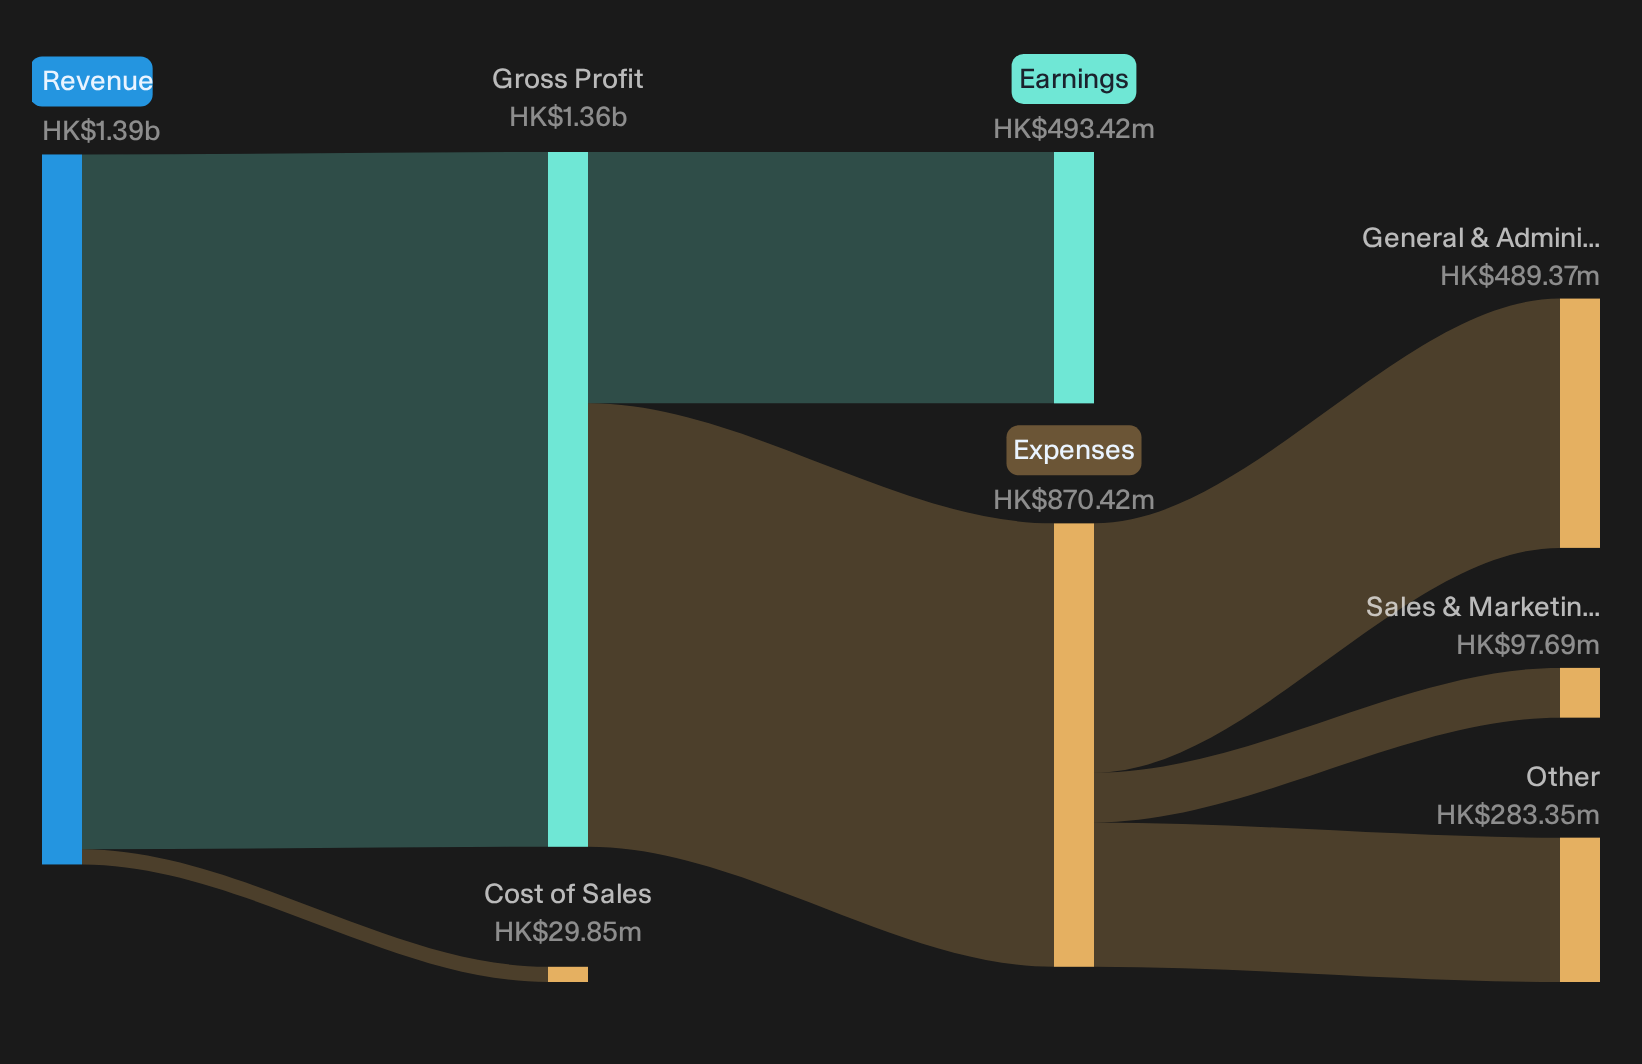
Revenue momentum supports steady AEON Credit story
For a lender like AEON Credit Service (Asia), the near 68.1% jump in quarterly revenue to HK$565.1 million backs the idea of a resilient spending engine. Trailing 12 month earnings of HK$493.4 million, modestly ahead of the prior period, keep the narrative of a mature, income oriented franchise intact. Net income for the quarter held close to last year at HK$122.8 million, which suggests growth in activity is not blowing up credit costs. For investors who prioritize stability over excitement, these numbers appear broadly supportive.
Soft profit trend leaves room for caution
The bear story does not disappear. Net income excluding extra items slipped slightly year on year, and basic EPS edged down from HK$0.297 to HK$0.293. That pattern hints at some pressure on unit profitability even as business volumes expand. Revenue growth without matching earnings progress can point to higher funding, marketing, or credit related costs. Share price performance also looks muted over 7 and 30 days, with returns near 0.4%, which suggests the market is not treating this quarter as a clear positive catalyst.
Review whether AEON Credit Service (Asia)'s muted share reaction is masking deeper funding and payout vulnerabilities. Explore the full risk profile in our risk analysis for AEON Credit Service (Asia) which shows 2 important warning signs.Take Charge Of Your Next Move
If the steady revenue and earnings profile at AEON Credit Service (Asia) has your attention, register for free with Simply Wall St and add it to your Watchlist to track the share price against fair value and wait for a setup that fits your plan. Once you hold the stock, keep your view clear with the Portfolio Command Center that highlights only the most important fundamental and valuation updates. For a wider viewpoint, compare your thinking with thousands of other investors through the Community and see how sentiment is shifting in real time. By spotting potential catalysts and risks early, you give yourself a better chance of staying ahead of the market rather than reacting to it.
Seeking Alternatives Beyond AEON Credit?
Fresh ideas move first, not last. While attention clings to today’s headlines, new breakout themes build momentum under the radar for now. Do the work before the crowd and act now.
- Spot cash rich businesses that could hold up when sentiment turns by reviewing a curated list of solid balance sheet and fundamentals stocks (203 results) before these opportunities get fully priced in.
- Chase income opportunities with staying power by scanning through 165 dividend fortresses while yields still look appealing and before demand compresses the payouts.
- Track the backbone of the AI build out by screening 87 AI infrastructure stocks while these enablers of data centers and chips remain under heavier radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com