


In the last week, the United States market has experienced a 1.5% decline, yet it remains up by 13% over the past year with earnings forecasted to grow by 18% annually. In such an environment, identifying growth companies with substantial insider ownership can be key as insiders often have unique insights into their company's potential and are willing to back it with personal investment.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Uxin (UXIN) | 34.3% | 72.9% |
| Upstart Holdings (UPST) | 14.0% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 61.3% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 22.8% | 22.3% |
| Karman Holdings (KRMN) | 14.4% | 56.4% |
| Himax Technologies (HIMX) | 29.2% | 70.2% |
| Dave (DAVE) | 16.7% | 23.6% |
| Carlyle Group (CG) | 27.4% | 22% |
| Almonty Industries (ALM) | 10.8% | 37.4% |
Let's review some notable picks from our screened stocks.
Amneal Pharmaceuticals (AMRX)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Amneal Pharmaceuticals, Inc. is a global biopharmaceutical company involved in the development, manufacturing, marketing, and distribution of generics, injectables, biosimilars, and specialty branded pharmaceutical products across various regions including the United States and India with a market cap of $6.89 billion.
Operations: Amneal Pharmaceuticals generates revenue from three main segments: Avkare ($732.28 million), Specialty ($574.73 million), and Affordable Medicines ($1.81 billion).
Insider Ownership: 38.2%
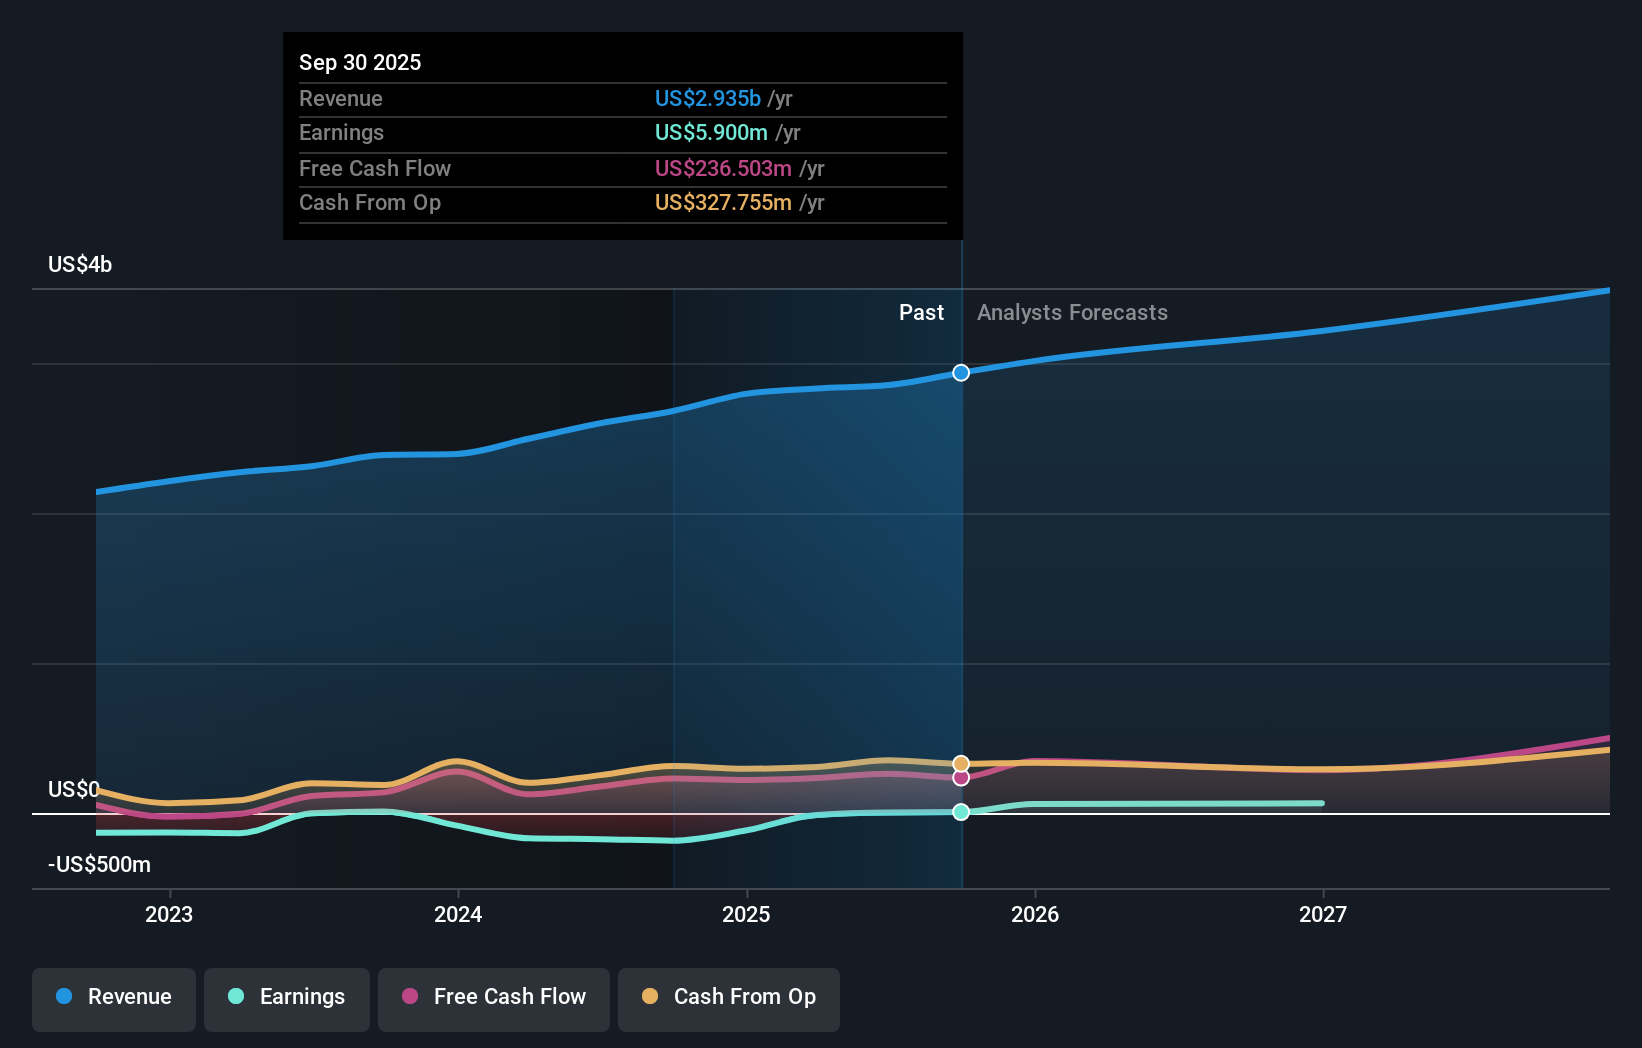
Amneal Pharmaceuticals is experiencing significant earnings growth, forecasted at 30.9% annually over the next three years, outpacing the broader US market. Despite trading below its estimated fair value and facing high-interest payments relative to earnings, insider ownership remains strong with more shares bought than sold recently. Recent FDA approvals for key products like lanreotide injection enhance its competitive positioning in the generic drug market, potentially driving future revenue growth despite slower forecasted revenue increases compared to the market.
- Navigate through the intricacies of Amneal Pharmaceuticals with our comprehensive analyst estimates report here.
- Upon reviewing our latest valuation report, Amneal Pharmaceuticals' share price might be too optimistic.
Accelerant Holdings (ARX)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Accelerant Holdings operates a data-driven risk exchange that links specialty insurance underwriters with risk capital partners and has a market cap of $4.29 billion.
Operations: The company's revenue is derived from three primary segments: Underwriting ($480.60 million), MGA Operations ($256.90 million), and Exchange Services ($385.90 million).
Insider Ownership: 25.5%
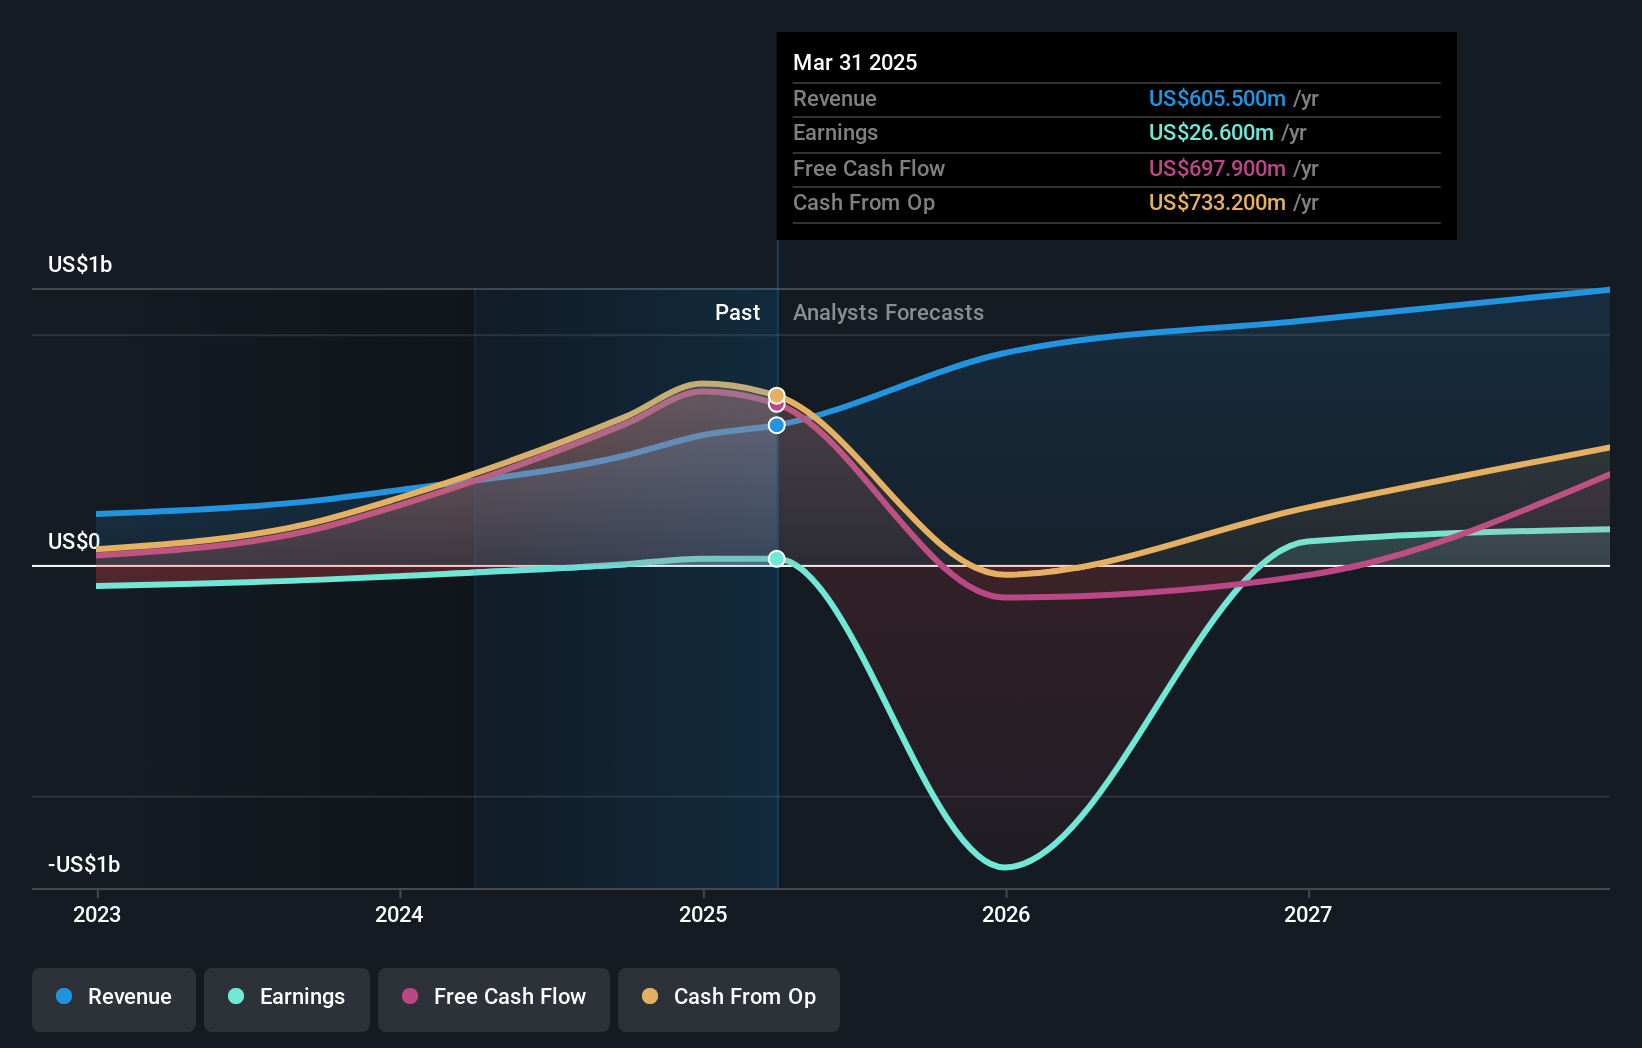
Accelerant Holdings is poised for significant earnings growth, with forecasts indicating a 138.87% annual increase over the next three years, surpassing market averages. Despite recent insider selling, substantial insider ownership remains intact. The company reported strong Q2 2026 results, with revenue of US$356.9 million and net income of US$78.7 million, both showing impressive year-over-year growth. An acquisition by Thoma Bravo at a premium price underscores confidence in Accelerant's strategic direction and potential for continued expansion within the specialty insurance market.
- Dive into the specifics of Accelerant Holdings here with our thorough growth forecast report.
- The analysis detailed in our Accelerant Holdings valuation report hints at an inflated share price compared to its estimated value.
Equity Bancshares (EQBK)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Equity Bancshares, Inc. is the bank holding company for Equity Bank, offering a variety of banking and financial services to both individual and corporate clients, with a market cap of approximately $995.85 million.
Operations: The company's revenue primarily comes from its banking operations, with Equity Bank generating $304.88 million in revenue.
Insider Ownership: 14.1%
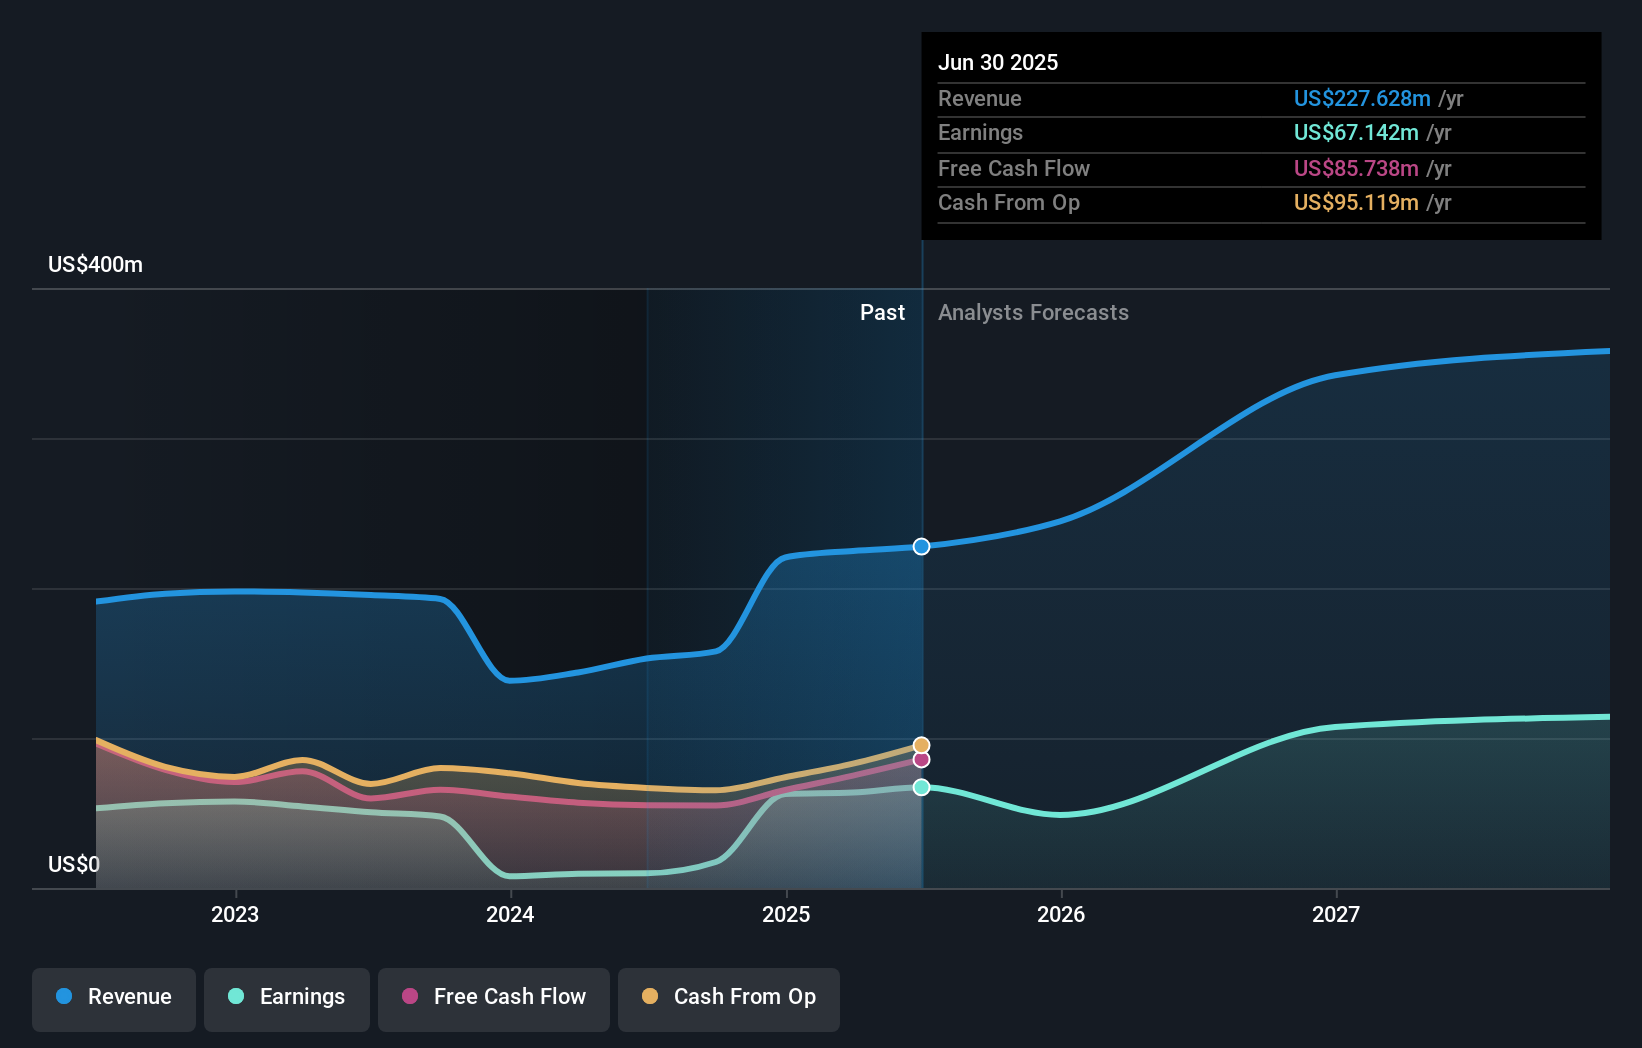
Equity Bancshares demonstrates potential for growth, with earnings forecasted to grow 40.32% annually over the next three years, outpacing the US market average. Recent insider activity shows more shares bought than sold, indicating confidence in its future prospects. The company reported strong Q2 2026 results with net interest income of US$73.87 million and net income of US$26.44 million, despite a decrease in profit margins from last year due to large one-off items impacting financials.
- Unlock comprehensive insights into our analysis of Equity Bancshares stock in this growth report.
- Our comprehensive valuation report raises the possibility that Equity Bancshares is priced higher than what may be justified by its financials.
Summing It All Up
- Unlock our comprehensive list of 183 Fast Growing US Companies With High Insider Ownership by clicking here.
- Looking For Alternative Opportunities? AI is about to change healthcare. These 133 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com