


Geopolitical friction around the Strait of Hormuz, after Donald Trump rejected Iran’s ceasefire offer, has kept oil markets unsettled and pushed Cardinal Energy (TSX:CJ) into sharper focus for investors tracking price sensitive producers.
Cardinal Energy’s share price has moved sharply over the year, with a 36.14% year to date share price return and a 10.01% 3 month share price return pointing to building momentum. A 62.62% 1 year total shareholder return and very large 5 year total shareholder return show how recent trading is layered on top of a strong longer run payoff profile.
Compare Cardinal Energy's recent oil price sensitivity with other producers by screening for 39 power grid technology and infrastructure stocks that could also react sharply to supply headlines out of the Strait of Hormuz.
Cardinal Energy has already delivered a sharp payoff for holders, which leaves new buyers weighing a quick entry against the risk of chasing strength. Is the current valuation still attractive at this level?
Most Popular Narrative: 35% Undervalued
Cardinal Energy’s most followed narrative assigns a fair value of CA$18.51 per share, compared with the recent close at CA$11.98. This puts the stock on a sizeable discount in that framework.
Low debt, with room to issue more to cover dividend or existing growth project if needed by YE 2025 as a low fiscal risk position. This allows for strategic M&A if a downturn occurs for pulling ahead of competition. Would like to see excess cashflow above plan from high oil prices toward debt targets of zero.
See why 22 investors see Cardinal Energy as 35% undervalued.
Result: Fair Value of CA$18.51 (UNDERVALUED)
Still, Cardinal Energy’s thesis leans heavily on supportive oil prices and continued low leverage. As a result, weaker crude or unexpected debt funded deals could quickly challenge that undervaluation story.
Find out about the key risks to this Cardinal Energy narrative.
Another View: Cardinal Energy Through Earnings Multiples
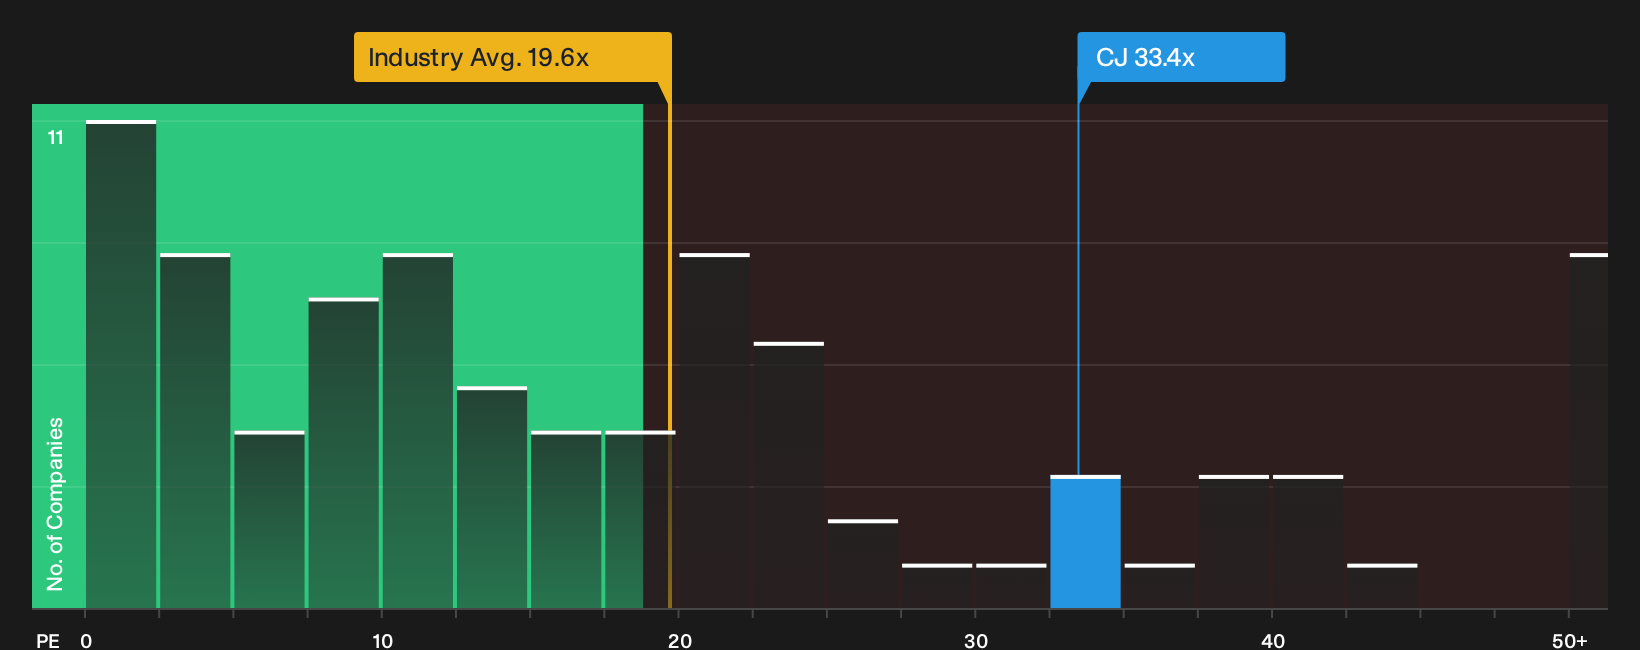
The fair value story around Cardinal Energy looks very different once you switch from narrative and user fair value estimates to plain P/E maths. At around CA$11.98, the stock trades on a P/E of 33.4x, which is meaningfully higher than the Canadian oil and gas group on 19.7x and above peer levels at 23.6x.
The fair ratio sits at 21x. This means the current multiple implies investors are already paying up for earnings, even though CJ is flagged as trading 58.2% below an estimated fair value. That gap between a rich P/E and a cheap fair value estimate raises a practical question for you: which signal should carry more weight when sizing risk on a new position?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Cardinal Energy so far. If you want to move before the next headline hits and pressure shifts sentiment again, start by weighing its 2 key rewards and 3 important warning signs.
Looking for more Cardinal Energy sized ideas?
Cardinal Energy may already be on your radar, but the real edge often comes from lining it up against a wider watchlist of fresh opportunities.
- Target potential mispricings by scanning a curated pool of companies that look statistically cheap on quality metrics through the 7 high quality undervalued stocks.
- Strengthen your income stream by reviewing resilient payers and researching the 1 dividend fortresses that match your yield and risk comfort.
- Dial down portfolio stress by focusing on steadier performers and using the 8 resilient stocks with low risk scores to spot candidates with more defensive profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com